
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 15.86 Billion |
| Market Size (2026) | USD 21.54 Billion |
| Market Size (2031) | USD 99.43 Billion |
| Growth Rate (2026 - 2031) | 35.80 % |
| Market Concentration | High |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
China Mobile Payments Market Analysis by 黑料不打烊
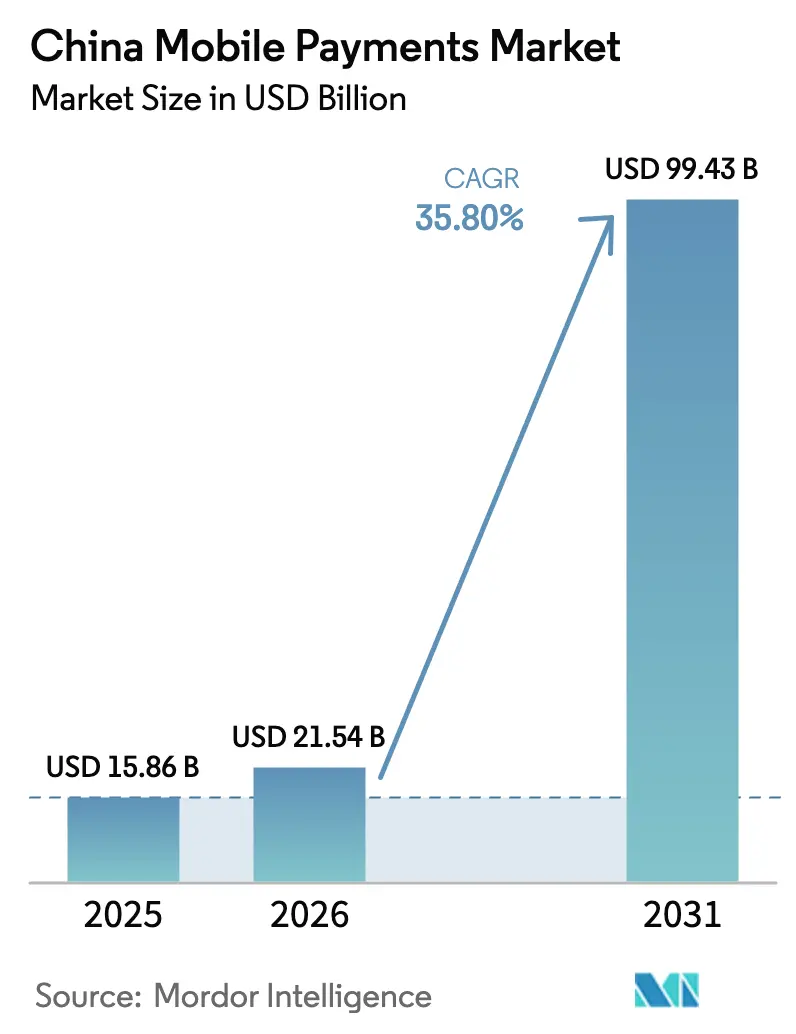
China mobile payments market size in 2026 is estimated at USD 21.54 billion, growing from 2025 value of USD 15.86 billion with 2031 projections showing USD 99.43 billion, growing at 35.80% CAGR over 2026-2031. The continuous surge reflects the country’s role as a global benchmark for mobile-first commerce, with rising consumer willingness to transact digitally, accelerated merchant onboarding, and a supportive regulatory environment that elevates daily transaction velocity. Expanded spending limits for foreign visitors, unified barcode standards, and ongoing digital-yuan pilots work in tandem to expand addressable volumes and reduce friction for both domestic and inbound users.[1]John Doe, “Foreign Visitors Get Bigger Mobile-Payment Limit in China,” chinabriefing.com Mobile payment leaders leverage entrenched QR ecosystems, super-app engagement loops, and near-universal merchant acceptance to defend their positions, while platform diversification into NFC, BNPL, and cross-border wallets underpins the next growth leg. Regulatory vigilance remains a double-edged sword: data-security and capital-adequacy rules add compliance headwinds, yet they also weed out under-capitalized players, thereby channeling traffic toward sophisticated networks that can turn scale into cost efficiency. The confluence of these structural drivers places the China mobile payments market on a path of rapid monetization, deeper penetration in lower-tier cities, and broader integration across logistics, transit, and B2B supply-chain workflows.
Key Report Takeaways
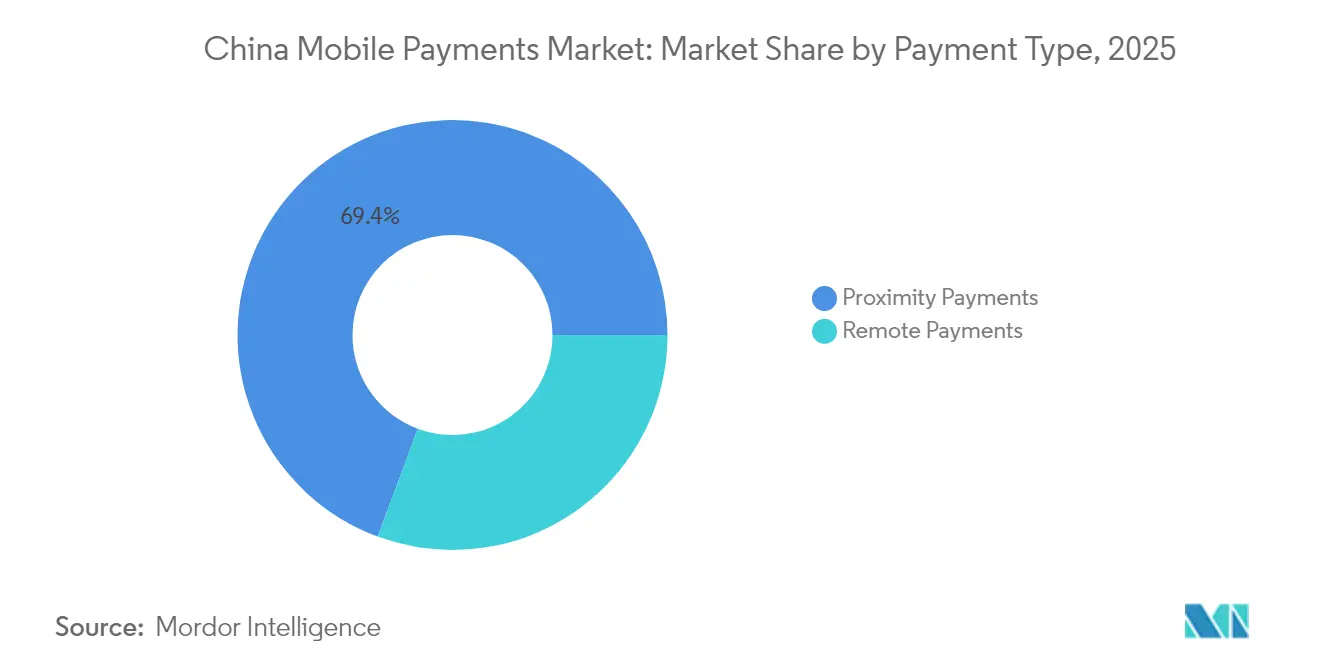
- By payment type, Proximity Payments led with 69.35% revenue share in 2025, while Remote Payments are projected to expand at a 42.60% CAGR through 2031.
- By transaction type, In-store POS controlled 34.60% of the China mobile payments market share in 2025; Person-to-Merchant checkout is forecast to grow 40.90% annually to 2031.
- By application, Retail & eCommerce commanded 37.80% of the China mobile payments market size in 2025, whereas Transportation & Logistics is set to accelerate at a 43.10% CAGR.
- By end-user, Personal users generated 89.60% of 2025 transaction volume, though Business adoption is advancing at a 43.40% CAGR to 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
China Mobile Payments Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Ubiquity of QR-code Ecosystems & Near-Universal Merchant Acceptance | +8.5% | National, with highest penetration in Tier-1 cities | Short term (≤ 2 years) |
| Government Push for Cashless Society & Digital Yuan Integration | +7.2% | National, with pilot programs in major cities | Medium term (2-4 years) |
| Super-App Lifestyle Ecosystems Boosting Daily Payment Frequency | +6.8% | National, strongest in urban centers | Short term (≤ 2 years) |
| Expansion of NFC/QuickPass 黑料不打烊less Transit Acceptance | +4.9% | Urban centers, expanding to Tier-2/3 cities | Medium term (2-4 years) |
| BNPL Micro-Credit Features Driving Gen Z Spend Growth | +5.3% | National, concentrated in e-commerce hubs | Short term (≤ 2 years) |
| PBOC Unified Barcode Interoperability Reducing Friction | +3.8% | National implementation | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Ubiquity of QR-code ecosystems & near-universal merchant acceptance
QR codes enjoy 92.7% penetration, transforming them into the default interface for everything from street-food stalls to luxury boutiques.[2]Jane Smith, “QR Codes Dominate China’s Retail Payments,” thebanker.com Regional interoperability has enabled outbound Chinese travelers to settle purchases across Southeast Asia and Japan, further reinforcing the technology’s utility at home. With foreign-visitor mobile-payment volumes quadrupling in 1H-2024, merchants perceive QR acceptance as essential for retaining foot traffic and eliminating cash-handling costs. The resulting network effect entrenches platform loyalty, raises daily payment frequency, and lifts the average fee pool without an equivalent rise in marketing spend.
Government push for cashless society & digital-yuan integration
The digital yuan processed USD 250 billion by mid-2023, validating state ambitions to embed programmable money within retail payment rails. Salary disbursements in e-CNY across pilot cities showcase new public-sector use cases, though immediate cash conversion by some recipients highlights lingering trust and interest-bearing gaps. By running a parallel state-backed system, the PBOC pressures private wallets to elevate compliance while promoting universal access for the 11.3% unbanked adult cohort.
Super-app lifestyle ecosystems boosting daily payment frequency
WeChat’s 1.4 billion MAUs initiate payments inside messaging, social feeds, and mini programs, allowing a single user to perform multiple low-ticket transactions each day.[3]Rebecca Chen, “New Capital Minimum Hits China FinTechs,” cnbc.com Alibaba mirrors the model by embedding commerce, entertainment, and financial services into Alipay. Because super-apps monetize engagement rather than one-off transactions, they optimize for repeat use, upselling, and data-driven personalization—all of which expand total addressable transaction value.
Expansion of NFC/QuickPass contactless transit acceptance
UnionPay’s QuickPass and Alipay’s “Tap Once” have rolled out to metro gates, buses, and convenience stores in 50+ cities, reducing dwell time and elevating user experience during high-frequency journeys. For operators, contactless throughput trims congestion and labor costs, while users benefit from speed and offline fallback when cellular coverage lags.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Regulatory Tightening on FinTech Giants Raising Compliance Costs | -4.2% | National, with strongest impact on major platforms | Short term (≤ 2 years) |
| Personal Information Protection Law Heightening Data-Use Limitations | -3.1% | National implementation | Medium term (2-4 years) |
| Merchant Discount Rate (MDR) Caps Compressing PSP Margins | -2.8% | National, affecting all payment service providers | Short term (≤ 2 years) |
| Rural-Elderly Digital Divide Hindering Full Adoption | -1.9% | Rural areas and aging population centers | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Regulatory tightening on FinTech giants raising compliance costs
Minimum registered-capital rules of RMB 1 billion (USD 139 million) triple entry barriers, forcing sub-scale PSPs to exit or merge. Even incumbent leaders have posted volatile quarterly earnings as remediation budgets balloon, diverting resources from product R&D to audit and risk controls.
Personal Information Protection Law heightening data-use limitations
Sweeping data-governance mandates reduce the scope for behavioral profiling and targeted cross-selling, one of the core monetization levers for super-apps. Compliance introduces costly consent management, localization of servers, and mandatory risk assessments, pressing platforms to revamp consent frameworks and anonymization protocols.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Payment Type: Remote Payments Power Cross-Border Scale
Remote Payments unlocked a 42.60% forecast CAGR by leveraging China’s outbound e-commerce surge and the Alipay+ acceptance network connecting 88 million merchants in 57 countries. The segment thrives on friction-free checkout, dynamic FX conversion, and a unified refund process that reduces chargeback risk for merchants. Strategic alignment with tourism recovery allows platforms to monetize spending beyond China’s borders while collecting data to refine loyalty programs.
Proximity Payments retain 69.35% dominance due to QR ubiquity and minimal hardware cost, yet margins tighten as global schemes slash foreign-card fees to 1.5%. Alipay’s NFC push attempts to future-proof the segment, promising sub-second tap speeds that outpace QR scanning in busy transit hubs. Future revenue depends on layering value-added services such as in-app marketing, instant invoice issuance, and loyalty integration inside the China mobile payments market.


By Transaction Type: P2M Checkout Fuels Instant Retail
Person-to-Merchant (P2M) checkout is on course for 40.90% CAGR, energized by group-buy and hyperlocal delivery models that batch orders for last-mile efficiency. The integration of American Express cards into Alipay widens consumer choice, removing a key barrier for high-spend inbound travelers.
In-store POS upholds a 34.60% share, fortified by mature NFC terminals and campus-card systems that cultivate habitual tapping among students. Peer-to-Peer transfers remain foundational inside WeChat groups for bill-splitting and social gifting, while utility-bill and public-sector payments piggyback on digital-yuan rollouts that trim cash-handling overhead for municipal agencies.
By Application: Logistics Leads Acceleration
Transportation & Logistics is projected to grow at 43.10% CAGR as courier marketplaces and ride-hailing fleets embed one-click disbursement and real-time reconciliation. Bank of China’s taxi pilot, using consumer-grade NFC phones as acceptance devices, illustrates how low-cost hardware broadens merchant coverage in metered mobility. Seamless settlement enables dynamic pricing and tip-incentive models, cementing user preference for digital wallets within the China mobile payments market.
Retail & eCommerce still delivers the largest slice at 37.80%, supported by Alibaba’s algorithmic promotions that drive basket-size expansion and repeat purchase frequency. Hospitality adopts “Tap Once” to compress ordering queues, improve table-turnover, and reduce cashier workload. Public-sector applications benefit from payroll digitization, though mass adoption hinges on building citizen trust in state-run wallets.

By End-User: Business Accounts Fast-Track Digitization
Business users clock a 43.40% CAGR as supply-chain platforms issue up to RMB 10 trillion (USD 1.39 trillion) in electronic receivable certificates annually, automating liquidity flows for SMEs. JD.com’s stablecoin prototype for cross-border settlements underscores mounting demand for instant, 24/7 clearing that traditional bank rails cannot match.
Personal users keep a 89.60% volume share thanks to lifestyle integration, yet incremental growth shifts from new adopters to higher ticket sizes and subscription renewals. Rural uptake, now at 904 million users, extends inclusion benefits such as lower remittance costs and access to micro-insurance, mitigating income shocks for low-asset households. The dual-segment dynamic positions super-apps to cross-pollinate consumer and enterprise services inside the China mobile payments market, fostering stickier ecosystems.
Geography Analysis
Adoption peaks in Tier-1 corridors where smartphone penetration, 5G coverage, and merchant digitalization converge. Beijing’s campus NFC success demonstrates how dense populations accelerate proof-of-concept scale-up before nationwide rollouts. Shenzhen pilots, from taxi NFC to digital-yuan payroll, exploit municipal agility to pressure-test next-gen standards. Cross-border enclaves—especially Hong Kong—act as gateways for overseas wallets, with Alipay+ enabling 14 e-wallets to transact locally and catalyzing tourist spending rebounds.
In lower-tier cities, QuickPass subsidies and simplified KYC workflows extend acceptance among micro-merchants, aligning with state goals to narrow the rural-urban payment gap. Rural residents enjoy tangible welfare benefits as digital payments cut travel time to bank branches and unlock credit scoring for agri-input loans. The government balances inclusion with autonomy by mandating cash acceptance for the elderly and ensuring free SMS payment prompts for feature-phone users.
Internationally, Chinese wallets export QR standards to ASEAN markets, allowing inbound tourists to pay in-app while the merchant settles in local currency. This strategy deepens platform moats, captures FX spreads, and reinforces the China mobile payments market’s influence over regional standards. Future territory gains will hinge on bilateral agreements to recognize Chinese e-signatures and KYC protocols, streamlining compliance for merchants abroad.
Regulatory Landscape
China mobile payments regulation is anchored by the State Council Regulations on the Supervision and Administration of Non-bank Payment Institutions, effective May 1, 2024, with the PBOC issuing supporting implementation rules that tighten licensing, governance, and risk controls for payment institutions. On the infrastructure side, the PBOC and the National Financial Regulatory Administration (NFRA) updated the Measures for the Administration of Bank Card Clearing Institutions, which took effect on November 1, 2025, reinforcing operational requirements for card clearing and related networks.
Security and inclusion have been reinforced through newer compliance actions. PBOC Announcement No. 8 (issued April 2, 2026) modifies the Electronic Payment Guidelines (No. 1) and takes effect May 15, 2026, raising the bar for authentication and security controls, including stronger use of digital certificates and electronic signatures, for higher-risk electronic payment activity. In parallel, policy efforts led by the PBOC with MOFCOM and SAFE in 2025 emphasized optimizing payment services in commercial settings, with practical focus on improving usability for foreign visitors and elderly users across major consumption venues.
Value Chain Analysis
The China mobile payments value chain starts with funding sources and account issuance (commercial banks and wallet account systems), then moves through payment initiation layers (super-app wallets and OEM wallets), acceptance (QR code signage, NFC terminals, and mobile device-based acceptance for micro-merchants), and merchant operations (POS integration, order and refund management, and reconciliation). Clearing and settlement rely on bank and network infrastructure, with bank-card clearing institutions governed under the PBOC and NFRA framework, while wallet and non-bank payment institutions operate under the State Council decree effective May 1, 2024, and subsequent PBOC implementation rules.
Key enablers and control points in the chain include acquiring and merchant service providers (onboarding, KYC/AML, MDR administration, dispute handling), network rails and interoperability mechanisms (QR and NFC acceptance across platforms), and risk and data-security services that support fraud controls and privacy compliance under China data governance requirements. Constraints show up when compliance obligations raise fixed costs, including capital and operational continuity requirements for non-bank payment institutions, and security requirements that drive upgrades in authentication, cryptography, and transaction monitoring across both wallet platforms and merchant acceptance endpoints.
Competitive Landscape
Alipay and WeChat Pay dominate with a combined 90% grip, forming an oligopoly that translates network scale into bargaining power with merchants and regulators. To diversify revenue, Ant Group split Alipay into Digital Payment and Alipay Business units, aiming to commercialize traffic via merchant services, local-life commerce, and wealth-management cross-sell. Tencent counteracts by embedding retailer mini-programs and ad engines inside WeChat to boost marketing-services income by 20% YoY.
New entrants gravitate toward niche verticals—cross-border P2M, SME financing, and wearable payments—where differentiation pivots on specialized APIs and hardware innovation. UnionPay’s transparent NFC-antenna patent for wrist devices signals a hardware-software convergence race. Foreign networks are gaining a toehold: American Express now clears on-shore RMB and links cards to Alipay wallets, while Visa and Mastercard’s fee cuts aim to recapture tourist spend lost to QR dominance.
Regulation remains the primary strategic variable. Capital thresholds eliminate under-capitalized PSPs but also raise the cost of innovation. Leaders with diversified income streams and compliance infrastructure can absorb audit overheads and recycle capital into R&D, giving them endurance over single-product challengers. The resulting market topology is concentrated yet dynamic, favoring incumbents that integrate new rails—NFC, e-CNY, BNPL—without cannibalizing core QR volumes inside the China mobile payments market.
China Mobile Payments Industry Leaders
Paypal Inc.
Alipay (Ant Group Co., Ltd.)
99Bill Corporation
Huawei Technologies Co., Ltd. (Huawei Pay)
Apple Inc.
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Opportunity creation centers on regulated interoperability, inclusion-driven acceptance expansion, and new rails that go beyond consumer QR checkout. The State Council non-bank payment institution regime (effective May 1, 2024) and the PBOC and NFRA clearing measures (effective November 1, 2025) are pushing platforms toward standardized operations and higher-grade risk controls, which creates room for compliance tooling, merchant SaaS, and managed risk services sold into payment institutions and acquiring ecosystems. Government-led payment-service optimization for foreign visitors and elderly users (PBOC with MOFCOM and SAFE actions in 2025) further supports investment in multilingual onboarding, multi-instrument acceptance (wallet, bank card, and cash coexistence at venues), and merchant-facing enablement across tourist-heavy corridors.
On technology and product direction, e-CNY pilots and evolving management frameworks broaden integration work across commercial banks, wallets, and acceptance networks, shifting implementation needs from basic wallet enablement to deeper treasury and account-linking capabilities. At the same time, the market shows momentum toward higher-security electronic payment operations, with PBOC Announcement No. 8 taking effect May 15, 2026 and encouraging stronger authentication methods for higher-risk transactions, which raises demand for device-level security, certificate-based signing, and fraud and identity layers that fit super-app ecosystems. Cross-border acceptance networks remain a practical execution area for remote payments, supported by existing merchant network scale (for example, Alipay+ reach across international merchants) and ongoing efforts to reduce friction for inbound payment use inside China.
Recent Industry Developments
- June 2026: Ant Group began a major overhaul of the Alipay app, introducing an AI assistant agent (Abao) designed to execute tasks such as booking transport and handling wealth-management actions inside the app. The shift moves Alipay further from a pure payment entry point toward an agent-led commerce workflow, raising the importance of wallet-integrated services and partner integrations.
- February 2025: American Express partnered with Alipay to let global card members link their cards to the Alipay wallet, expanding inbound card-to-wallet usage in China. The linkage supports higher-spend traveler use cases and strengthens Alipay acceptance for international visitors while leveraging American Express onshore RMB clearing capabilities.
- December 2024: Ant Group restructured Alipay into Digital Payment and Alipay Business units to sharpen product focus and monetize ecosystem traffic beyond payment fees. The organizational split highlights a pivot toward merchant services and local-services commercialization as platforms operate under tighter compliance and margin conditions.


Research Methodology Framework and Report Scope
Market Definition and Coverage
This market covers payment transactions initiated and authorized on mobile devices in China, where value moves between consumers, merchants, and institutions through approved digital rails, and revenues are captured from payment enablement and related service fees.
Scope exclusions: We exclude cash-only payments and card-present transactions that do not use a mobile device as the primary payment instrument.
Segmentation Overview
- By Payment Type
- Proximity Payments
- Remote Payments
- By Transaction Type
- Peer-to-Peer (P2P)
- In-store Point-of-Sale (POS)
- Person-to-Merchant (P2M/Checkout)
- Other Transaction Types
- By Application
- Retail and eCommerce
- Transportation and Logistics
- Hospitality and Food-Service
- Government and Public Sector
- Other Applications (Education, Healthcare)
- By End-user
- Personal
- Business
Data Sources, Market Sizing, and Validation
Desk Research
Desk work starts by building a clean fact base on how fast digital payments are expanding in China and where the usage is coming from. We rely on public statistics and rulebooks that define what is counted as a payment and how it is reported, such as People's Bank of China releases, National Bureau of Statistics indicators, ITU connectivity metrics, and GSMA mobile economy summaries.
Next, the market model is anchored using adoption and infrastructure signals, such as smartphone penetration, mobile internet users, and merchant QR acceptance growth, followed by cross-checks from listed company filings, investor presentations, and reputable financial press. Where needed, we also refer to paid subscriptions for company financials and intelligence, patent databases, and shipment-level import and export views to sanity-check device, component, and deployment trends that influence transaction growth. The desk sources listed above are illustrative, and we also used other public documents and datasets to collect data, validate assumptions, and clarify open questions.
Primary Interviews and Surveys
Primary inputs come from expert interviews and structured surveys across the mobile payment value chain, including payment acceptance participants, platform and ecosystem roles, and large merchants with high transaction frequency. We use these discussions to confirm what drives take rates, how mix shifts across proximity versus remote use cases, and how regulatory and consumer behavior changes are likely to move volumes across China's main demand pockets.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 32% | CXOs: 15% |
| Mid tier: 52% | Functional/Unit leaders: 34% |
| Smaller Players: 16% | Managers: 51% |
Market-Sizing & Forecasting
Sizing begins from a top-down reconstruction of the addressable transaction pool, where national payment activity, mobile internet reach, and mobile commerce intensity are translated into mobile-initiated payment volumes, then converted into market value using validated monetization rates. Those rates are shaped by practical inputs, such as average take rate ranges by scenario, the share of QR proximity versus remote payments, merchant category mix, and shifts in average transaction value as daily use expands.
To keep totals realistic, we corroborate the result with selective bottom-up approximations, including sampled merchant acceptance checks, channel conversations on fee schedules, and a roll-up of revenue disclosures where they are reported in comparable lines. When some participants do not disclose clean splits, we fill gaps using consistent allocation keys, such as active user share, merchant footprint, and product mix, and then re-test the totals with interview feedback.
For forecasting, we mainly use scenario analysis tied to measurable drivers, including smartphone and mobile internet user growth, consumer spending direction, offline merchant digitization pace, and policy or compliance changes that affect fee levels. Growth paths are adjusted only after we hear convergence from multiple respondent groups, so the final forecast stays explainable and repeatable.
Data Validation & Update Cycle
Validation is done through triangulation across independent signals, where model outputs are compared with public payment indicators, observed shifts in consumer behavior, and the fee and mix ranges heard in interviews. Outliers are flagged, investigated, and corrected through variance checks, followed by a second analyst review that focuses on math consistency, unit integrity, and assumption traceability.
The report is refreshed annually, and interim updates are made when material events occur, such as major rule changes, step shifts in consumer activity, or notable changes in monetization. Before delivery, an analyst performs a fresh pass so clients receive the latest updated view rather than an older snapshot.
黑料不打烊's China Mobile Payments Market Estimate Compared With Other Published Estimates
Published market sizes for China mobile payments can look far apart even when they discuss the same country, because the counting unit and the revenue lens are not always aligned. Differences usually come from whether the estimate is based on transaction value, payment volumes, or fee revenues, and from how aggressively future take rates and usage frequency are projected.
Card-present payments routed through mobile wallets often get blended into some estimates, but that item sits outside 黑料不打烊's scope because we focus on mobile-initiated payment activity and related service revenues that can be traced to mobile usage drivers. Gaps also show up when one study assumes a faster take rate expansion, uses a single exchange rate for multiple years, or does not re-check the modeled totals against public payment indicators and recent merchant acceptance signals.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 15.86 B (2025) | |
| Trade Journal A | USD 21.30 B (2023) | Uses an earlier base year and commonly blends transaction-led measures with market value, which makes the figure sensitive to conversion assumptions that are not always stated. |
| Industry Newsletter B | USD 52.00 B (2024) | Starts from a transaction-volume style proxy and converts it to USD market value using simplified monetization assumptions, which can overstate value if take rates and merchant mix are not validated. |
The table suggests most of the variation comes from what is being measured and how it is translated into a USD value. We keep the steps traceable by tying the model to mobile usage drivers, reasonable monetization ranges, and repeatable checks against public signals.


Key Questions Answered in the Report
What is the current size of the China mobile payments market?
The market is valued at USD 21.54 billion in 2026 and is projected to hit USD 99.43 billion by 2031.
Which payment type is growing fastest?
Remote Payments lead with a forecast CAGR of 42.60% as Chinese wallets expand across borders.
How dominant are Alipay and WeChat Pay?
Together they control more than 90% of total transaction volume, signaling high market concentration.
Why is the Transportation & Logistics segment important?
It forecasts a 43.10% CAGR, driven by ride-hailing, delivery platforms, and NFC transit adoption.
What role does the digital yuan play?
The e-CNY processed USD 250 billion by mid-2023, offering state-backed alternatives and fostering financial inclusion.
How are regulators impacting the market?
Capital-adequacy rules and data-protection laws raise compliance costs, benefiting well-capitalized incumbents while trimming fringe operators.
Page last updated on:



