
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 109 Billion |
| Market Size (2026) | USD 113.90 Billion |
| Market Size (2031) | USD 141.94 Billion |
| Growth Rate (2026 - 2031) | 4.50 % |
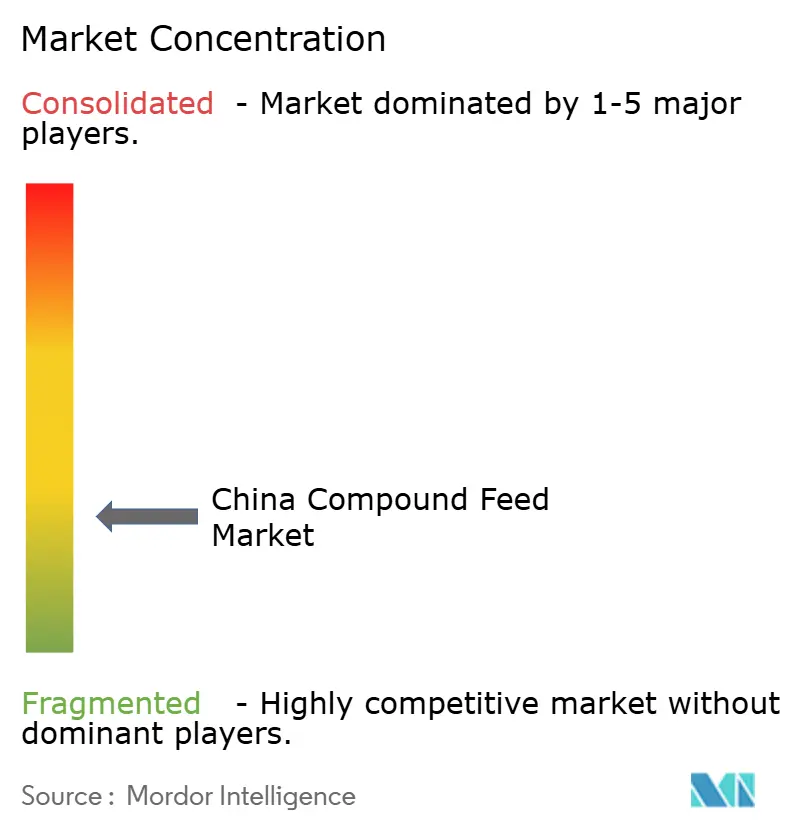
| Market Concentration | Low |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. |
|
China Compound Feed Market Analysis by 黑料不打烊
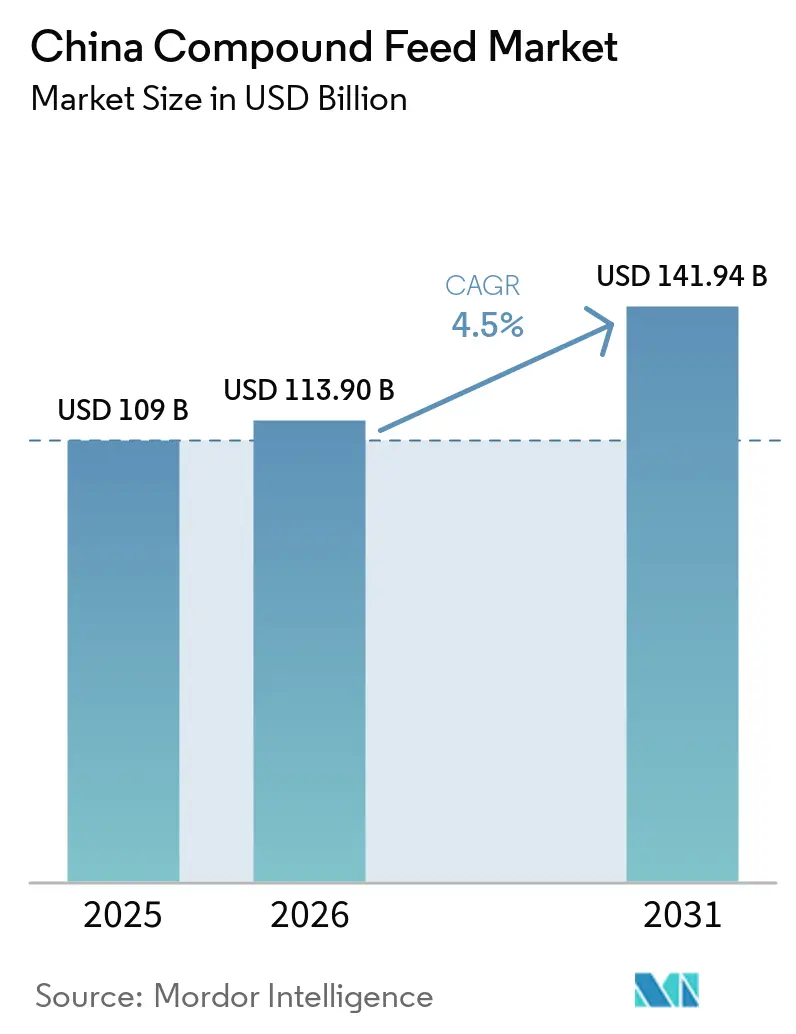
The China compound feed market was valued at USD 109.00 billion in 2025 and is forecast to grow from USD 113.90 billion in 2026 to USD 141.94 billion by 2031, at a CAGR of 4.50% during the forecast period from 2026 to 2031. The market is supported by recovering feed demand, rising animal protein consumption, the expansion of commercial aquaculture, and a shift from self-mixed feed toward standardized commercial products. According to the USDA Foreign Agricultural Service (USDA FAS) in 2026, China's total feed and residual use is forecast to reach 293 million metric tons in marketing year 2026/27, slightly higher than in MY 2025/26, supported by anticipated higher feed demand from the poultry and aquaculture sectors[1]Source: USDA FAS, "Grain and Feed Update-China - People's Republic of ," apps.fas.usda.gov. Major suppliers are investing in aquafeed capacity, formulation capabilities, and digital production systems, while volatility in soybean and corn prices continues to pressure margins.
Key Report Takeaways
- By animal type, swine is the largest segment and held 50.0% of the China compound feed market share in 2025, while aquaculture is the fastest-growing segment and is forecasted to expand at a 6.2% CAGR between 2026 and 2031.
- By ingredient, cereals are the largest segment and held 41.0% of the China compound feed market size in 2025, while supplements are the fastest-growing segment and are forecasted to expand at a 6.4% CAGR between 2026 and 2031.
- By form, mash is the largest segment and held a 44.0% share in 2025, while pellets are the fastest-growing segment and are forecasted to expand at a 6.0% CAGR between 2026 and 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
China Compound Feed Market Trends and Insights
\
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Demand for Animal-Based Protein in China | +0.9% | China-wide, with East, South, and Central China as demand centers | Long term (≥ 4 years) |
| Industrialization of Poultry and Swine Farming | +0.8% | Central China, North China, and Southwest China | Medium term (2-4 years) |
| Expansion of Commercial Aquaculture and Specialized Aquafeed | +0.7% | Guangdong, Fujian, and Hubei | Long term (≥ 4 years) |
| Adoption of Low-Protein, Precision-Nutrition Formulations | +0.5% | Guangdong, Shandong, and Jiangsu | Medium term (2-4 years) |
| Growth of Integrated Livestock and Feed Operations | +0.5% | Henan, Sichuan, and Shandong | Long term (≥ 4 years) |
| Digitalization and Automation of Feed Mills and Farm Feeding | +0.4% | Jiangsu, Guangdong, and Shandong | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Rising Demand for Animal-Based Protein in China
Rising demand for animal-based protein is supporting the China compound feed market because feed is a key input for commercial livestock and aquaculture production. The continued expansion of livestock, poultry, and aquaculture production is increasing the need for formulated feeds tailored to different species, growth stages, and production systems. In particular, the development of commercial aquaculture is supporting demand for specialized aquafeed formulations, while sustained poultry and livestock production continues to generate demand for compound feed across major animal categories. According to the United States Department of Agriculture Foreign Agricultural Service (USDA FAS) in 2026, feed use accounts for approximately 65% of China's total corn consumption, while poultry feed is anticipated to become the main growth engine for corn demand in MY2026/27[2]Source: USDA FAS, "Grain and Feed Update-China - People's Republic of ," apps.fas.usda.gov. The increasing commercialization of animal production and the shift toward more standardized feeding practices are further supporting the adoption of commercially manufactured feed products. As a result, the China compound feed market benefits from a diversified animal-protein production base spanning livestock, poultry, and aquaculture rather than relying solely on swine feed demand.
Industrialization of Poultry and Swine Farming
The transition from small-scale and mixed farming systems toward larger, more commercialized livestock operations is expanding the customer base for commercial feed manufacturers and increasing the use of standardized feeding programs. According to the China Feed Industry Association in 2026, bulk compound feed accounted for 53.4% of total compound feed output in 2025, up 4.1 percentage points from 2024, indicating a continued shift toward commercially supplied feed and centralized procurement. The growing scale of poultry production is also supporting demand for formulated feed, while larger swine farms increasingly rely on standardized nutrition and professionally managed feeding systems. At the same time, China's efforts to manage sow inventories may moderate swine feed demand in the near term, creating a more balanced growth outlook across livestock segments. USDA FAS reported that sow inventories had declined to 39.61 million head at the end of 2025, close to the government target, while weak hog prices and tighter margins were anticipated to limit further herd expansion. Overall, the increasing scale, standardization, and professionalization of poultry and swine farming are supporting the adoption of commercial compound feed, particularly among large-scale producers.
Expansion of Commercial Aquaculture and Specialized Aquafeed
Commercial aquaculture represents an important growth channel for the China compound feed market because the production of different fish and aquatic species requires specialized nutritional formulations. According to the China Feed Industry Association in 2026, aquafeed production reached 11.1 million metric tons in the first half of 2026, increasing 17.4% year on year, while marine-species feed increased 34.7% during the same period. This growth reflects the recovery of aquaculture activity and increasing demand for species-specific feed products. BioMar announced in February 2026 that it would expand its Wuxi production facility by adding 50,000 metric tons of capacity, with the new line designed to serve high-end species and produce specialized feed for Japanese eel, grouper, mandarin fish, and early-life-stage fish, commissioning is anticipated in the first quarter of 2027. The expansion of specialized aquafeed capacity indicates increasing opportunities for higher-value feed products as China's aquaculture industry becomes more commercialized and diversified.
Adoption of Low-Protein, Precision-Nutrition Formulations
Feed manufacturers in China are increasingly adopting lower-protein, amino-acid-balanced formulations to reduce reliance on soybean meal while maintaining the nutritional requirements of livestock and poultry. According to the Ministry of Agriculture and Rural Affairs of China (MARA) in 2023, a three-year action plan targeted reducing the proportion of soybean meal in animal feed from 14.5% in 2022 to below 13% by 2025. The shift toward lower-protein diets is being supported by the use of synthetic amino acids, alternative protein meals, and precision formulation techniques that enable feed manufacturers to meet nutritional requirements with lower soybean meal inclusion. According to MARA in 2024, soybean meal accounted for 12.9% of feed ingredients during January–October 2024, down 0.5 percentage points from the corresponding period of the previous year. These formulation practices can reduce feed manufacturers' exposure to imported soybean costs while increasing demand for feed additives, amino acids, formulation expertise, and technically differentiated compound feed products. The adoption of precision nutrition is therefore supporting the development of more resource-efficient feed formulations, particularly among larger commercial farms.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Swine-Cycle Volatility and Periodic Herd Destocking | -0.7% | Sichuan, Henan, Hunan, with national effects | Short term (≤ 2 years) |
| Dependence on Imported Soybean Meal and Volatile Corn Costs | -0.8% | Shandong, Henan, and Jiangsu | Medium term (2-4 years) |
| Feed-Safety, Environmental, and Antibiotic-Reduction Compliance Costs | -0.5% | Guangdong, Shandong, Jiangsu, and nationwide | Medium term (2-4 years) |
| Disease Outbreaks and Biosecurity Disruptions | -0.6% | Liaoning, Sichuan, and Hunan | Short term (≤ 2 years) |
| Source: 黑料不打烊 | |||
Dependence on Imported Soybean Meal and Volatile Corn Costs
Raw materials represent a major share of compound feed production costs, making fluctuations in soybean and corn prices an important constraint on feed manufacturers' margins. China remains highly dependent on imported soybeans for its feed industry, with soybean imports reaching approximately 105 million metric tons in 2024, with Brazil accounting for the largest share of supply[3]Source: USDA FAS, "Biotechnology and Other New Production Technologies Annual," apps.fas.usda.gov. At the same time, corn prices can fluctuate with domestic supply, inventories, and feed demand. USDA Foreign Agricultural Service (USDA FAS) anticipated that large Chinese feed mills used 6% more corn in feed rations during the first seven months of 2025 than the average level in the previous year, highlighting the importance of corn availability and pricing to feed manufacturers. The combination of imported soybean exposure and changing domestic corn requirements can increase formulation costs and make it more difficult for feed manufacturers to maintain stable margins. These cost pressures can also influence ingredient substitution and formulation decisions, particularly when the relative prices of soybean meal, corn, and alternative protein or energy sources change.
Swine-Cycle Volatility and Periodic Herd Destocking
Swine feed remains a major volume category in China's compound feed industry, making feed demand sensitive to changes in the national hog herd and breeding-sow inventory. Periodic fluctuations in hog prices, producer profitability, and breeding capacity can trigger cycles of herd expansion, restocking, and destocking, resulting in corresponding changes in swine feed demand. The Ministry of Agriculture and Rural Affairs (MARA) has also introduced measures to manage breeding capacity and improve the balance between hog supply and market demand. While these measures are intended to reduce excessive production capacity and moderate future supply fluctuations, adjustments in herd size can still create short-term volatility in feed consumption. Consequently, compound feed manufacturers remain exposed to cyclical changes in the swine industry, which can affect production volumes, capacity utilization, and revenue stability.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Animal Type: Swine Leads Volume While Aquaculture Adds Value
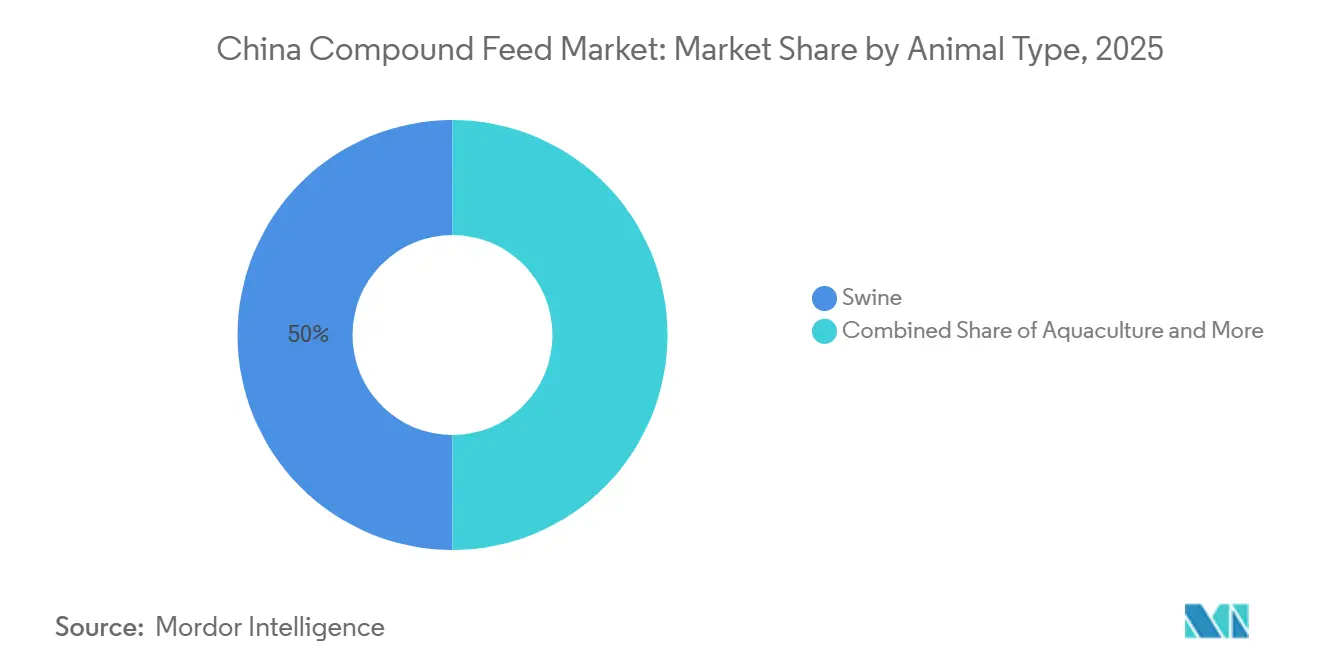
Swine accounted for 50.0% of the China compound feed market in 2025, making it the largest animal-type segment. Its substantial production base gives swine feed a major influence on feed mill utilization and raw material demand. Poultry meat feed and layer feed also represent significant segments of China's compound feed industry, while ruminant feed maintains a smaller but established position. The large swine-feed base reflects the continued importance of pork production in China's livestock sector, although the segment remains exposed to fluctuations in hog inventories, producer profitability, and the swine production cycle.
Aquaculture is forecast to be the fastest-growing animal-type segment, expanding at a 6.2% CAGR between 2026 and 2031. The segment is supported by the continued commercialization of aquaculture and increasing demand for species-specific formulations. Premium feed for shrimp, marine finfish, eel, and other high-value species requires specialized nutritional formulations and processing capabilities, supporting opportunities for higher-value aquafeed products. The expansion of aquaculture therefore provides an additional growth channel for China's compound feed industry alongside its large swine-feed base.


By Ingredient: Cereals Remain the Largest Segment While Supplements Record the Fastest Growth
Cereals accounted for 41.0% of the China compound feed market by ingredient in 2025, making them the largest segment, as corn and wheat remain key energy sources in livestock and poultry feed formulations. According to the USDA Foreign Agricultural Service (USDA FAS) in 2026, corn feed and residual use in China is forecast to reach 241 million metric tons in MY2026/27, increasing 0.4% from the previous marketing year. The Chinese Government is also encouraging greater diversification of feed ingredients, with a longer-term objective of reducing the combined share of grains and oilseeds in feed. Cakes and meals remain important protein sources, while changes in relative ingredient prices and government policies are encouraging feed manufacturers to evaluate alternative protein and energy sources.
Supplements are forecast to be the fastest-growing ingredient segment, expanding at a 6.4% CAGR between 2026 and 2031. Amino acids, enzymes, vitamins, and other feed additives enable manufacturers to formulate diets with greater nutritional precision and support the development of lower-protein formulations. The increasing adoption of precision nutrition is particularly relevant as feed manufacturers seek to reduce soybean meal inclusion while maintaining animal performance. Supplements also allow feed mills to tailor formulations according to animal species, age, production stage, and nutritional requirements, supporting continued demand for specialized feed formulations. The shift toward more efficient and technically optimized diets is therefore anticipated to support the faster growth of the supplements segment.
By Form: Mash Retains a Large Base While Pellets Gain Ground
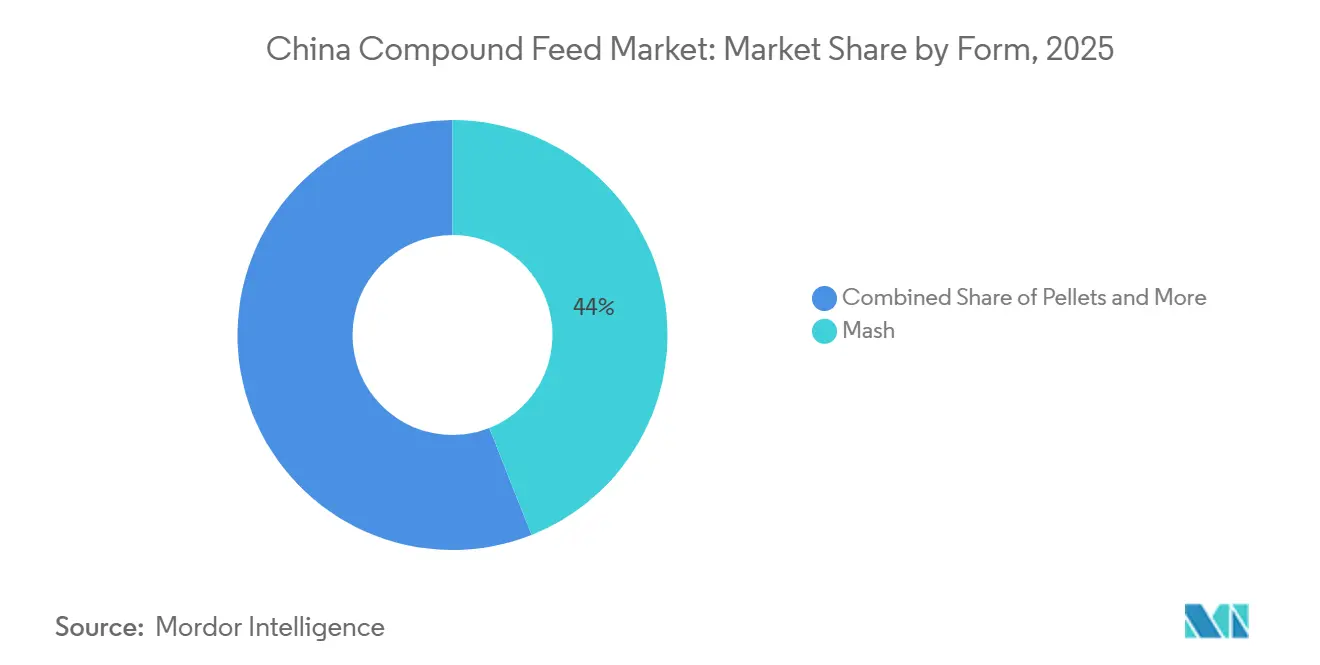
Mash accounted for 44.0% of the China compound feed market by form in 2025, making it the largest segment. Its continued use is supported by established feeding practices across livestock production and its relatively simple handling and production requirements. Mash can be supplied in bulk and integrated into existing farm feeding systems, supporting its continued adoption among commercial livestock producers. Crumbles serve more specialized applications, particularly in early-stage poultry feeding, while liquid feed remains a smaller segment because of its greater handling and distribution requirements. The established use of mash across China's livestock sector provides the segment with a substantial installed base despite increasing adoption of processed feed forms.
Pellets are forecast to be the fastest-growing form segment, expanding at a 6.0% CAGR between 2026 and 2031. Pelleting provides greater uniformity in feed composition and particle size and can improve handling, storage, and feed distribution efficiency. These characteristics are particularly relevant for aquaculture, poultry, and other commercial feeding systems requiring consistent feed quality. The continued shift toward standardized commercial feed supply and the expansion of larger, professionally managed farms are supporting demand for pelleted products. As feed manufacturers and producers increasingly prioritize consistency, logistics efficiency, and precise nutrient delivery, pelletized feed is anticipated to gain share over the forecast period.
Geography Analysis
Geography Analysis
Shandong was the largest provincial market for compound feed in China, supported by its large livestock and poultry production base, established feed manufacturing industry, and well-developed agricultural supply chains. Guangdong represented the fastest-growing provincial market, supported by its strong aquaculture industry, extensive feed manufacturing capacity, and access to established coastal supply chains. The geographic structure of China's compound feed market varies across provinces because livestock concentration, aquaculture activity, crop production, and feed logistics differ considerably by region.
Fujian and Guangxi benefit from established aquaculture and livestock production, creating demand for both conventional and specialized feed products. Fujian's marine aquaculture base supports demand for specialized diets for marine finfish, shrimp, and eel, while Guangxi combines swine, poultry, and freshwater aquaculture production. Sichuan also remains an important market because of its large swine production base. Other major agricultural provinces, including Hunan, Jiangxi, Hubei, Henan, Jiangsu, and Anhui, have diversified combinations of livestock, poultry, aquaculture, and grain production, supporting demand across multiple feed categories.
Investments in integrated livestock production can support regional demand for commercial feed as hog and poultry production capacity expands. In contrast, more mature feed markets in provinces such as Hebei and Liaoning may offer comparatively lower incremental demand from further farm formalization, while geographically dispersed markets in northeastern, northwestern, and autonomous regions can face greater logistics challenges and continued use of self-mixed feed. Consequently, coastal aquaculture clusters and integrated livestock-producing regions provide distinct growth opportunities within China's compound feed market.
Competitive Landscape
The China compound feed market is fragmented, with Guangdong Haid Group Co., Limited, New Hope Liuhe Co., Ltd., Wens Foodstuff Group Co., Ltd., Tongwei Co., Ltd., and Beijing Dabeinong Technology Group Co., Ltd. representing some of the major players in 2025. Competition is centered on compound feed production, species-specific nutrition, aquafeed, livestock feed, feed formulation, distribution, and integrated production services. Guangdong Haid Group Co., Limited and New Hope Liuhe Co., Ltd. compete through large-scale feed production and broad product portfolios covering livestock, poultry, and aquaculture, while Guangdong Wens Foodstuff Group Co., Ltd. combines feed production with integrated livestock operations. Tongwei Co., Ltd. has a strong position in aquafeed and aquatic production, while BioMar Group focuses on specialized and premium aquaculture nutrition through its partnership with Tongwei.
Competitive differentiation is increasingly shifting from feed volume alone toward specialized nutrition, aquafeed formulations, production efficiency, and digitalized feed operations. Guangdong Haid Group Co., Limited and New Hope Liuhe Co., Ltd. benefit from scale, broad distribution networks, and diversified animal-feed portfolios, while Tongwei Co., Ltd. and BioMar Group compete through specialized aquafeed products for higher-value aquatic species. BioMar Group and Tongwei Co., Ltd. are expanding their Wuxi joint-venture facility in 2026 by adding a second production line and 50,000 metric tons of additional capacity, supporting specialized diets for species including Japanese eel, grouper, and mandarin fish. Guangdong Wens Foodstuff Group Co., Ltd. is also adopting digital technologies, including its Zhiliao Tong feed prediction and scheduling system, which integrates demand forecasting, feed-mill scheduling, and logistics management. These developments indicate increasing emphasis on formulation expertise, operational efficiency, and specialized feed solutions.
The market also provides opportunities for companies to adapt feed products to China's diverse livestock and aquaculture production systems. Coastal provinces with large aquaculture industries create opportunities for specialized marine and freshwater aquafeed, while major swine- and poultry-producing regions support demand for conventional compound feed. Larger integrated farms provide opportunities for companies offering standardized formulations, technical services, digital planning, and reliable bulk supply, while specialized aquaculture operations can support demand for premium species-specific diets. Consequently, competitive advantage is increasingly determined by a company's ability to combine production scale with specialized nutrition, formulation capabilities, distribution networks, digital operations, and technical support rather than by feed manufacturing capacity alone.
China Compound Feed Industry Leaders
-
Guangdong Haid Group Co., Limited
-
New Hope Liuhe Co., Ltd. (New Hope Group Co., Ltd.)
-
Wens Foodstuff Group Co., Ltd.
-
Tongwei Co., Ltd. (Tongwei Group Co., Ltd.)
-
Beijing Dabeinong Technology Group Co., Ltd.
- *Disclaimer: Major Players sorted in no particular order

Recent Industry Developments
- June 2026: Tongwei Agricultural Development Co., Ltd. unveiled its shrimp feed microparticle production base at Jiangsu Tongwei and launched the Tongwei Beyond series of shrimp fry feed. The build-out included four high-end fry-feed production lines, supported by an additional CNY 15 million (USD 2.08 million) investment made in 2025, expanding Tongwei's capacity for specialized early-life-stage shrimp nutrition.
- February 2026: BioMar Group, through its joint venture with Tongwei Co., Ltd., announced the expansion of its Wuxi aquafeed facility with a second production line. The expansion will add 50,000 metric tons of capacity and enable production of advanced nursery feeds and specialized feeds for high-value species including Japanese eel, grouper, and mandarin fish. Commissioning is anticipated in Q1 2027.
- April 2025: China's Ministry of Agriculture and Rural Affairs (MARA) issued the Implementation Plan for the Grain-Saving Action in Animal Husbandry Sector, promoting precision feed formulation, low-protein diets, alternative non-grain feed resources, and digitalized feeding and feed-formulation systems. The plan targets reducing the share of grain in feed consumed by the animal husbandry sector to around 60% and soybean meal to around 10% by 2030.


China Compound Feed Market Report Scope
Compound feed is a mixture of raw materials and supplements fed?to the livestock, sourced from either plant,?animal,?organic or inorganic substances or industrial processing, whether or not containing additives. While soybean, corn, barley, wheat, and sorghum are the most commonly used raw materials, vitamins, minerals, and amino acids?are the most common additives blended to form compound feed.
The China Compound Feed Market Report is Segmented by Animal Type (Ruminants, Poultry, Swine, Aquaculture, and Other Animal Types), by Ingredient (Cereals, Cakes and Meals, By-Products, and Supplements), and by Form (Pellets, Mash, Crumbles, and Liquid). The Market Forecasts are Provided in Terms of Value (USD).
By Animal Type
| Ruminants |
| Poultry |
| Swine |
| Aquaculture |
| Other Animal Types (Equine, etc.) |
By Ingredient
| Cereals |
| Cakes and Meals |
| By-products |
| Supplements |
By Form
| Pellets |
| Mash |
| Crumbles |
| Liquid |
| By Animal Type | Ruminants |
| Poultry | |
| Swine | |
| Aquaculture | |
| Other Animal Types (Equine, etc.) | |
| By Ingredient | Cereals |
| Cakes and Meals | |
| By-products | |
| Supplements | |
| By Form | Pellets |
| Mash | |
| Crumbles | |
| Liquid |


Key Questions Answered in the Report
What is the size of China’s compound feed sector?
The sector is USD 113.90 billion in 2026 and is forecasted to reach USD 141.94 billion by 2031, at a 4.50% CAGR.
Which animal feed category has the largest share in China?
Swine feed held 50% of compound feed volume in 2025.
Which feed category is forecasted to grow the fastest?
Aquaculture feed is forecasted to expand at a 6.2% CAGR from 2026 to 2031, supported by specialized diets for farmed aquatic species.
Why are feed mills reducing soybean meal use?
Lower soybean meal inclusion can reduce exposure to imported soybeans, while amino acids and supplements help maintain nutritional targets.
Page last updated on:


 Your data is secure and never sold or shared.


