
Car Subscription Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Market Size (2026) | USD 6.12 Billion |
| Market Size (2031) | USD 17.52 Billion |
| Growth Rate (2026 - 2031) | 23.41 % |
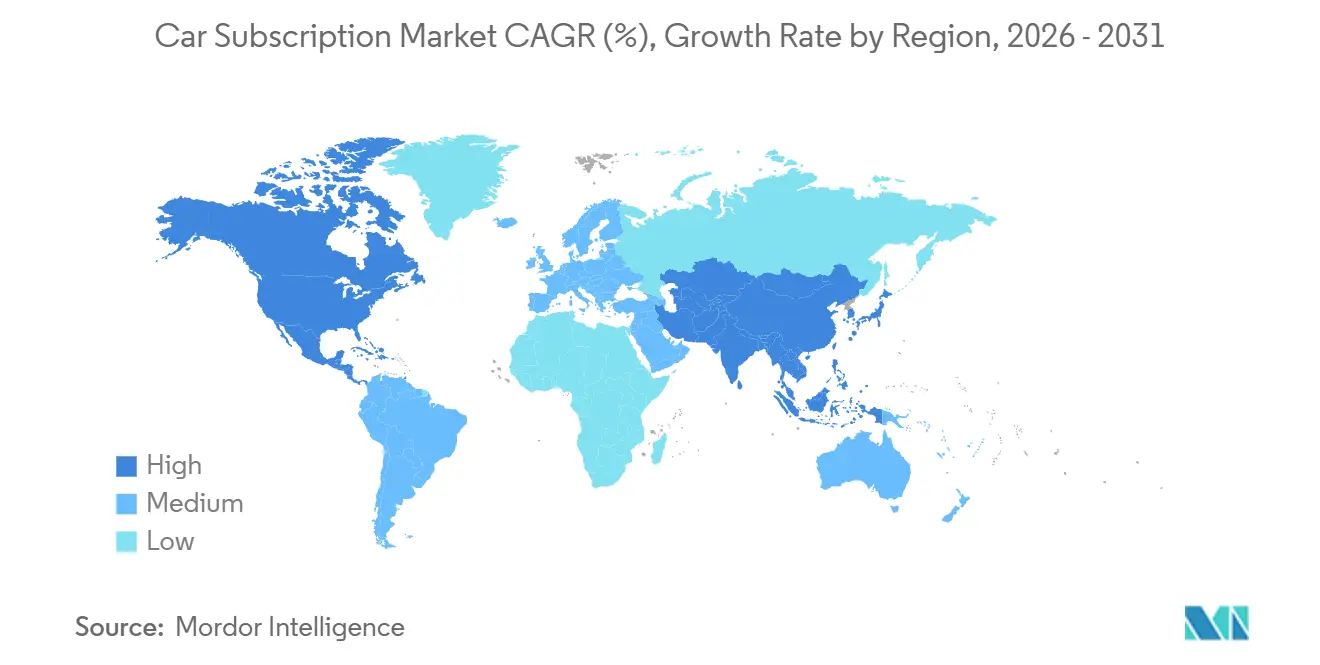
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
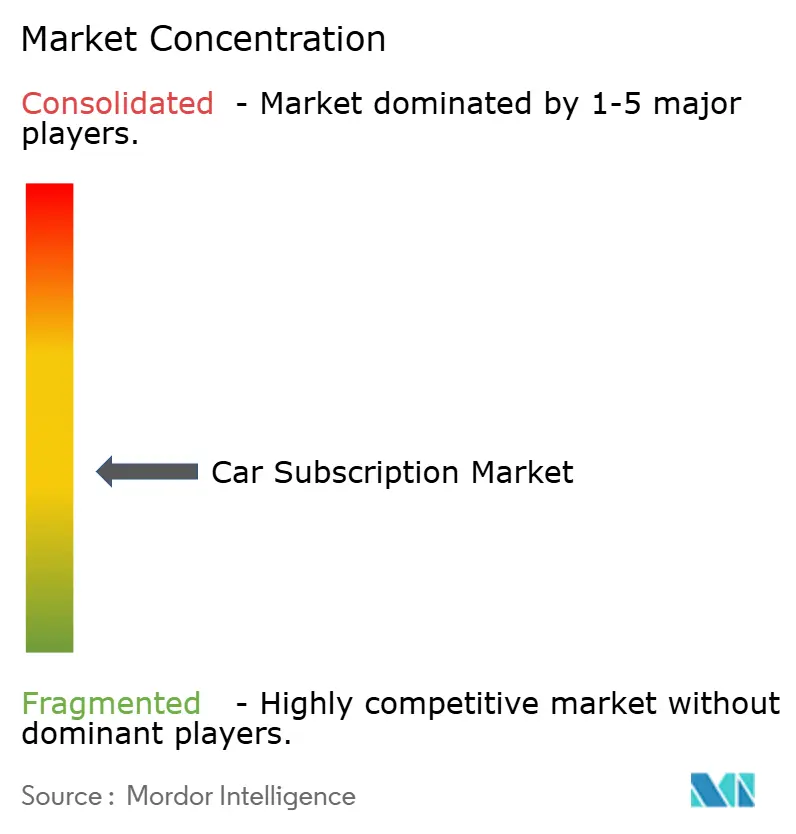
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Car Subscription Market Analysis by 黑料不打烊
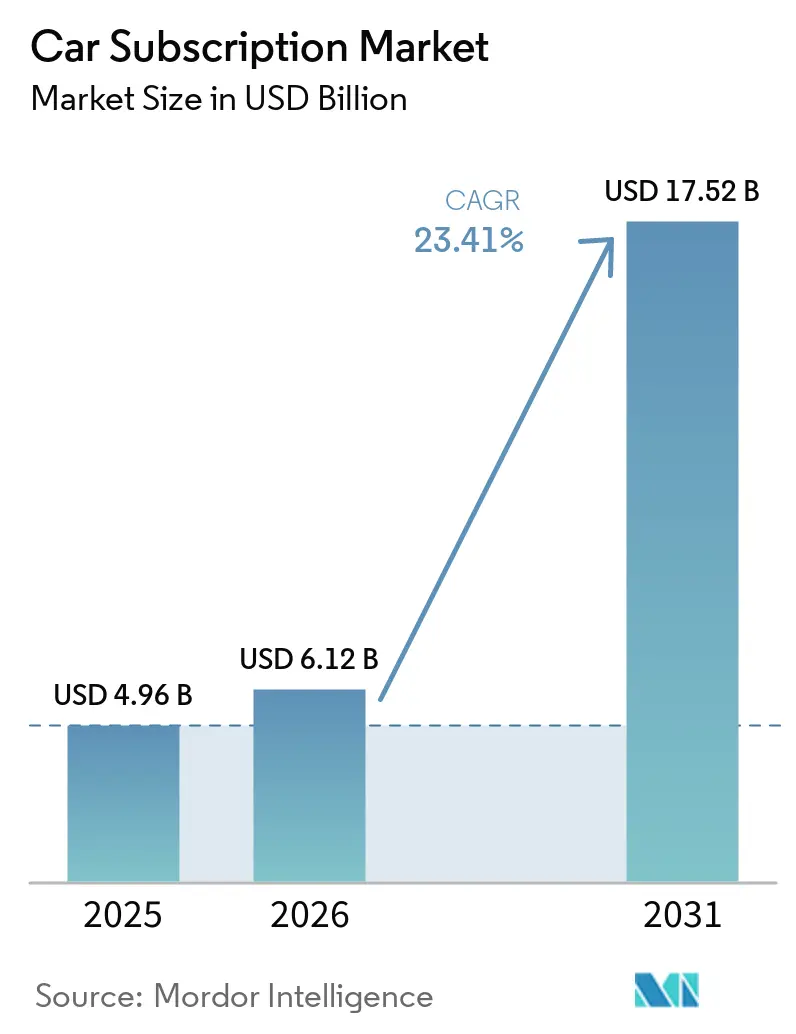
The car subscription market was valued at USD 4.96 billion in 2025 and is estimated to grow from USD 6.12 billion in 2026 to reach USD 17.52 billion by 2031, at a CAGR of 23.41% during the forecast period (2026-2031). The market is gaining traction as consumers face elevated borrowing costs and prefer a single monthly payment over loan installments, insurance, maintenance costs, and depreciation exposure. OEMs and captive finance arms view car subscriptions as a customer retention channel, as the model keeps the vehicle, service relationship, and data connection within the ecosystem for extended periods. Consequently, the car subscription market is evolving beyond a mobility model into a retail offering that appeals to consumers seeking flexibility, businesses requiring operating-cost visibility, and cities where congestion and usage-based policies make fixed-cost vehicle ownership less attractive. However, providers must maintain fleet utilization and resale management because the market remains sensitive to residual-value fluctuations when electrified fleets expand faster than secondary-market pricing stabilizes across the broader used-vehicle market.
Key Report Takeaways
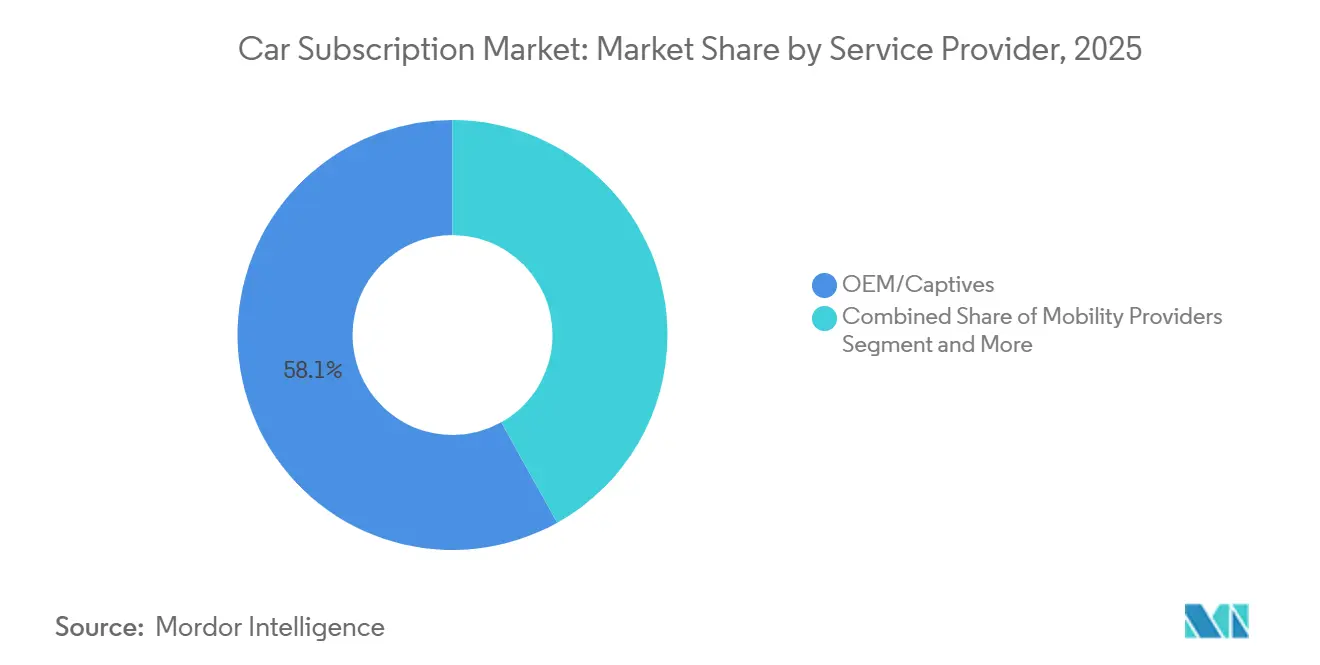
- By service provider, OEM/Captives held 58.10% of revenue in 2025, while mobility providers are set to record the highest projected CAGR at 27.45% through 2031.
- By subscription period, the 6-to-12-month plan accounted for 49.33% of the car subscription market size in 2025, while the 1-to-6-month bracket is forecast to expand at a 30.35% CAGR through 2031.
- By subscription type, single-brand programs held 63.15% of the car subscription market share in 2025, while multi-brand platforms are projected to grow at a 28.23% CAGR through 2031.
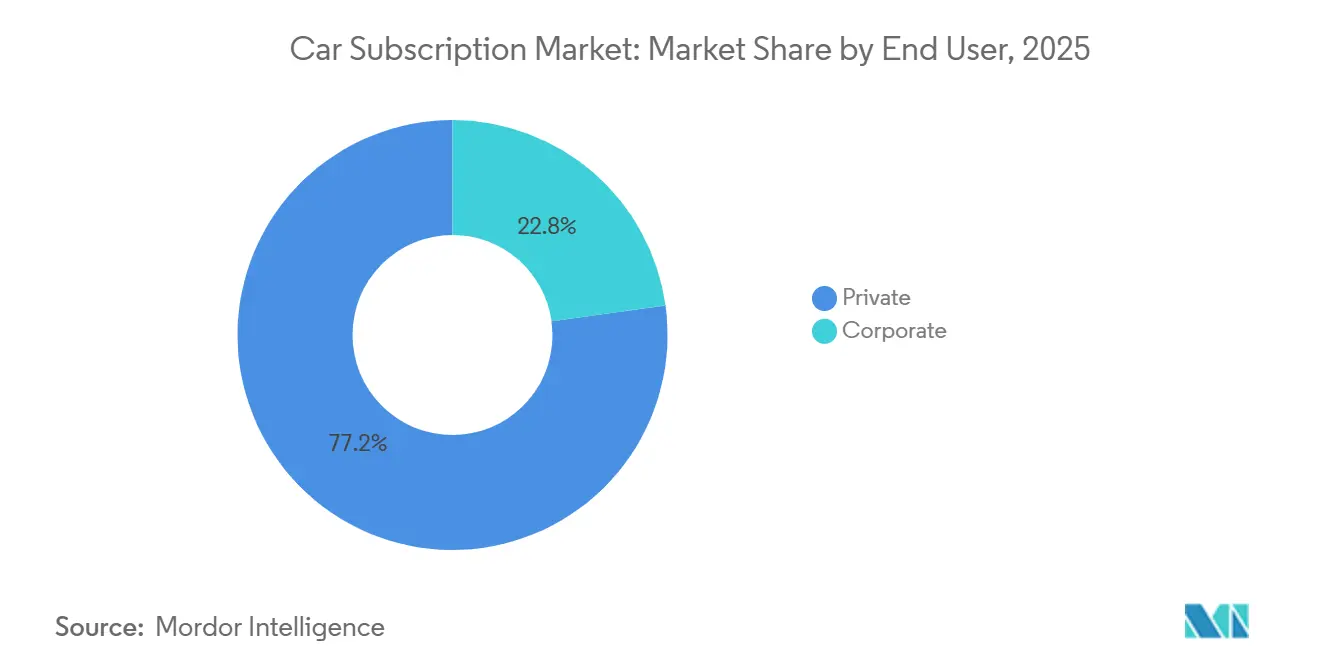
- By end user, private users represented 77.24% of revenue in 2025, while the corporate segment is forecast to grow at a 25.01% CAGR through 2031.
- By propulsion type, internal combustion engine (ICE) vehicles accounted for 84.02% of revenue in 2025, while EV propulsion is projected to expand at a 36.04% CAGR through 2031.
- By geography, North America held 40.16% of revenue in 2025, while Asia-Pacific is forecast to expand at a 31.45% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Car Subscription Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Preference for Hassle-Free Access | +5.5% | Global | Short term (≤ 2 years) |
| OEM and Captive Financing | +4.8% | North America and Europe | Medium term (2-4 years) |
| EV-Specific Depreciation Mitigation | +4.2% | Global | Medium term (2-4 years) |
| SaaS Platform Proliferation | +3.0% | Global | Short term (≤ 2 years) |
| White-Label Dealer Platforms | +1.8% | Asia-Pacific, Middle East and Africa, South America | Medium term (2-4 years) |
| Road-Usage-Pricing Pilots | +1.2% | Europe and North America | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Rising Preference for Flexible, Hassle-Free Vehicle Access
Consumers are showing less interest in long-term vehicle ownership commitments, increasing the relevance of the car subscription market across mature and developing mobility ecosystems. Cost transparency is a key driver, as a bundled monthly fee combines the vehicle, insurance, maintenance, and taxes into a single payment. This structure reduces uncertainty around financing, resale risk, and repair costs. Car subscriptions lower barriers for consumers seeking newer vehicles or electric vehicles (EVs) without a full purchase commitment, expanding the addressable customer base. Rapid digital onboarding shortens retail timelines, making subscriptions resemble digital service purchases and positioning them as a consumption model.
OEM and Captive Financing Push to Retain Lifetime Customer Value
Subscription models reshape the handoff between OEMs and dealers by enabling manufacturers to maintain relationships with customers after vehicle delivery. In the car subscription market, recurring monthly billing generates data on usage, retention, upgrades, and service behavior, helping refine pricing and targeting. Toyota's KINTO reached first-time profitability in Sweden in 2025 while expanding its customer and registered-user base. KINTO Italia recorded growth in long-term registrations in 2025, with electrified vehicles comprising the majority. These results show why captives view subscriptions as a retention layer supporting sales, fleet management, remarketing, and electrification. Operators integrating refurbishment, resale discipline, and residual-value management can sustain an advantage.
EV-Specific Depreciation Mitigation via Subscription Models
The car subscription market is gaining traction among EV buyers seeking electrified driving without assuming the full resale uncertainty of battery-electric vehicles. Early-year depreciation compared with ICE models makes flexible access attractive as technology evolves. Subscription models pool residual value exposure across fleets rather than placing the downside on buyers. This structure aligns with behavior: a majority of new EV purchases in the United States in Q4 2024 were financed through leasing or lease-like instruments. Providers can rotate EVs across subscriber cohorts, extend service cycles, and time vehicle exits. As charging infrastructure improves and OEMs supply inventory, subscriptions remain a bridge to EV adoption.
SaaS Platform Proliferation Lowering Entry Barriers
The car subscription market no longer requires every operator to build a full software stack from scratch, widening participation. Modular platforms support telematics integration, identity verification, pricing, billing, documentation, and fleet workflows. Loopit states it manages more than 50,000 vehicles globally across OEMs, dealerships, and independent operators through a single software environment, demonstrating operating infrastructure maturity [1]“Platform Overview,” Loopit, loopit.co . This reduces launch barriers for white-label dealer networks and mid-sized operators entering the market without proprietary technology costs. As back-office processes become accessible, competition shifts toward fleet mix, customer experience, pricing discipline, and local geographic density, expanding consumer awareness of the subscription model.
Restraints Impact Analysis of Car Subscription Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Economics and Residual-Value Risk | -3.5% | Global | Short term (≤ 2 years) |
| Consumer Awareness and Trust | -2.1% | Emerging Asia-Pacific, South America, Middle East and Africa | Short term (≤ 2 years) |
| Residual-Value Insurance | -1.4% | Emerging Asia-Pacific, South America, Middle East and Africa | Medium term (2-4 years) |
| OEM Channel Conflict | -1.2% | North America and Europe | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Thin Unit-Economics and Residual-Value Risk
The car subscription market faces a core operating challenge: revenue must cover fleet acquisition, insurance, maintenance, logistics, refurbishment, and depreciation. This cost structure leaves little room for error when utilization declines, particularly for newer programs without stable scale. EV-heavy fleets face further pressure as resale assumptions can shift rapidly with changes in battery technology, incentives, and used-vehicle demand. Providers deploy vehicles across subscription, rental, and sales channels to sustain asset earnings when subscriber demand softens. However, this strategy requires pricing, rapid turnaround, and disciplined remarketing capabilities that many smaller entrants lack. Until residual-value insurance and secondary-market liquidity improve, the market will expand cautiously rather than through unrestricted fleet growth.
Low Consumer Awareness and Trust in New Models
Consumer awareness remains uneven, slowing the car subscription market, where consumers poorly understand the model. In many emerging markets, consumers do not clearly differentiate subscriptions from rentals, leasing, or installment financing, complicating evaluation. Opaque pricing and unclear damage liability, cancellation policies, and vehicle return conditions also undermine trust. Subscriptions require consumers to adopt a new contractual model rather than familiar ownership. Limited credit infrastructure in parts of South America, Southeast Asia, and Sub-Saharan Africa creates another barrier, as onboarding approval rates remain low. Providers need clear education, simple contracts, and strong dealer or brand credibility to deepen adoption.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Car Subscription Market Segment Analysis
By Service Provider:
OEM Scale Still Leads While Platform Models Gain GroundOEM/captive operators accounted for 58.10% of revenue in 2025, securing the leading position in the car subscription market through direct access to vehicle inventory, financing, insurance partnerships, and dealer support. This advantage shortens delivery timelines and reduces the sourcing challenges faced by independent providers. Brand familiarity also increases consumer confidence in bundled monthly pricing and recurring service commitments. Consequently, captive operators can meet mobility demand while retaining customers who might otherwise leave the brand between vehicle purchase cycles.
Mobility providers will emerge as the fastest-growing group, with a projected CAGR of 27.45% through 2031. They aggregate supply, deploy app-based experiences, and scale with lower balance-sheet intensity than captive models. Technology companies integrate subscription tools, enabling white-label launches for dealers. Software influences pricing, inventory visibility, and onboarding, shifting information advantages from OEM captives to third-party systems. This creates a market where software, experience, and fleet access matter nearly as much as vehicle ownership.


By Subscription Period:
Mid-Length Plans Provide Stability While Shorter Terms Lift GrowthThe 6-to-12-month tier accounted for 49.33% of the car subscription market size in 2025, reflecting preference for a tenure that balances flexibility and predictable fleet utilization. It supports relocation, project-based work, seasonal family needs, and EV trials without long-term ownership risks. For operators, it spreads onboarding, delivery, and servicing costs over enough time to support margins. It bridges short-term rentals and leasing commitments while generating data on driver behavior, vehicle wear, and renewals, improving pricing discipline.
The 1-to-6-month category is forecast to grow at a 30.35% CAGR through 2031, the fastest-growing tenure segment, as customers prioritize immediate access and minimal commitment. SIXT positions SIXT+ to convert renters into recurring users, reporting month-over-month retention [2]“Annual Results 2025,” SIXT SE, about.sixt.com. Short plans suit tourism, gig work, temporary assignments, and rapid access without lock-in. More-than-12-month plans improve utilization visibility and reduce churn costs. Long-term corporate contracts facilitate emissions tracking and allocate vehicle data to business units. Medium-term plans support revenue, while short-term plans drive growth.
By Subscription Type:
Single-Brand Programs Dominate While Multi-Brand Choice ExpandsSingle-brand programs held 63.15% of the car subscription market in 2025, reflecting OEM-led fleet strength and dealer-network convenience. Providers standardize procurement, servicing, residual planning, and customer communication across narrower model ranges. It reinforces loyalty: users receive vehicles, support, and often financial services from the same manufacturer. Toyota’s KINTO expansion across countries illustrates this approach, providing Toyota and Lexus vehicles rather than a cross-brand inventory pool. For first-time users, it appears simpler than unfamiliar mixed-fleet offerings.
Multi-brand platforms are projected to grow at a 28.23% CAGR through 2031 by addressing limited vehicle choice as needs change. They offer compact weekday vehicles and family or leisure options, improving retention. Operators must secure reliable supply agreements and manage depreciation, servicing, and remarketing requirements. Challenges are greater outside North America and Northern Europe, where dealer and OEM channels may limit access. Mixed-brand models will expand as software, sourcing partnerships, and fleet financing mature.
By End User:
Private Users Hold the Base While Corporate Demand Builds FasterPrivate users accounted for 77.24% of revenue in 2025, making them the largest demand base in the car subscription market. This reflects demand from urban professionals, younger consumers, and EV-curious drivers seeking all-inclusive monthly mobility without significant capital commitments. Demand is strongest in markets with digital onboarding and service-based spending. EV financing reinforces the trend: most EV transactions in the United States in Q4 2024 used lease or lease-like structures that align with subscriptions. The market serves users prioritizing flexibility, predictable budgeting, and exit options over ownership.
The corporate segment is projected to grow at a 25.01% CAGR through 2031, outpacing private users despite its smaller base. Businesses use subscriptions to replace capital purchases with operating expenses, improving flexibility and aligning budgets with reporting cycles. The model supports fleet electrification while limiting technology and residual-value exposure. As ESG reporting expands, subscriptions may attract SMEs and enterprise fleets seeking lower commitment and emissions tracking.
By Propulsion Type:
ICE Maintains Scale While EVs Drive the Fastest ShiftInternal combustion engine vehicles accounted for 84.02% of car subscription market revenue in 2025, highlighting reliance on conventional powertrains. Their installed base, broad refueling networks, and established maintenance and insurance systems support scale. ICE fleets offer operators entering Asia-Pacific, South America, and the Middle East and Africa simpler launch paths, as public charging remains uneven, consumer EV familiarity is developing, and pricing, servicing, and residual-value planning are less volatile.
EV subscriptions are projected to grow at a 36.04% CAGR through 2031, the market’s fastest segment. OEM electrification programs, consumer willingness to test EVs without purchase commitments, and policies supporting lower-emission fleets drive growth. Lease-like financing makes subscriptions familiar for managing EV uncertainty. Providers can spread EV risk across fleets and rotate vehicles through customer cycles before disposal, unlike direct retail sales. Subscriptions help consumers test electrification, and operators manage battery values over time, creating a mixed propulsion structure: ICE supports revenue stability, while EVs drive future expansion.
Geography Analysis
North America Car Subscription Market
North America accounted for 40.16% of the car subscription market size in 2025, making it the largest regional contributor. Early OEM launches, mature credit systems, and urban consumers comfortable with access-based spending support demand. The United States remains the largest country market, supported by provider scale, financing familiarity, and digital onboarding. Canada is gaining momentum as EV-supportive policies and consumer awareness strengthen flexible access models. Compared with other regions, North America remains more concentrated among OEM-captive and platform-led offerings than independent local specialists.
Europe Car Subscription Market
Europe stands out for program density and regulatory alignment, creating a market structure distinct from North America. Established OEM financing systems, stricter emissions requirements, and urban mobility frameworks favor products positioned between leasing and rental. Germany remains a key operating base, while the Netherlands, Italy, Spain, Norway, and the United Kingdom shape demand through EV adoption, SME mobility needs, and digitally managed fleet offerings. SIXT identifies subscriptions as a recurring-revenue contributor within its mobility portfolio, reflecting their role in wider service platforms.
APAC, South America and MEA Car Subscription Market
Asia-Pacific is forecast to expand at a 31.45% CAGR through 2031, the fastest rate. Toyota’s KINTO and India’s OEM-led launches support adoption. South America and the Middle East and Africa remain earlier-stage, while differing maturity keeps provider strategies localized.

Competitive Landscape
The car subscription market is moderately fragmented, with competition divided among OEM-captive operators, technology-enabled platforms, and independent mobility providers rather than dominated by one cross-regional player. Fleet ownership, software, and customer acquisition vary by country. OEM-linked operators integrate vehicles, financing, infrastructure, and brand trust, while others offer multi-brand access and simpler digital journeys. Local operating-model fit matters more than global brand visibility.
SIXT uses SIXT+ as a recurring-revenue offering in its mobility ecosystem, showing how subscriptions increase value alongside rental and car-sharing. Toyota’s KINTO reached profitability in Sweden in 2025 while expanding users and fleet scale, and strengthened its Italian position through several new registrations and an electrified mix. DriveItAway and Free2move expanded the United States dealer-led rollout, enabling national reach without requiring every dealer to manage product design and software development [3]“Company News,” DriveItAway, driveitaway.com.
Opportunities include corporate fleet subscriptions in Asia-Pacific, multi-brand EV offers in Europe, and dealer-enabled white-label expansion in South America and the Middle East and Africa, where demand is rising despite immature infrastructure, insurance, and fleet finance. Asset exposure remains the risk: volatile fleet resale values can compress margins. Success requires disciplined fleet cycling, pricing, and multiple vehicle revenue streams. Battery-separated EV economics, AI-supported pricing, and dealer software will shape an investable, open, unconcentrated market.
Car Subscription Industry Leaders
Hyundai Motor Company
Hertz Global Holdings, Inc.
Volvo Cars
Toyota Motor Corporation (Kinto)
Free2Move
- *Disclaimer: Major Players sorted in no particular order
Car Subscription Market Companies Covered in this Report
- Daimler AG (Mercedes-Benz Mobility)
- Toyota Motor Corporation (Kinto)
- Volvo Cars
- Hyundai Motor Company
- Free2Move
- Porsche AG
- Lynk and Co.
- Autonomy Inc.
- Sixt SE
- Hertz Global Holdings, Inc.
- FlexClub
- Facedrive Inc. (Steer)

Recent Industry Developments in Car Subscription Market
- July 2026: Car subscription company Carbar merged with Middle Eastern competitor Carasti to create a combined company before the fundraising round. Both companies offer Netflix-style monthly car subscriptions that provide greater flexibility than traditional novated leases.
- June 2026: Karmo, which describes itself as “Australia’s largest car subscription platform,” received a major investment from Eagers Automotive, which has acquired a 17.5% stake in the business. Karmo describes its service as enabling customers to use a car “without the long-term commitment and financial burden of ownership.
- April 2026: Nissan Motor India Pvt. Ltd. (NMIPL) and Avis India announced a strategic partnership to strengthen corporate mobility and leasing solutions in India through integrated leasing and subscription offerings. The collaboration aimed to address the growing demand for flexible, asset-light mobility models among enterprises while providing convenient and cost-efficient access to Nissan’s vehicle portfolio through a structured, end-to-end ecosystem.
- January 2026: CarSlice announced the launch of India’s first tax-efficient, subscription-based luxury mobility model, introducing a new way for affluent consumers to access premium vehicles without the financial burden of traditional ownership. Designed for high-income professionals, entrepreneurs, and investors, CarSlice replaces outright ownership with a structured subscription and fractional framework that reduces capital lock-in and mitigates depreciation.


Global Car Subscription Market Report Scope
The scope includes segmentation by service provider (OEM/captives, mobility providers, and technology companies), subscription period (1 to 6 months, 6 to 12 months, and more than 12 months), subscription type (single brand (single-brand swap) and multi-brand), end user (private and corporate), and propulsion type (internal-combustion engine (ICE) and electric vehicle (EV). The analysis also covers regional-level segmentation, including North America, South America, Europe, Asia-Pacific, and the Middle East and Africa. Market size and growth forecasts are presented by value in USD.
| OEM/Captives |
| Mobility Providers |
| Technology Companies |
| 1 to 6 Months |
| 6 to 12 Months |
| More than 12 Months |
| Single Brand (Single-Brand Swap) |
| Multi Brand |
| Private |
| Corporate |
| Internal-Combustion Engine (ICE) |
| Electric Vehicle (EV) |
| North America | United States |
| Canada | |
| Rest of North America | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Spain | |
| Italy | |
| Poland | |
| Russia | |
| Rest of Europe | |
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| Australia | |
| Malaysia | |
| Rest of Asia-Pacific | |
| Middle East and Africa | United Arab Emirates |
| Saudi Arabia | |
| South Africa | |
| Rest of Middle East and Africa |
| By Service Provider | OEM/Captives | |
| Mobility Providers | ||
| Technology Companies | ||
| By Subscription Period | 1 to 6 Months | |
| 6 to 12 Months | ||
| More than 12 Months | ||
| By Subscription Type | Single Brand (Single-Brand Swap) | |
| Multi Brand | ||
| By End User | Private | |
| Corporate | ||
| By Propulsion Type | Internal-Combustion Engine (ICE) | |
| Electric Vehicle (EV) | ||
| By Geography | North America | United States |
| Canada | ||
| Rest of North America | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Spain | ||
| Italy | ||
| Poland | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| India | ||
| Japan | ||
| South Korea | ||
| Australia | ||
| Malaysia | ||
| Rest of Asia-Pacific | ||
| Middle East and Africa | United Arab Emirates | |
| Saudi Arabia | ||
| South Africa | ||
| Rest of Middle East and Africa | ||


Key Questions Answered in the Report
What is driving growth in car subscription services?
Growth is being supported by simpler monthly pricing, financing pressure on buyers, and rising demand for flexible vehicle access. The category is projected to grow from USD 6.12 billion in 2026 to USD 17.52 billion by 2031 at a 23.41% CAGR.
Which region leads today and which region is growing fastest?
North America led with 40.16% of revenue in 2025. Asia-Pacific is forecast to grow the fastest, with a 31.45% CAGR through 2031.
Which customer group is expanding fastest?
Private users still dominate current demand with 77.24% of 2025 revenue. Corporate customers are growing faster, with a projected 25.01% CAGR as firms shift fleet spending toward operating expenses.
What subscription duration is most important right now?
The 6-to-12-month plan is the current anchor, with 49.33% of 2025 revenue. It balances user flexibility with better fleet utilization for operators.
Page last updated on:



