
Asia-Pacific Automotive Plastics Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | 9.73 Million tons |
| Market Volume (2026) | 10.22 Million tons |
| Market Volume (2031) | 13.07 Million tons |
| Growth Rate (2026 - 2031) | 5.04 % |
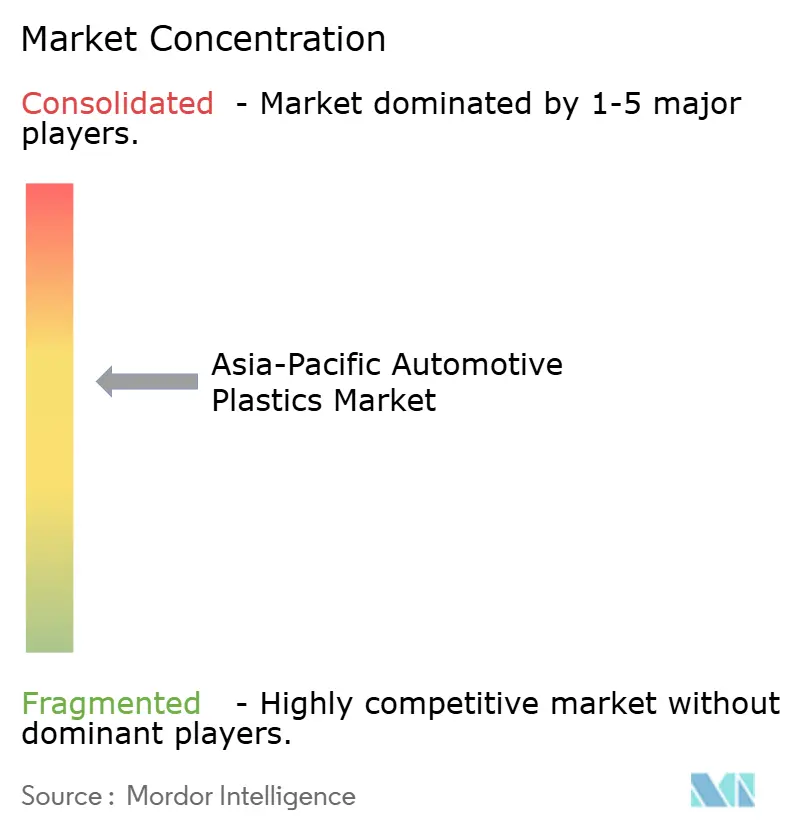
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Asia-Pacific Automotive Plastics Market Analysis by 黑料不打烊
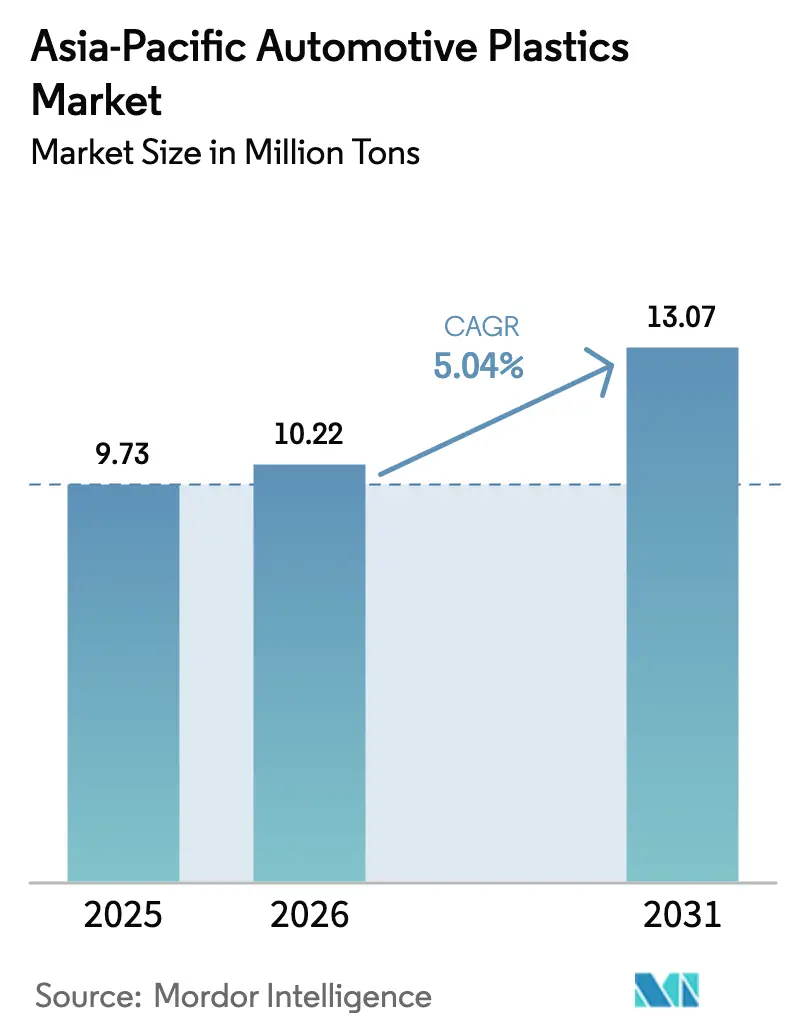
Asia-Pacific Automotive Plastics Market size in 2026 is estimated at 10.22 Million tons, growing from 2025 value of 9.73 Million tons with 2031 projections showing 13.07 Million tons, growing at 5.04% CAGR over 2026-2031. Steady electric-vehicle roll-outs, stringent lightweighting rules, and expanding recycling mandates underpin the momentum. Original equipment makers are embedding recycled or bio-based grades to meet score-card targets, while quick-cycle injection moulding keeps costs in check. Polypropylene maintains leadership because of its versatility and low density, yet rapid growth in polycarbonate and polyamide points to rising demand for high-heat and high-voltage parts. Regional supply chains continue to rebalance after shipping bottlenecks at Panama and Suez canals curtailed feedstock flows, pushing processors to localize resin sourcing. Heightened regulatory scrutiny, particularly on microplastics and verified recycled content, is turning sustainability compliance into a decisive competitive lever across the automotive plastics market.
Key Report Takeaways
- By material, polypropylene led with 41.10% automotive plastics market share in 2025, while polycarbonate recorded the fastest 7.12% CAGR through 2031.
- By vehicle type, conventional vehicles held 82.95% share of the automotive plastics market size in 2025; electric vehicles are expanding at an 8.35% CAGR to 2031.
- By application, interior parts accounted for 46.20% of the automotive plastics market size in 2025 and under-bonnet parts are advancing at a 7.42% CAGR over 2026-2031.
- By geography, China captured 41.40% share in 2025, whereas India is projected to log the highest 6.38% CAGR during the outlook period.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Asia-Pacific Automotive Plastics Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Lightweighting Mandate Compliance | +1.2% | Global, strongest in China and India | Medium term (2-4 years) |
| Growing Polypropylene Penetration in Interiors and Exteriors | +0.8% | APAC core, spill-over to ASEAN | Long term (≥ 4 years) |
| Surge in Electric-Vehicle Production Volumes | +1.5% | China, India, ASEAN early adopters | Short term (≤ 2 years) |
| Cost Reduction via High-throughput Injection Moulding | +0.7% | Manufacturing hubs: China, Thailand, Vietnam | Medium term (2-4 years) |
| OEM Score-card Targets for Bio-based/Recycled Plastics | +0.9% | Japan, South Korea leading, China following | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Lightweighting Mandate Compliance
Regulatory authorities across Asia-Pacific tie fleet-average emissions to weight reduction goals. Automakers respond by substituting metals with advanced polypropylene blends that deliver complex geometries at lower cost. Borealis Fibremod long-glass-fiber polypropylene helped reduce the weight of Volkswagen’s Multivan by 200 kg and met stiffness targets. Gigacasting adoption, first popularised by Tesla, is reshaping body-in-white strategies and puts pressure on plastics suppliers to justify structural roles. To keep pace, compounders introduce chemical foaming agents such as Avient Hydrocerol that cut door-panel weight by 20% while lowering carbon dioxide emissions[1]Polymer Additives World, “Avient Hydrocerol Optimises Door Panel Weight,” polymeradditives.com . In China, where battery-electric vehicles are forecast to command 52.9% of total light-vehicle sales by 2036, lightweight plastic modules that also manage heat are becoming indispensable.
Growing Polypropylene Penetration in Interiors and Exteriors
Polypropylene’s noise-dampening and processing advantages are driving adoption in high-performance components. R?chling Automotive intake manifolds trimmed cabin noise by 10–15 dB compared with polyamide alternatives and saved 15% on material cost. Research teams in Japan blend cellulose nanofibres into polypropylene, boosting impact strength while preserving full recyclability, a feature attractive under extended-producer-responsibility laws. Compounds with 30% post-consumer resin from Sirmax now appear in door panels, cutting lifecycle carbon footprints by 21% and meeting odor thresholds. Exterior cladding benefits from ultraviolet-stable grades such as LyondellBasell CirculenRecover that retain dimensional integrity while offering 20% recycled content. Process optimisation studies confirm that higher packing pressure mitigates shrinkage, reinforcing polypropylene’s appeal for visible Class-A surfaces.
Surge in Electric-Vehicle Production Volumes
Government incentives across ASEAN pushed electric-vehicle penetration from 9% in 2023 to 13% in 2024. EV platforms call for flame-retardant, high-temperature plastics such as BASF Ultramid T6000 polyphthalamide that survives 1 000 thermal-shock cycles between -40 °C and 150 °C. Injection-moulded thermoplastic battery enclosures developed by Engel and SABIC consolidate multiple metal parts into a monolithic design, lowering cost and tooling complexity. Celanese Zytel HTN and Fortron PPS extend operating windows to 180 °C, meeting coolant-system safety margins. National targets, such as Thailand’s 30-at-30 policy and Indonesia’s 600 000-unit ambition by 2030, reinforce near-term demand for specialised resins that satisfy both thermal and dielectric criteria.
Cost Reduction via High-throughput Injection Moulding
Processors across the automotive plastics market deploy MuCell micro-cellular foaming to trim resin consumption without compromising strength. Ensinger reports cycle-time cuts and reduced warpage since adopting the nitrogen-blown technique in 2023. Integrated energy-management systems that combine mold cooling, heat pumps, and material pre-heating yield marked efficiency gains and lower greenhouse-gas intensity. Machinery builders such as FCS Machinery enjoy order backlogs to 2026 thanks to soaring new-energy-vehicle demand. Automation platforms tie real-time sensor feedback to AI-driven optimisation, illustrated by Atomic Industries and LS Mtron moulds equipped with 46 I/O ports. Injection-Moulded Structural Electronics technology integrates wiring into plastic skins, slashing component counts and boosting design freedom.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Recycling Infrastructure Gaps and Regulatory Pressure | -0.6% | China, India infrastructure challenges | Medium term (2-4 years) |
| Volatility in Raw-material (Naphtha/Propylene) Pricing | -0.9% | Global, acute in import-dependent markets | Short term (≤ 2 years) |
| Emerging Alloy-Aluminium Substitution in Structural Parts | -0.4% | Premium segments, China EV market | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Recycling Infrastructure Gaps and Regulatory Pressure
Extended-producer-responsibility rules proliferate, yet collection and sorting capacity lag vehicle scrappage rates in several markets. India’s End-of-Life Vehicles Rules 2025 introduce comprehensive online tracking but omit detailed plastic quotas, limiting immediate circularity gains. Vietnam mandates a 22% recycling rate for rigid PET packaging, signaling future obligations for automotive plastic modules that raise compliance costs. Japan’s mature stewardship programmes still focus on packaging, so automotive parts fall outside current take-back streams. Technical studies show that bumper regrind loses impact resistance if primer removal is incomplete, underscoring the need for chemical recycling to complement mechanical routes. Supply-chain collaborations such as Yanfeng-Trinseo aim to bridge the gap by scaling dissolution and advanced-sorting technologies that meet 2030 targets.
Volatility in Raw-material (Naphtha / Propylene) Pricing
Shipping snarls at Panama and Suez canals cut Chinese access to North-American propane, pushing polypropylene margins down to USD 55 per ton from USD 200 in early 2024. China’s polypropylene capacity will exceed local demand by 68% in 2025, forcing producers into export or run-rate cuts. Geopolitical actions such as Beijing’s 74.9% provisional duty on US polyacetal exports render American product uncompetitive in its biggest offshore market. Red Sea disruptions and Panama-Canal droughts prolong transit times, eroding just-in-time resin inventories that tier-one suppliers rely on. Vertical-integration moves, like SCG Chemicals’ USD 700 million ethane upgrade in Vietnam, help dampen feedstock shocks and lower carbon intensity.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Material: Polypropylene Adapts to High-Performance Demands
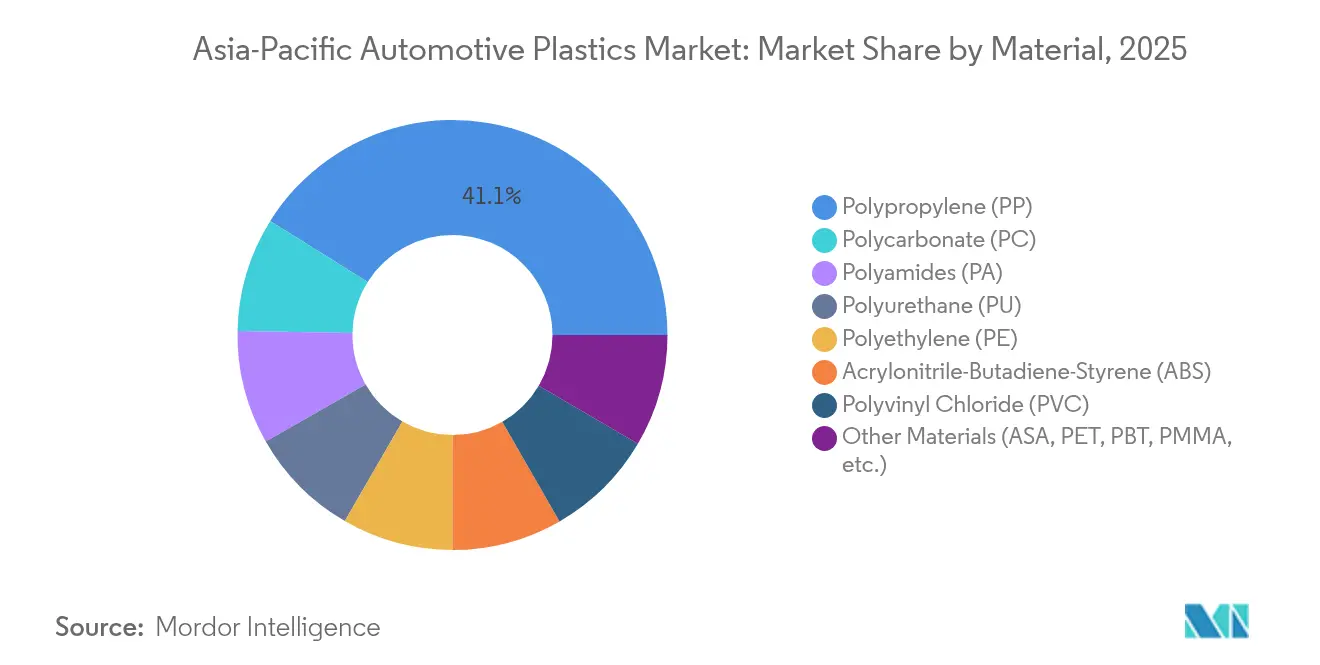
Polypropylene commands the largest slice of the automotive plastics market at 41.10% volume share. ExxonMobil Achieve Advanced grades lift impact strength above legacy copolymers, allowing thinner structures that lower mass and support a USD 55 per-ton margin squeeze. Polycarbonate delivers the fastest 7.12% CAGR as processors embrace Covestro mechanically recycled content for glazing and lighting housings. Thermoplastic polyurethane supply is set to tighten once BASF’s Zhanjiang mega-line ramps up, responding to electrification needs that require flexible cable jacketing in 800 V architectures.
The automotive plastics market size for engineering resins is climbing with acrylonitrile-butadiene-styrene shifting toward biomass styrene monomer and polyamide 66 seeing 40 000-ton capacity increments in Shanghai. Polyethylene still supports packaging and lightweight exterior trims, whereas PVC faces image pressure under circularity pledges. Specialty families like ASA, PBT, and PMMA supply niche roles such as weather-resistant grilles and scooter battery packs. As Asia-Pacific refineries convert crude to chemicals, upstream integration provides cost buffers that safeguard polypropylene’s foothold against the surging engineering-resin cohort.


By Vehicle Type: Electric Vehicles Drive Specialised Material Uptake
Conventional vehicles still consume 82.95% of total automotive plastics volume in 2025, but incremental weight-out initiatives elevate plastic content per car. Intake manifolds in polypropylene now reach acoustic benchmarks that once required heavier polyamide configurations, showcasing cost advantages. Engine covers and fluid reservoirs increasingly adopt chemically foamed polypropylene, further lifting lightweighting headroom.
Electric vehicles post an 8.35% CAGR and push the automotive plastics market toward flame-retardant, dielectric, and thermally conductive grades. Engel-SABIC battery enclosures demonstrate that a single moulding replaces multi-piece aluminium boxes, reducing assembly fasteners and improving recyclability. Celanese PPS cool-plate systems allow tighter battery-cell spacing, extending vehicle range within a fixed pack volume. Government roadmaps—Indonesia’s 600 000-unit goal and Malaysia’s plan for 20% EV penetration—support long-run resin demand growth. Injection-moulding machine backlogs until 2026 indicate that Tier-one suppliers continue to lock in capacity dedicated to EV components.
By Application: Interior Parts Retain Volume Lead while Under-bonnet Surges
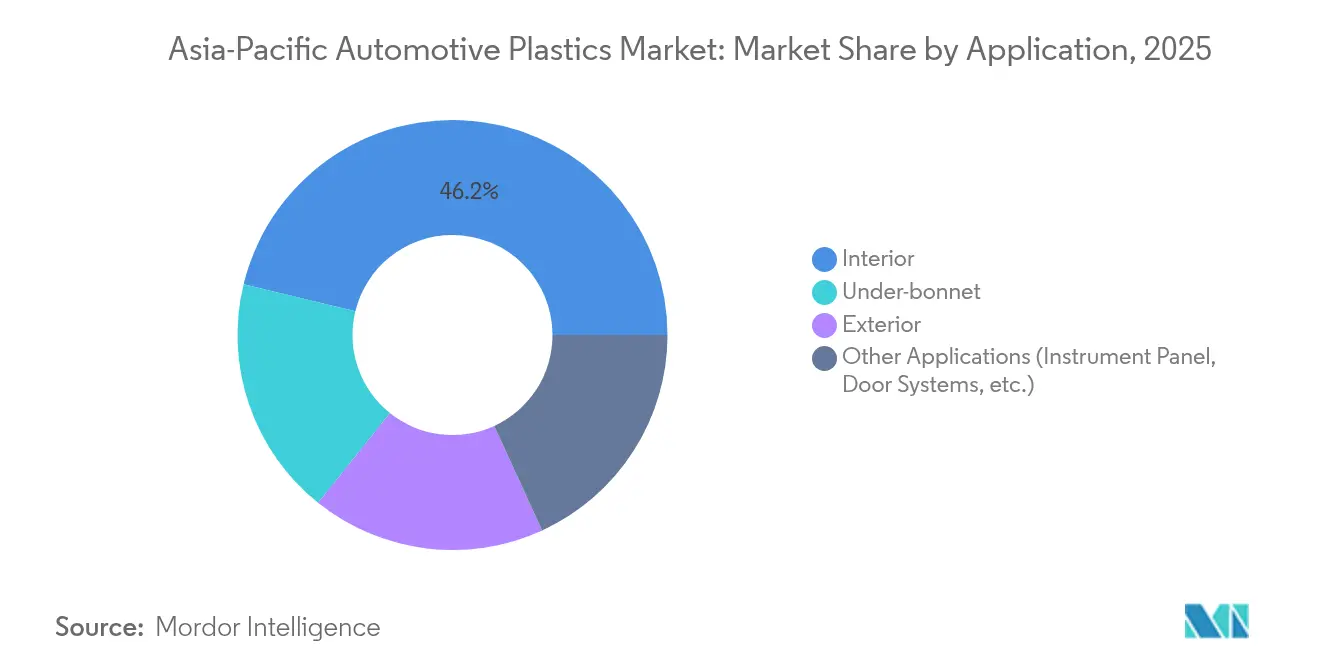
Interior modules absorbed 46.20% of all automotive plastics use in 2025. Door-panel makers that integrate 30% recycled polypropylene lower cradle-to-gate emissions by 21% without violating volatile-organic-compound thresholds. IMSE technology embeds touch controls directly into instrument panels, reducing harness weight and assembly steps. Exterior skins benefit from long-glass-fiber polypropylene tailgates that match metal stiffness and shave kilograms from rear closures.
Under-bonnet demand grows at a 7.42% CAGR, driving automotive plastics market share gains for high-heat families. DSM Arnitel HT lets turbo-ducts form in a single shot, coping with 180 °C continuous exposure while halving cost against multi-material assemblies. Avery Dennison high-heat PA66 stands up to 165 °C excursions and meets tightening thermal-shock profiles in downsized engines. Injection-moulded glass-reinforced PA 6 hybrids introduced by LANXESS improve load-bearing performance in power-unit mounts and front-end carriers. The automotive plastics market size attached to these high-temperature niches is projected to expand in tandem with turbocharging and electrification platforms through 2031.
Geography Analysis
China retained 41.40% automotive plastics market share in 2025, anchored by global light-vehicle output leadership and a massive chemical production base. Margin headwinds emerged when canal disruptions throttled US propane inflows, sending domestic polypropylene spreads to USD 55 per ton. The country’s polypropylene capacity overhang, forecast to climb 68% in 2025, invites export pressure yet also lowers resin costs for local converters. Battery-electric vehicles are likely to command 52.9% of 2036 sales, widening the addressable pool for high-performance plastics that deliver thermal management and flame-retardancy. Geopolitical levies, such as the 74.9% duty on US polyacetal, encourage accelerated in-house specialty-resin expansion.
India shows the fastest 6.38% CAGR, underpinned by USD 87 billion planned petrochemical investments and policies allowing 100% foreign direct investment. Automotive plastics market size gains stem from capacity additions at BASF’s Gujarat and Maharashtra compounds that feed growing domestic demand. The End-of-Life Vehicles Rules 2025 create an online marketplace for scrappage certificates and battery recycling, indirectly boosting reclaimed plastic components. Though India recorded a 7.02 million-ton polymer trade deficit in 2023-24, expansions toward 46 million-ton national nameplate capacity by 2030 aim to narrow the shortfall.
Japan and South Korea operate at the technological frontier but grapple with volume constraints. Japanese vehicle output fell 8.8% in 2024 to 6.01 million units, reducing polyether-polyol consumption. Even so, Toray Advanced Materials Korea boosted PPS resin capacity by 5 000 tons, targeting a global 6% annual demand rise in EV drivetrain parts. South Korea’s draft recycling enforcement mandates authenticated recycled content, spurring investment in digital traceability platforms.
ASEAN markets display mixed volumes yet favourable policy frameworks. Light-vehicle sales slipped 5.4% in 2024 across ASEAN-6, but EV penetration improved to 13%. Thailand’s 30-at-30 strategy earmarks tax incentives to localise battery module production, elevating demand for flame-retardant polypropylene and polyamide enclosures. Vietnam secures upstream resilience through SCG Chemicals’ USD 700 million ethane enhancement, while domestic compounders like Polyplastics supply battery-pack PBT to home-grown e-scooter manufacturer Selex Motors. Indonesia intends to raise EV capacity to 600 000 units by 2030, courting resin producers for joint ventures near nickel and cobalt resources.
Regulatory Landscape
Automotive plastics adoption in Asia-Pacific is shaped by tightening fleet efficiency and materials compliance regimes that increasingly overlap with recyclability, interior air quality, and data disclosure. In China, MIIT-linked GB requirements, including GB 30512-2024 material restrictions and GB 27630 for in-cabin VOCs, push OEMs and tier suppliers toward low-emission interior polymers and traceable formulations, with material declarations commonly handled through CAMDS alongside IMDS in cross-border programs.
Circularity and verified content rules are also becoming a direct procurement gate. Japan uses the Automobile Recycling Law to administer end-of-life obligations and extends recycled-content planning and reporting through the Act on Promoting Resource Circulation for Plastics (2022). South Korea applies recyclability targets under the Act on Resource Circulation and aligns standards work through KATS, with interior-emissions coordination involving MFDS, reinforcing demand for authenticated recycled content and auditable supply chain documentation across resin producers, compounders, and part makers.
Value Chain Analysis
The value chain starts with upstream feedstocks and polymerization (naphtha/propane cracking, and PP/PC/PA/TPU production), moves into compounding and conversion (masterbatching, reinforcement, flame-retardant and low-VOC formulations), and then supplies tier manufacturers producing interior, exterior, and under-bonnet components through high-throughput injection molding. This is followed by OEM assembly and aftermarket replacement parts. Integrated players such as BASF, Covestro, and SABIC are increasingly using local-for-local production and technical service around major China manufacturing clusters to shorten qualification cycles for EV-related thermal, dielectric, and interior-emissions requirements.
Midstream compounding and application engineering have also gained leverage as OEM sustainability scorecards drive carbon footprint declarations and recycled-content verification requests. Localization is expanding in emerging hubs as well, for example through LG Chem starting engineering plastics production at its Sri City facility in India to support automotive and industrial demand. Policy efforts such as Malaysia's incentive refinements to integrate local SMEs into the automotive supply chain further support regionalization of molding, tooling, and module assembly.
Competitive Landscape
The automotive plastics market exhibits moderate consolidation. Global majors BASF, SABIC, and LyondellBasell leverage feedstock integration and broad engineering-resin portfolios. Covestro differentiates on circularity through its Guangdong recycling complex that will boost recycled-content polycarbonate output to 60 000 tons by 2026[2]Covestro Newsroom, “Mechanical-Recycling Polycarbonate Line Starts in Guangdong,” covestro.com . Kingfa, LG Chem, and Asahi Kasei use regional proximity and tailored grades to win business from rapidly expanding Tier-one moulders tied to Chinese and Korean automakers.
Competitive intensity pivots on electrification and sustainability. Yanfeng and Trinseo combine advanced mechanical recycling with dissolution technology to supply dashboards meeting 2030 end-of-life mandates. Covestro’s flame-retardant thermoplastic polyurethane targeting 150 °C cable applications rounds out high-voltage offerings and reinforces safety credentials in the automotive plastics industry.
Mergers and alliances reshape the field. ADNOC and OMV agreed to acquire Nova Chemicals for USD 13.4 billion, integrating the asset into Borouge-4 and creating the world’s largest single-site polyolefin hub aimed at Asia demand pull. AI-enabled optimisation platforms from Atomic Industries grant moulders live feedback, reducing scrap and speeding new-tool validation. Supply chain resilience is now a value proposition as processors hedge against maritime chokepoints by dual-sourcing propane and commissioning regional cracker investments.
Asia-Pacific Automotive Plastics Industry Leaders
BASF SE
Covestro AG
SABIC
LG Chem
LyondellBasell Industries Holdings B.V
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
EV platform specialization and interior electrification create room for higher-temperature, flame-retardant, and functional materials that also meet recyclability and VOC limits. In regional examples, thermoplastic battery enclosures from Engel and SABIC consolidate multi-part metal designs, while in-cabin functional films and substrates support haptics and integrated surfaces. Material suppliers are also building application engineering capability closer to OEM design centers to reduce time-to-qualification.
Capacity localization and new-material programs point to active investment lanes for automotive plastics in Asia-Pacific tied to resin availability, customization, and circularity. In July 2026, SABIC and Rongsheng Petrochemical signed a project development agreement for the Jintang New Materials Project, targeting high-performance resins and biodegradable plastics. In the same month, Covestro outlined plans for a new 660-kiloton per year MDI train at its Integrated Site Shanghai, supporting polyurethane value chains used in seating, interiors, and NVH components. India-focused compounding and engineering plastics supply is being localized too, with LG Chem starting production at its Sri City engineering plastics facility in February 2026, and Malaysia refining its New Customised Incentive Mechanism with local-content utilization targets rising up to 40%, which expands the base for locally compounded and molded automotive polymer parts.
Recent Industry Developments
- June 2026: BASF - Extended partnership with Wacoal into automotive armrest concepts using Melooop technology and Elastollan TPU. The collaboration broadens BASFs interior material footprint and strengthens supply chain resilience for high performance elastomer components in seating applications. It signals BASFs ongoing push to embed advanced TPU solutions in premium interior parts.
- May 2026: BASF - Partnered with Hyundai Design China to develop inflatable Air Hug seat modules using Elastollan TPU for the EARTH Concept vehicle, unveiled at Auto China 2026. The initiative accelerates lightweight, comfort oriented seating and expands elastomer usage in the Chinese market. It reinforces BASFs role in providing engineering resins for next generation mobility concepts.
- May 2026: Covestro - Opened a new Thermoplastic Polyurethanes TPU Application Development Center in Guangzhou, China, completing a regional network that includes the Zhuhai production site and Changhua R&D center. The facility enhances regional TPU innovation capabilities and supports automotive plastics supply chains in APAC. It strengthens Covestros position in high performance materials for the next wave of automotive lightweighting and durability needs.


Research Methodology Framework and Report Scope
Market Definition and Coverage
This market covers the demand for plastic materials used in making automotive components across Asia Pacific, measured as the amount of material consumed by vehicle manufacturing and related part production.
Scope exclusions: We exclude plastics used mainly for non-automotive uses, and we also exclude adhesives, coatings, and rubber materials even if they sit near plastic parts in a bill of materials.
Segmentation Overview
- By Material
- Polypropylene (PP)
- Polyurethane (PU)
- Polyvinyl Chloride (PVC)
- Polyethylene (PE)
- Acrylonitrile-Butadiene-Styrene (ABS)
- Polyamides (PA)
- Polycarbonate (PC)
- Other Materials (ASA, PET, PBT, PMMA, etc.)
- By Vehicle Type
- Conventional/Traditional Vehicles
- Electric Vehicles
- By Application
- Exterior
- Interior
- Under-bonnet
- Other Applications (Instrument Panel, Door Systems, etc.)
- By Geography
- China
- India
- Japan
- South Korea
- ASEAN
- Rest of Asia-Pacific
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to build the base structure of the model and anchor it to real-world signals such as vehicle output and polymer supply. Public sources were checked for country-level vehicle production, registration, and trade direction, and then converted into demand markers for plastics used in interior, exterior, and under-bonnet parts.
We typically refer to sources such as OICA production tables, national transport and customs statistics, UN Comtrade trade flows for key polymer resins, and publications from polymer and automotive associations in the region. Other helpful inputs came from company annual reports, investor presentations, and reputable press coverage that clarified capacity additions, resin price movements, and recycling mandates. Where needed, paid subscriptions were used for company financials and intelligence, shipment-level import and export checks, and patent databases to understand where material substitution is actively happening. These desk sources are illustrative only, and many other public and paid references were also used for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work focused on validating the plastics-per-vehicle assumptions and the split of demand across key applications and vehicle categories, since these points are not consistently reported in public data. We spoke with resin suppliers, compounders and processors, and downstream automotive part stakeholders across major manufacturing hubs, then reconciled feedback by geography so that China, India, Japan, South Korea, and ASEAN each had their own set of demand signals applied.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 29% | CXOs: 15% |
| Mid tier: 54% | Functional/Unit leaders: 41% |
| Smaller Players: 17% | Managers: 44% |
Market-Sizing & Forecasting
Sizing starts from a top-down build where vehicle production and platform mix are used to reconstruct the addressable plastics demand pool by country, and then adjusted for application intensity in areas like interior trim, exterior parts, and under-bonnet components. To keep totals realistic, we corroborate outputs with selective bottom-up checks, such as sampled resin and compound shipment patterns, processor utilization commentary, and volume-to-value sanity checks using observed price ranges.
Inputs that most influenced the model included vehicle production by type (passenger and commercial), the electric versus conventional build mix, and typical plastics intensity per vehicle for high-growth parts like battery-related housings and lightweight exterior modules. Resin availability and substitution trends by polymer family were also considered, especially where polypropylene and polyurethane dominate high-volume use, while higher performance grades rise with thermal and electrical needs. For forecasting, scenario analysis was applied around production outlook and plastics intensity shifts, then refined using expert consensus on near-term auto output and the pace of material substitution. Where direct volume visibility was limited for smaller countries, gaps were handled by using proxy indicators like vehicle assembly capacity, import reliance for key resins, and validated application shares from nearby markets.
Data Validation & Update Cycle
Validation was handled through cross-checking model outputs against independent signals, including regional vehicle output trends, resin trade direction, and consistency with known capacity and utilization commentary. Outliers were flagged early, and assumptions were revisited when a country result moved outside the expected range for plastics-per-vehicle or application shares.
Before sign-off, the model is reviewed in steps by another analyst who checks arithmetic logic, unit consistency, and year-on-year movement across the forecast horizon. If a large variance is found, interview follow-ups are triggered so the assumption is confirmed or replaced with a better supported range. Reports are refreshed annually, with interim updates considered when material events occur such as major regulation changes, sudden production shocks, or large capacity additions. Before delivery, a final pass is completed to ensure the latest public signals are reflected in the published view.
黑料不打烊's Asia Pacific Automotive Plastics Market Sizing Compared With Other Published Estimates
Published market sizes for Asia-Pacific automotive plastics often do not match because the scope and the unit of measurement are not aligned, and because pricing and vehicle-mix assumptions are handled differently. Some sources describe the market in revenue terms, while others focus on material consumed, which naturally changes the headline number even when the end-use story is similar.
The biggest gap driver here is whether the model is built in tons based on plastics intensity and production, or converted into USD using resin and compound price assumptions that can swing by country and year. Differences also come from what gets counted as automotive plastics, since some estimates blend in wider polymer value chains or treat recycled content premiums in a simplified way. In our case, the core figure is expressed in volume for 2026, which reduces currency and price-cycle distortion and keeps the sizing tied to vehicle builds and application usage, a deliberate choice applied by 黑料不打烊.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 10.22 M (2026) | |
| Regional Consultancy A | USD 7.49 B (2024) | Uses revenue-based sizing for 2024, which depends heavily on resin price selection, currency timing, and whether compounding and conversion margins are included in the value captured. |
| Trade Journal B | USD 10.64 B (2024) | Applies a regional revenue share to a global plastics total, which can overstate Asia Pacific when local vehicle mix, plastics-per-vehicle, and country-level price differences are not rebuilt from production and application demand. |
The table shows that the spread is mostly explained by unit choice and what is counted in the value build-up, rather than disagreement on underlying demand direction. When the model is anchored to vehicle output and application intensity first, and only then cross-checked with price ranges, the results stay easier to trace and repeat during updates.


Key Questions Answered in the Report
What is the Asia-Pacific automotive plastics market size today and how fast is it growing?
The market reached 10.22 million tons in 2026 and is projected to climb to 13.07 million tons by 2031, reflecting a 5.04% CAGR.
Which resin commands the largest share of automotive plastics in the region?
Polypropylene leads with 41.10% share because its low density, easy processing, and cost advantages suit both interior and exterior vehicle parts.
How is electric-vehicle adoption influencing material demand?
Accelerating EV production—up from 9% to 13% of ASEAN-6 sales in 2024—drives uptake of flame-retardant and high-temperature plastics for battery enclosures, inverters, and coolant systems.
What regulations most affect automotive plastics usage?
Lightweighting and circular-economy rules such as India’s End-of-Life Vehicles 2025 framework and South Korea’s draft recycled-content verification mandate are pushing OEMs toward recyclable or bio-based grades.
Why are raw-material price swings a concern for converters?
Canal disruptions and oversupply have pushed China’s polypropylene margins down to USD 55 per ton, forcing processors to hedge feedstock sourcing and invest in vertical integration.
Page last updated on:


 Your data is secure and never sold or shared.


