
Advanced Distribution Management System Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 4.31 Billion |
| Market Size (2031) | USD 10.53 Billion |
| Growth Rate (2026 - 2031) | 19.60 % |
| Fastest Growing Market | Asia Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Advanced Distribution Management System Market Analysis by 黑料不打烊
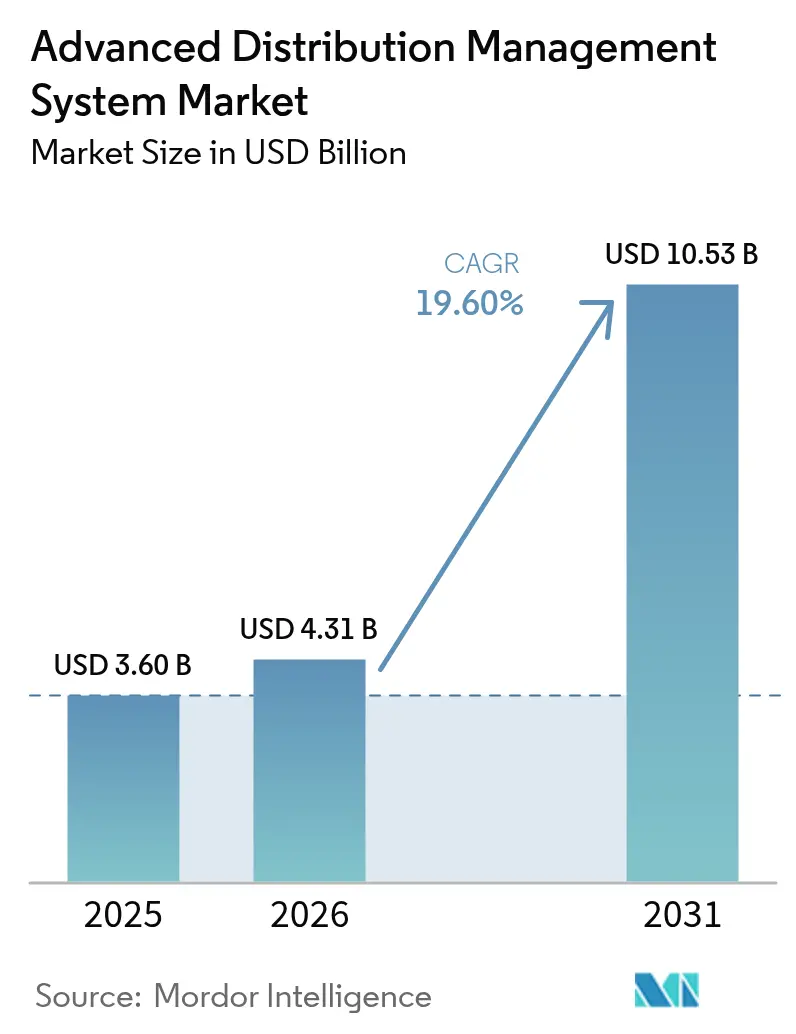
The Advanced Distribution Management System market size in 2026 is estimated at USD 4.31 billion, growing from 2025 value of USD 3.60 billion with 2031 projections showing USD 10.53 billion, growing at 19.60% CAGR over 2026-2031. Grid operators are channeling capital into platforms that fuse outage management, distribution automation, and distributed energy resource orchestration in a single control environment. North America remains the revenue anchor due to FERC Order 2222 compliance programs, yet Asia-Pacific exhibits the steepest growth curve as China and India accelerate smart-grid build-outs and utility digitalization. Cloud-native software, artificial intelligence modules, and edge analytics reinforce the business case, while copper shortages, semiconductor lead-time spikes, and a shrinking utility workforce threaten roll-out velocity. Competition is moderate; industrial automation majors still dominate but face pressure from cloud specialists that promise quicker time-to-value.
Key Report Takeaways
- By offering, software held 80.30% of the Advanced Distribution Management System market share in 2025; the services segment is projected to expand at a 21.40% CAGR through 2031.
- By system type, distribution management systems led with a 35.20% revenue share in 2025, while energy management systems are on track for a 21.05% CAGR to 2031.
- By end-user vertical, the energy and utilities segment accounted for 41.25% of the Advanced Distribution Management System market size in 2025; IT and telecom is the fastest riser with a 22.60% CAGR to 2031.
- By deployment mode, on-premise installations represented 46.50% of the Advanced Distribution Management System market size in 2025 as cloud deployments race ahead at a 21.35% CAGR.
- By geography, North America controlled 39.30% of the Advanced Distribution Management System market in 2025; Asia-Pacific is projected to expand at a 21.70% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Global Advanced Distribution Management System Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rapid adoption of smart-grid digitalisation | +7.2% | Global: strongest momentum in North America, Europe, and the Asia Pacific | Medium term (2–4 years) |
| Growing integration of distributed energy resources (DER) | +6.3% | Global, led by Europe and North America | Medium term (2–4 years) |
| Rising energy demand and outage-reduction priorities | +5.4% | Global; critical in emerging markets across Asia, Africa, and Latin America | Short term (≤ 2 years) |
| EV-charging load balancing requirements | +4.5% | Global; highest relevance in urban centers and EV-dense regions | Medium term (2–4 years) |
| Decarbonisation mandates (e.g., FERC 2222) accelerating ADMS roll-outs | +3.6% | North America and Europe; expanding to Asia Pacific | Long term (≥ 4 years) |
| Cloud-native ADMS lowering entry barriers for mid-size utilities | +3.0% | Global; especially impactful for utilities in developing and mid-tier markets | Medium term (2–4 years) |
| Source: 黑料不打烊 | |||
Rapid adoption of smart-grid digitalization
Utilities are fast-tracking digital control upgrades to replace legacy systems that lack real-time situational awareness. State Grid China earmarked USD 88.7 billion for 2025 distribution automation and advanced metering deployments, cementing the region’s leadership in large-scale smart-grid roll-outs. European network operators must lift annual distribution spending to EUR 67 billion (USD 75.7 billion) to cope with electrification targets, a mandate that is forcing immediate ADMS procurement. Early adopters report a 21% fall in network outage minutes and a 17% cut in restoration time after fully integrated ADMS launches, yielding annual savings near USD 150 million.[1]General Electric Vernova, “ADMS Value Realization Case Studies,” ge.com
Growing integration of distributed energy resources
Bidirectional power flows from rooftop solar, stationary batteries, and vehicle-to-grid assets overwhelm legacy distribution management workflows. India met a record 241 GW peak load in 2024 without deficit by leveraging advanced ADMS algorithms that co-optimize solar, hydro, and battery dispatch. In the United States, FERC Order 2222 forces market participation by aggregated distributed resources, compelling utilities to seek ADMS platforms that deliver synchronized DER visibility and dispatch.
Rising energy demand and outage-reduction priorities
Extreme weather, aging assets, and data-center build-outs amplify grid stress. Data-center electricity use may jump from 130 TWh in 2023 to 307 TWh by 2030, driving utilities toward AI-enabled failure prediction that can cut unplanned outages by 30-40%.[2]American Council for an Energy-Efficient Economy, “Data Center Energy Outlook,” aceee.org Regulators are tightening reliability penalties, turning predictive maintenance from an option into an operational prerequisite.
EV-charging load balancing requirements
Concentrated EV fast-charging clusters can overload distribution feeders unless actively managed. California alone could need 25 GW of feeder capacity upgrades by 2045 if unmanaged charging persists. ADMS algorithms that coordinate charging with renewable generation have demonstrated 16–34% peak-load shaving across scenarios with 1.5–5 million vehicles.[3]MDPI, “Coordinated EV Charging Strategies,” mdpi.com
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High initial capex and integration complexity | -3.4% | Global, acute in emerging markets | Short term (≤ 2 years) |
| Cyber-security and data-privacy concerns | -2.8% | Global, strictest in North America and EU | Medium term (2–4 years) |
| Shortage of ADMS-skilled workforce | -2.1% | Global, critical in mature markets | Long term (≥ 4 years) |
| Proprietary protocols limiting interoperability | -1.9% | Global, legacy system constraints | Medium term (2–4 years) |
| Source: 黑料不打烊 | |||
High initial capex and integration complexity
Full-scale ADMS deployments can cost USD 5–50 million, excluding hardware. Long production lead times on transformers have stretched to 18–24 months, magnifying capital-allocation risk.[4]Siemens Energy, “Transformer Capacity Expansion Statement,” siemens-energy.com Interfaces to legacy SCADA and billing platforms often double project timelines, challenging smaller utilities that look for Software-as-a-Service options.
Cyber-security and data-privacy concerns
Digitization widens attack surfaces. Utilities now align with NIST, ISO/IEC 27001, and IEC 62443 frameworks, a compliance load that can delay projects by up to one year. Cloud deployments therefore follow a zero-trust architecture that encrypts data at rest and in transit.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Offering: Services Gain Momentum in a Software-Led Market
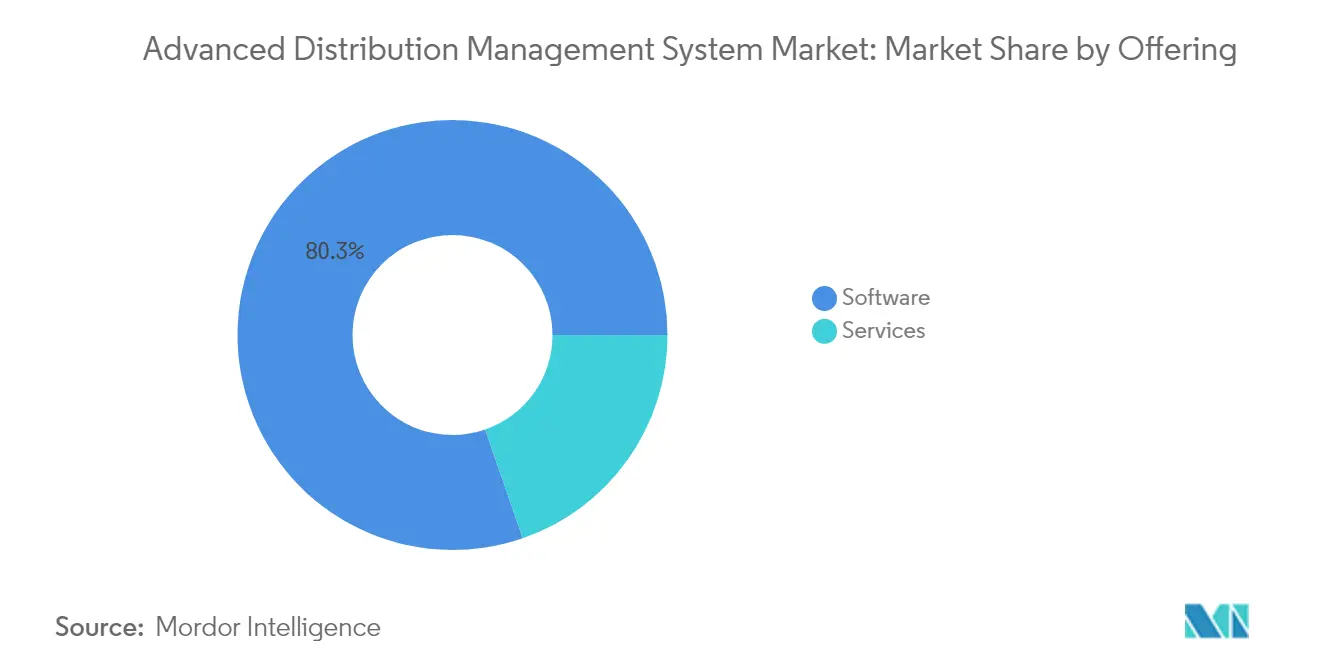
Software accounted for 80.30% of the Advanced Distribution Management System market in 2025, affirming utilities’ preference for unified control suites. The services segment is tracking a 21.40% CAGR because long-tail integration, security hardening, and continuous optimization dictate specialist support. Schneider Electric booked EUR 38.2 billion (USD 43.2 billion) in 2024 revenue, with a sizable share tied to grid-software lifecycle services. Consulting engagements typically span 12–18 months and involve interoperability testing across metering, GIS, and outage systems. These immersive projects anchor recurring service contracts that smooth revenue cyclicality.
Rapid cloud adoption widens the addressable pool of mid-tier utilities that cannot fund large data-center refreshes. Managed service agreements now bundle hosting, patching, and real-time cyber monitoring, pushing the Advanced Distribution Management System market size for services toward USD 2.25 billion by 2031.


By System Type: Energy Management Systems Accelerate
Distribution management systems held the top position, accounting for 35.20% of the Advanced Distribution Management System market share in 2025. Energy management systems exhibit a 21.05% CAGR because utilities view holistic optimization across transmission, distribution, and generation as a single economic equation. DER management modules naturally integrate with EMS frameworks, creating an integrated control plane. When utilities incorporate probabilistic renewables forecasting, they can reduce the frequency of ramping conventional generation units by 12%, resulting in lower fuel and operational costs. Front-office market bids also improve because the platform refines locational marginal price forecasts.
Meter data management and advanced metering infrastructure provide granular visibility into consumption, which feeds EMS algorithms. India’s National Smart Grid Mission cleared 22 million additional smart meters in 2024, enlarging the data lake from which AI models learn. This linkage between meter data and EMS decision support underpins future energy-as-a-service propositions.
By End-User Vertical: IT and Telecom Outpaces Core Utility Spend
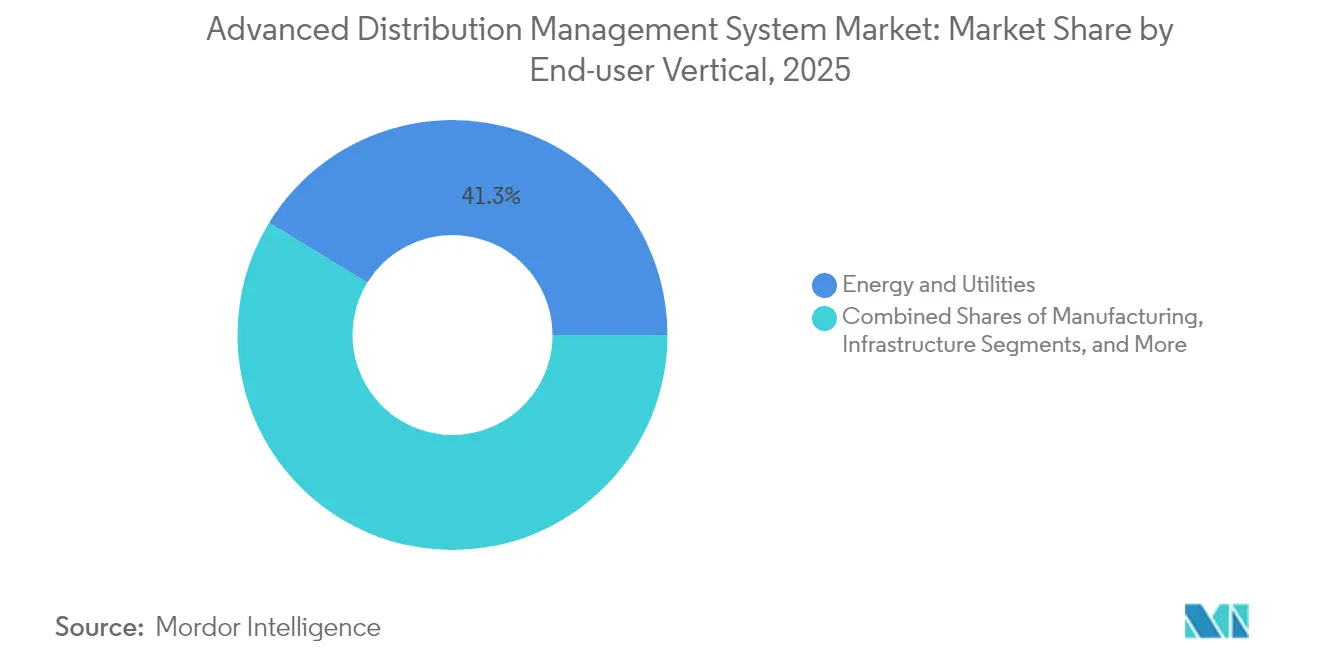
Utilities commanded 41.25% of 2025 revenue, but hyperscale data-center and telecom operations are the fastest movers at a 22.60% CAGR. Operators are converting backup generators into market-participating microgrids and monetizing flexibility on ancillary-service markets. Sophisticated ADMS deployments enable them to curtail or shift megawatt-scale loads within seconds, an attractive feature in power-price-volatile regions. Manufacturing adoption is driven by process electrification strategies that align production runs with real-time tariffs. Defense agencies are piloting resilient microgrids that island seamlessly during cyber or physical disruptions. Together, these non-utility verticals will exceed 30% of Advanced Distribution Management System industry revenue by 2031.
By Deployment Mode: Cloud and Hybrid Architectures Advance
On-premise remains prevalent at 46.50% of 2025 revenue due to security sensitivities. Yet cloud-based installations are growing at 21.35% annually as vendors certify systems on FedRAMP and comparable schemes, satisfying public-service cyber requirements. Hybrid architectures are emerging, locating latency-critical feeder automation onsite while streaming non-critical data to the cloud for heavy analytics. Connexus Energy completed such a transformation in December 2024, migrating its GIS and analytics workloads to the cloud while retaining real-time SCADA on secure local servers. This approach yields quicker feature updates and reduces on-premise hardware refresh cycles.
Geography Analysis
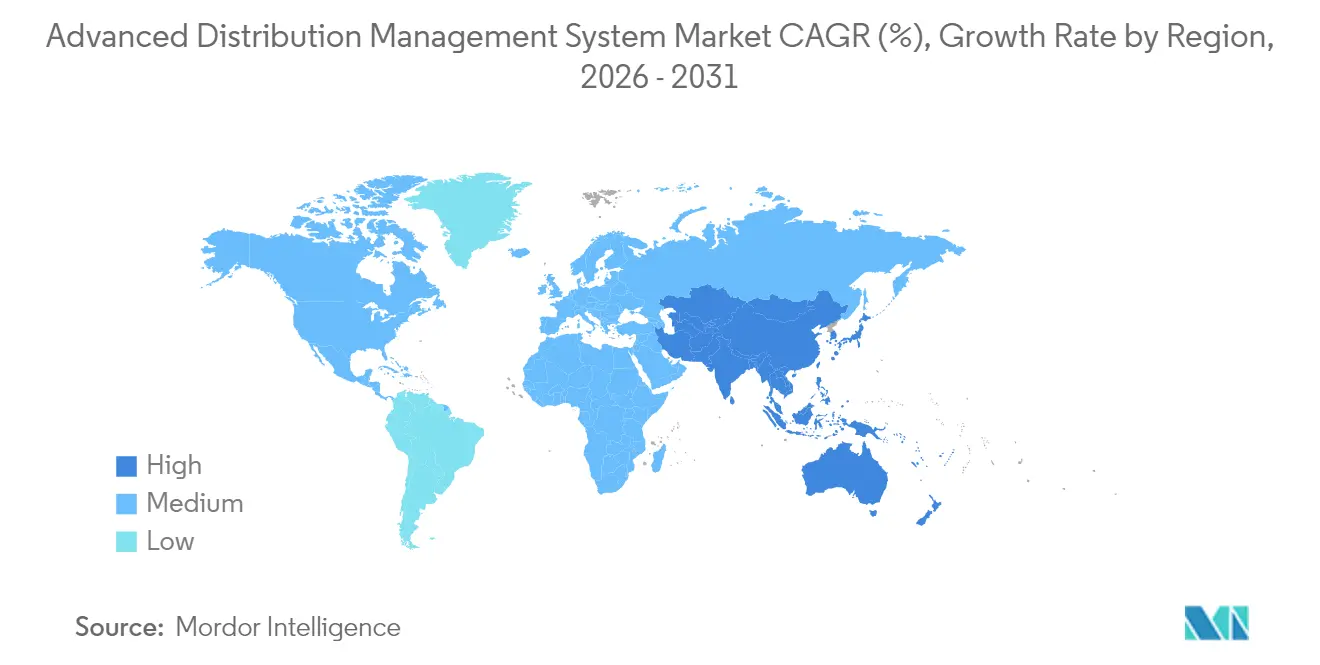
Asia-Pacific is on track for a 21.70% CAGR through 2031, propelled by State Grid China’s USD 88.7 billion 2025 allocation and strong Indian incentives for smart meters and feeder automation. Governments in the region prioritize distribution efficiency to integrate rooftop solar and a surging electric two-wheeler fleet. Europe faces mandatory annual distribution upgrades of USD 75.7 billion to honor fit-for-55 decarbonization rules. Advanced Distribution Management System market size in Europe will expand steadily as network operators front-load digital overlays before heavier conductor and transformer replacements.
North America, which controlled 39.30% of global revenue in 2025, continues to modernize under FERC Order 2222 and state resilience funding. Severe weather incidents justify real-time outage prediction analytics, and utilities are piloting AI-based network reconfiguration to trim public safety power shutoff events in wildfire-prone regions. Latin America is at an earlier stage, yet benefits from multilateral financing directed at loss reduction. African utilities focus first on revenue protection and feeder automation before rolling out full ADMS suites, but mobile-native cloud solutions could accelerate adoption.
Supply-chain friction is a universal constraint. Copperweld forecasts an 8 million-ton annual copper shortfall by 2034, which could inflate switchgear and conductor costs. Semiconductor shortages add delay to feeder automation hardware. Vendors now hedge by dual-sourcing custom ASICs and deploying flexible microcontroller designs that can accept alternative silicon.

Regulatory Landscape
Regulation for ADMS-related capabilities is shaped by market-access rules, cyber requirements, and interoperability guidance. In the United States, FERC Order No. 676-K (issued November 2024) requires public utilities to incorporate by reference NAESB WEQ Version 004 standards in their open access transmission tariffs, reinforcing standardized business practices and communications that influence how grid-operating platforms exchange data across the enterprise. In the reliability layer, FERC approved NERC Reliability Standard CIP-003-11 in March 2026, tightening cybersecurity controls for low-impact BES Cyber Systems, and utilities often align distribution digitalization programs with these controls to reduce audit and incident risk.
A key compliance nuance is the distribution-level cybersecurity gap. NERC CIP requirements apply to the Bulk Electric System, leaving many distribution ADMS deployments primarily governed by state regulators and utility risk programs. As a result, utilities often reference NIST-aligned practices and IEC 62443 and ISO/IEC 27001 control frameworks during procurement and implementation, particularly for cloud and hybrid deployments. Federal programs are also pushing toward verifiable interoperability, with DOE (including national-lab support) advancing test and verification methods for ADMS data integration interfaces, with completion targets set around 4Q FY26. That increases the importance of standards-based integration such as CIM (IEC 61968/61970).
Value Chain Analysis
The ADMS value chain starts with foundational technology inputs such as grid standards and data models (for example, CIM under IEC 61968/61970), cybersecurity frameworks (NIST-aligned practices, IEC 62443), and edge and cloud compute infrastructure. Core platform providers deliver ADMS software suites, often bundling DMS, OMS, and DER orchestration, while ecosystem partners supply enabling layers including GIS network models, AMI and MDMS feeds, and weather and asset-health data. System integrators and utility-focused IT services firms then configure the operating model, build interfaces to legacy SCADA and customer systems, and run long-duration validation and cutover programs, which makes the services portion of deployments particularly prominent.
Downstream, utilities procure ADMS either as on-premise or hybrid environments for latency-sensitive control, or as cloud-hosted subscriptions where security certification and operational monitoring are bundled. Recent deal activity also shows where vendor and integrator roles overlap: CGI and Schneider Electric expanded their partnership in February 2026 to deliver end-to-end ADMS and GIS solutions for energy providers in the DACH region, and Emerson announced in May 2026 that Oncor selected AspenTech OSI ADMS to enhance visibility, automation, and outage management. Smaller operators are increasingly testing shared delivery models to reduce integration burden, as in May 2026 when Waipa Networks agreed to implement an ADMS through a co-hosted setup with WEL Networks, highlighting a route for mid-tier networks to access enterprise-grade operations tooling.
Competitive Landscape
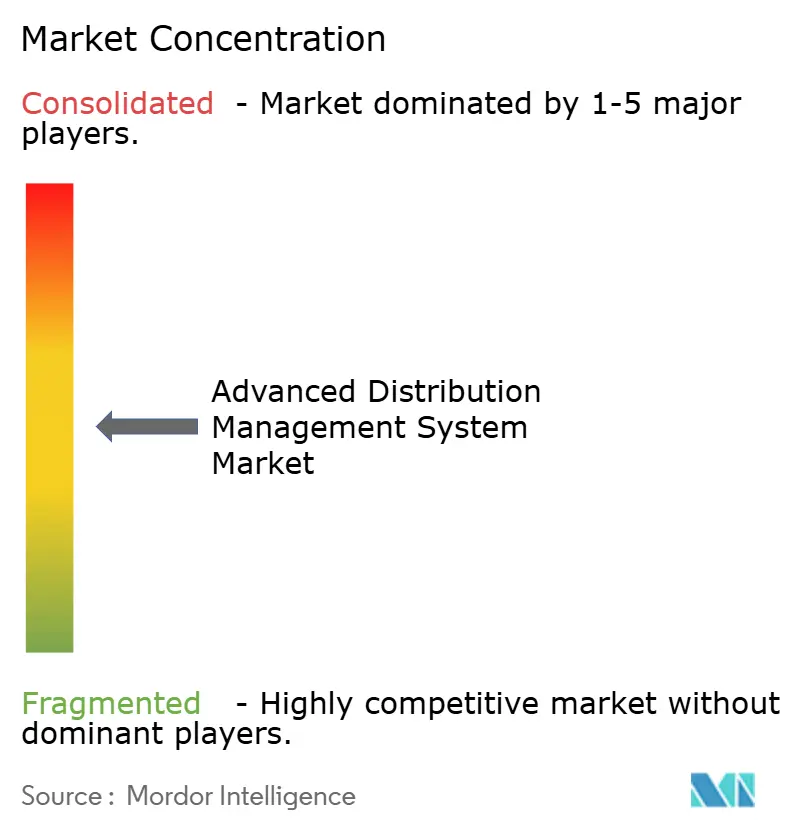
The market remains moderately consolidated. ABB, Siemens, Schneider Electric, and GE combine hardware, software, and services into turnkey propositions, raising customer switching costs. Hitachi Energy has committed USD 6 billion through 2027, including USD 4.5 billion for grid software and USD 1.5 billion for high-voltage products, to sharpen its competitiveness. Siemens Energy will open new U.S. transformer capacity by 2027 to alleviate bottlenecks and secure its hardware-software bundle.
Cloud-only challengers exploit subscription pricing to undercut large upfront licenses. Their differentiator lies in deployment speed and microservices architectures that integrate smoothly with GIS, AMI, and customer portals. Artificial intelligence is the emerging battleground. Vendors embed machine-learning models for outage prediction, topology optimization, and DER aggregation. Partnerships with hyperscale cloud providers accelerate the AI roadmap by tapping into advanced GPU resources and model-training pipelines.
Edge computing is a white-space opportunity. Several startups are embedding containerized ADMS agents in substation gateways to process phasor data locally, ensuring autonomous control if communications drop. Established suppliers respond by adding lightweight runtime versions of their ADMS engines.
Advanced Distribution Management System Industry Leaders
ABB Group
General Electric Company
Siemens AG
Schneider Electric SE
Eaton Corp.
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Interoperability-led modernization is a visible whitespace as utilities standardize network models and data exchange across operations and planning. In April 2026, Ameren completed the next production phase of its CIM-based Grid Network Model Management program, publishing model data into its ADMS and Synergi Electric planning environment. This points to demand for vendor solutions and services that operationalize CIM at scale, including model governance, publishing pipelines, and continuous synchronization. Similar utility programs also elevate opportunities for ADMS vendors that package CIM tooling, data-quality automation, and pre-built connectors to GIS and planning applications.
Another opportunity area centers on digitalization funding and regulatory mechanisms that explicitly allocate budget to ADMS-adjacent data platforms and operational tooling. In January 2026, Scottish and Southern Electricity Networks filed a Distribution Digitalisation re-opener application that included a GBP 4.03 million request for implementing data fabric technology within its ADMS, which indicates active spend tied to measurable digital outcomes. Municipal and mid-size utilities add incremental demand through discrete procurements, including the City of Naperville awarding cooperative procurement 26-118 in April 2026 for ADMS infrastructure and professional services (authorized not to exceed USD 557,532.17). Together, these signals support near-term demand for modular deployments, managed services, and phased rollouts that lower integration risk while enabling DER visibility, outage automation, and analytics improvements.
Recent Industry Developments
- March 2026: Octopus Energy announced plans to acquire a majority stake in Uplight, in partnership with Schneider Electric, to scale flexible and digitalized grid capabilities across North America. The transaction strengthens the software ecosystem around utility flexibility, demand-side orchestration, and data-driven grid operations that increasingly interface with ADMS environments.
- February 2026: GE Vernova launched GridOS for Distribution, positioning a unified software platform that brings together ADMS functions with DER management and planning analytics. The platform-level approach supports utilities seeking consolidated operations and faster addition of analytics and AI modules without managing fragmented point solutions.
- December 2025: Schneider Electric introduced the One Digital Grid Platform, built on EcoStruxure ADMS, DERMS, and ArcFM to unify grid planning, operations, and asset management. The release reinforces the market shift toward integrated suites that tighten GIS-to-operations workflows and accelerate digital utility transformation programs.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this methodology, the advanced distribution management system (ADMS) market covers software platforms and related services that help utilities and grid operators monitor, control, visualize, optimize, and automate electric distribution networks, including functions that support outage response and distributed energy operations.
Scope exclusions: This sizing does not count physical grid equipment and field devices (such as sensors, switches, meters, or communications hardware) unless the value is explicitly packaged and sold as part of the ADMS software or service contract.
Segmentation Overview
- By Offering
- Software
- Distribution Management System (core engine)
- DER Management Module
- Outage Management Module
- Services
- Consulting
- System Integration
- Support and Maintenance
- Software
- By Deployment Mode
- On-premise
- Cloud
- Hybrid
- By System Type
- Distribution Management System (DMS)
- AMR / AMI
- DER Management System (DERMS)
- Energy Management System (EMS)
- Customer Information System (CIS)
- Meter Data Management System (MDMS)
- By End-user Vertical
- Energy and Utilities
- IT and Telecom
- Manufacturing
- Defense and Government
- Infrastructure
- Transportation and Logistics
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set the market perimeter and build the first demand signals for ADMS adoption, using public and official references that are repeatable. Sources such as the US Energy Information Administration (utility grid and reliability context), the International Energy Agency (power networks and investment trends), NIST smart grid references, IEEE journals on distribution automation and operations, and US Department of Energy program publications were reviewed to anchor definitions and typical use cases.
We also checked company annual reports, investor presentations, utility procurement notes, and reputable press to understand how software licensing, cloud delivery, and support contracts are commonly structured and priced. When needed, a paid subscription focused on company financials and intelligence was used to cross-check revenue mixes and reduce the risk of double counting adjacent software categories. The desk sources mentioned here are illustrative, and additional public documents were reviewed for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work focused on interviews and short surveys with utility operations leaders, grid modernization program teams, system integrators, and ADMS product specialists, so the model reflects how projects are actually scoped and purchased. For a global market like this, inputs were checked across Americas, EMEA, and APAC to test assumptions on rollout speed, cloud migration, and how utilities bundle OMS, DERMS, and core DMS functions.
These discussions were used to close data gaps from public sources and to sanity-check pricing ranges and implementation timelines before finalizing the market totals.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 31% | CXOs: 14% | APAC: 42% |
| Mid tier: 54% | Functional/Unit leaders: 38% | EMEA: 37% |
| Smaller Players: 15% | Managers: 48% | Americas: 21% |
Market-Sizing & Forecasting
Sizing started from a top-down build where utility digital grid spending signals, distribution automation penetration, and software share assumptions were used to reconstruct the addressable ADMS demand pool by region and year. To keep the result grounded, we corroborated totals with selective bottom-up approximations, including sampled contract values from public deal disclosures where available, typical license plus services mixes, and a reasonableness check using supplier revenue exposure to ADMS-like offerings.
Key inputs in the model included the pace of smart grid modernization programs, distributed energy resource interconnection pressure, outage response performance focus (reliability improvement programs), the split of on-premise versus cloud deployment, and the services intensity seen in implementation and ongoing support. Forecasts were built using scenario analysis, where adoption and pricing paths were tested under slower and faster utility rollout cycles, then adjusted based on what primary respondents described as realistic procurement timing. Where bottom-up data points were missing in smaller countries or in early-stage deployments, assumptions were filled using proxy adoption rates from similar grid maturity profiles and then rechecked against regional spending capacity.
Data Validation & Update Cycle
Outputs were validated through multiple checks so the totals align with real-world signals, not just one data series. We compared modeled values against independent indicators such as utility IT and grid modernization budgets, the expected volume of multi-year platform deployments, and the implied average contract value ranges, then flagged any sharp year-to-year jumps for review.
Before sign-off, results move through stepwise analyst reviews, and follow-up calls are triggered when interview feedback shows a material mismatch on deployment mix, bundling, or services share. Reports are refreshed annually, with interim updates when major policy, grid investment, or technology shifts can change adoption timing. Right before delivery, a final update pass is done so clients receive the latest view based on newly available public information and recent expert feedback.
黑料不打烊's Advanced Distribution Management System Market Size Versus Other Published Estimates
Published estimates for ADMS often vary because firms do not always count the same software functions and services, and they can also choose different base years and currency timing. Differences show up most when adjacent platforms are bundled into one number, or when the services portion is assumed to be either very light or very heavy.
The main gap comes from how closely outage management, DERMS, and related utility IT platforms are grouped into the ADMS total, and in 黑料不打烊 modeling these system types are counted only when they are positioned and purchased as part of an ADMS suite rather than generic utility software. Other studies also diverge on whether deployment shifts to cloud are assumed to reduce service intensity over time, which changes the implied average selling price path and the near-term market size.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 4.31 B (2026) | |
| Industry Publication A | USD 1.95 B (2021) | Uses an earlier base year and a narrower adoption stage, and the scope appears centered on core utility distribution operations with less explicit bundling of broader end-use vertical deployments. |
| Research Outlet B | USD 5.07 B (2026) | Likely applies a wider software definition and a higher assumed services attachment rate per deployment, which can lift the same-year value even when functional scope overlaps. |
The table shows that timing and scope choices explain most of the spread, more than simple math differences. When the counted functions are clearly defined and the pricing logic is tied back to deployment mix and service intensity, the resulting market size becomes easier to trace and to reuse in planning.


Key Questions Answered in the Report
What is the current value of the Advanced Distribution Management System market?
The Advanced Distribution Management System market is valued at USD 4.31 billion in 2026 and is projected to reach USD 10.53 billion by 2031 at a 19.60% CAGR.
Which region dominates revenue in 2025?
North America leads with 39.30% of global revenue thanks to regulatory mandates such as FERC Order 2222.
Why are services growing faster than software?
Utilities increasingly depend on integration, cyber-security, and continuous optimization expertise, pushing services toward a 21.40% CAGR through 2031.
How do electric vehicles influence ADMS demand
Coordinated EV charging requires real-time feeder balancing and bidirectional power flow control that only an advanced ADMS platform can deliver, driving new deployments.
What supply-chain risks could slow market growth?
Projected copper deficits, semiconductor scarcity, and a shrinking pool of skilled utility workers threaten project timelines and cost structures.
Who are the leading vendors?
ABB, Siemens, Schneider Electric, GE, and Hitachi Energy currently hold a majority share, though cloud-native entrants are gaining traction with subscription models.
Page last updated on:



