
Wireless Infrastructure Monitoring Market Size and Share
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Market Size (2026) | USD 5.32 Billion |
| Market Size (2031) | USD 9.69 Billion |
| Growth Rate (2026 - 2031) | 12.74 % |
| Fastest Growing Market | Middle East and Africa |
| Largest Market | Asia Pacific |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Wireless Infrastructure Monitoring Market Analysis by 黑料不打烊
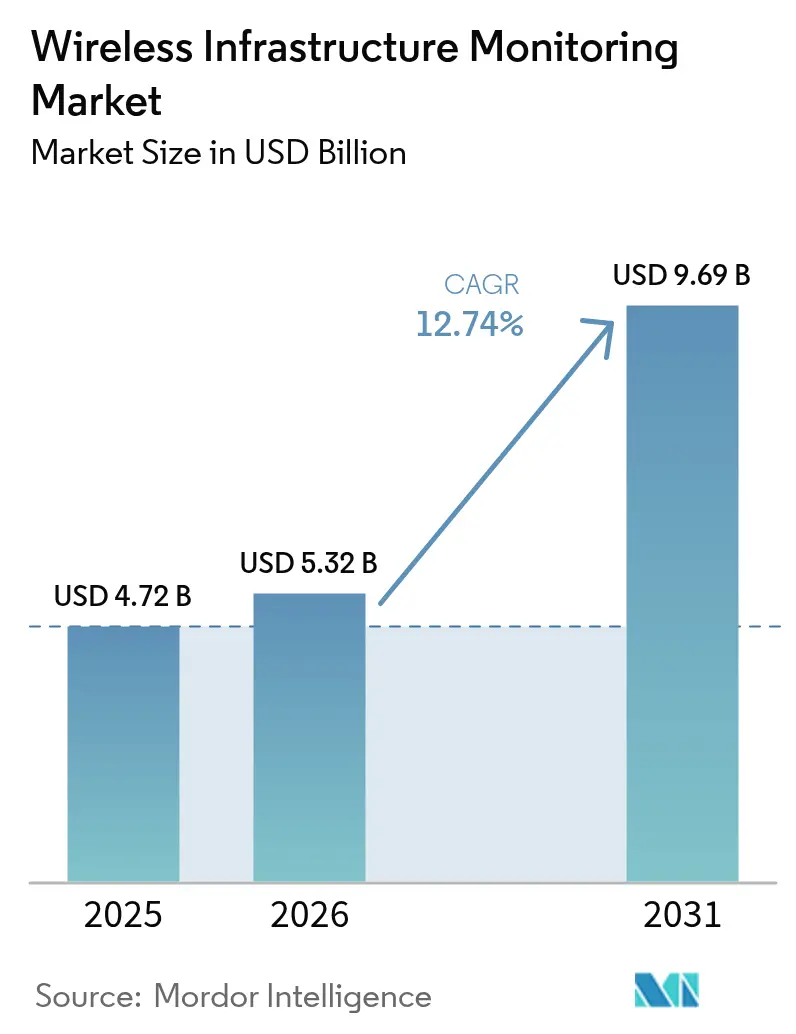
The wireless infrastructure monitoring market size is expected to grow from USD 4.72 billion in 2025 to USD 5.32 billion in 2026 and is forecast to reach USD 9.69 billion by 2031 at 12.74% CAGR over 2026-2031. Uptake is accelerating as infrastructure owners migrate from reactive to predictive maintenance, deploying dense, low-power sensor grids that cut downtime and extend asset life. Asia Pacific holds the largest regional position, buoyed by rapid urbanization and smart-city programs, while the Middle East delivers the fastest compound growth on the back of megaprojects and harsh-environment compliance requirements. Hardware remains the revenue backbone, but managed services and analytics now capture the greatest incremental value as end users seek actionable insights rather than devices. Convergence of LPWAN and 5G is expanding the addressable use-cases spectrum, particularly for high-bandwidth video analytics and AI-based anomaly detection.
Key Report Takeaways
- By component, hardware commanded 60.85% of the wireless infrastructure monitoring market share in 2025; services are projected to expand at a 13.92% CAGR through 2031.
- By connectivity, LPWAN held 37.22% revenue share in 2025; 5G/cellular is the fastest-growing segment at a 13.54% CAGR to 2031.
- By application, structural monitoring accounted for a 45.62% share of the wireless infrastructure monitoring market size in 2025, while corrosion monitoring grew at a 13.98% CAGR to 2031.
- By infrastructure type, bridges and tunnels led with a 29.18% share in 2025; renewable energy assets exhibit the highest forecast CAGR at 13.32% through 2031.
- By sensor, strain/stress gauges occupied 32.76% share in 2025; accelerometers/vibration sensors rise at a 15.26% CAGR to 2031.
- By end-user, civil infrastructure owners held 34.62% share in 2025; utilities and energy companies post the fastest 14.41% CAGR between 2026-2031.
- By region, Asia Pacific captured 28.34% regional share in 2025; the Middle East is projected to grow at 14.06% CAGR to 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of Wireless Infrastructure Monitoring Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| 5G roll-outs demanding tower integrity verification | +3.5% | Global; early uptake in North America, Europe, East Asia | Medium term (2-4 years) |
| Digital-twin mandates for aging bridges | +2.6% | North America and EU | Medium term (2-4 years) |
| LPWAN sensor cost decline enabling dense grids | +2.3% | Global; pronounced in developing regions | Short term (≤ 2 years) |
| Insurance-linked monitoring for tailings dams | +2.2% | Latin America; spillover to other mining hubs | Medium term (2-4 years) |
| Offshore-wind corrosion monitoring | +2.1% | Europe, East Asia, emerging North America | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
5G roll-outs demanding tower integrity verification
The densification of 5G networks places heavier wind and vibrational loads on existing towers. Operators now embed continuous structural health monitoring to detect early fatigue, optimize maintenance scheduling, and ensure regulatory compliance. Real-time analytics have trimmed tower energy consumption by 20% through dynamic power adjustment.[1]Na Xu, “Design and Implementation of a Cloud-Based Energy Monitoring System for 5G Base Stations,” digital-library.theiet.org
Digital-twin mandates for aging bridges in the US & EU
Regulators increasingly require digital replicas supported by live sensor data, extending bridge lifespans by up to 20% while reallocating maintenance budgets toward assets exhibiting real structural stress. Sixty-six Horizon 2020 projects now target wireless inspection technologies.
LPWAN sensor cost decline enabling dense monitoring grids
Sensor price erosion of more than 35% since 2023 allows municipalities to deploy hundreds of nodes per structure, improving detection accuracy. A Bulgarian water-utility pilot confirmed LoRaWAN’s long-range and low-power benefits while meeting regulatory mandates.
Insurance-linked monitoring for tailings dams in LatAm
Insurers now demand real-time seepage and deformation data before underwriting high-risk mining assets. Compliance needs elevate reliability over price, favoring certified solution providers.
Restraints Impact Analysis of Wireless Infrastructure Monitoring Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Signal Attenuation inside Reinforced Concrete | -1.6% | Global, with higher impact in dense urban environments | Short term (≤ 2 years) |
| Data-Sovereignty Barriers for Cloud Analytics in ME | -0.8% | Middle East, with spillover to parts of Asia and Africa | Medium term (2-4 years) |
| Funding Gaps for Small Municipal Infrastructure Owners | -0.7% | Global, with higher impact in developing economies and rural areas | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Signal attenuation inside reinforced concrete
Steel rebar forms a Faraday cage, forcing integrators to add gateways or higher-power transmitters, raising capex and maintenance. New sub-GHz protocols such as VaiNet improve penetration, reducing repeater count.
Data-sovereignty barriers for cloud analytics in the Middle East
National mandates to localize data escalate deployment costs and fragment architectures. Multinationals must build in-country clouds or adopt on-premise analytics, delaying roll-outs. [2]International Monetary Fund, “Regional Economic Outlook: Middle East and Central Asia,” imf.org
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Wireless Infrastructure Monitoring Market Segment Analysis
By Component:
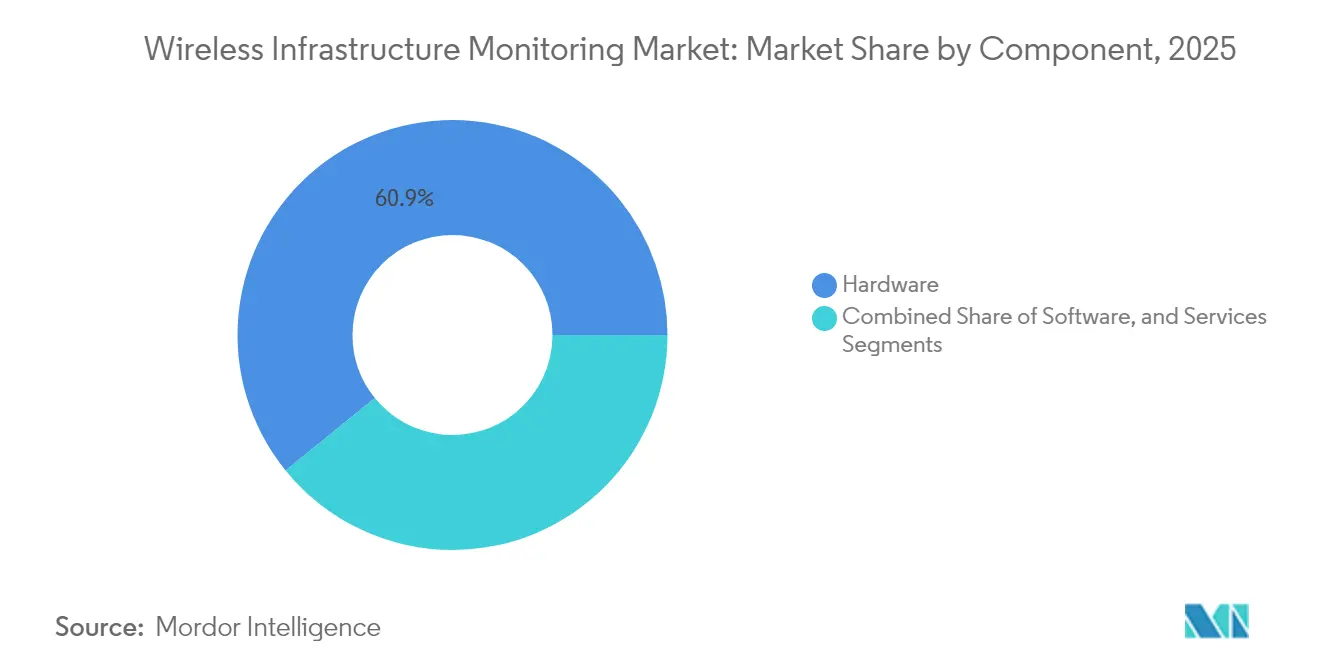
Services Gain Momentum Over Hardware DominanceHardware captured 60.85% of the wireless infrastructure monitoring market in 2025, owing to large-scale sensor roll-outs across bridges, dams, and energy assets. Yet, services are scaling at a 13.92% CAGR as owners prioritize insight extraction over device procurement. Managed analytics contracts now bundle hardware, gateways, and predictive dashboards, generating higher margins than product sales. Gateways that translate multiple protocols into unified data streams are the fastest-growing hardware sub-segment, enabling fleet-wide visibility. Packet Power notes that predictive maintenance can halve downtime and cut maintenance costs by 30%.
The software layer, though smaller, anchors long-term value. Vendors embed AI algorithms that transform raw time-series data into actionable alerts and automated work orders. As systems mature, differentiation shifts from sensor specs to outcome-based service level agreements, with vendors staking revenue on uptime guarantees. This service-centric model locks in recurring cash flows and raises switching costs, underpinning consolidation moves across the wireless infrastructure monitoring market.


By Connectivity Technology:
LPWAN Holds Lead while 5G Unlocks High-Bandwidth Use-casesLPWAN delivered 37.22% revenue in 2025, balancing multi-year battery life with kilometer-scale range. It underpins the majority of long-cycle civil-infrastructure deployments where data packets are small but frequent. Conversely, 5G/cellular revenues advance at 13.54% CAGR, powering real-time video feeds and edge-AI analytics for mission-critical assets. A hybrid deployment model leveraging LPWAN for baseline telemetry and 5G overlays for peak-data events is emerging as the reference architecture for nationwide wireless infrastructure monitoring systems. This integrated approach optimizes operating costs while maximizing bandwidth availability for advanced analytics and event-driven applications.
Bluetooth and Wi-Fi retain relevance for short-range building and industrial plants leveraging existing LAN coverage, while satellite links unlock remote, off-grid deployments. IEEE studies confirm the LPWAN-5G integration path as central to scaling billions of IoT nodes.
By Application:
Structural Monitoring Dominates, Corrosion Detection AcceleratesStructural monitoring accounted for 45.62% of 2025 revenue, driven by aging bridges and seismic-prone geographies demanding continuous integrity checks. The wireless infrastructure monitoring market share for corrosion detection is expanding fastest at 13.98% CAGR to 2031, propelled by offshore wind farms and coastal infrastructure where saltwater accelerates degradation.
Integrated deployments correlate vibration, strain, and environmental data, yielding richer diagnostics than siloed installations. The iWindCr project validates miniature corrosion sensor arrays for turbine foundations.
By Infrastructure Type:
Bridges Lead; Renewables SurgeBridges and tunnels contributed 29.18% of 2025 spending as governments tackle deferred maintenance backlogs. Renewable energy assets, chiefly offshore wind, deliver the highest 13.32% CAGR, reflecting rapid capacity additions and harsh-condition monitoring needs.
Buildings adopt wireless sensors within smart-building strategies, while dams leverage long-range telemetry for early leak detection. Mining and oil-and-gas operators deploy resilience programs to satisfy insurer and regulator mandates, reinforcing the addressable scope for the wireless infrastructure monitoring market.
By Sensor Type:
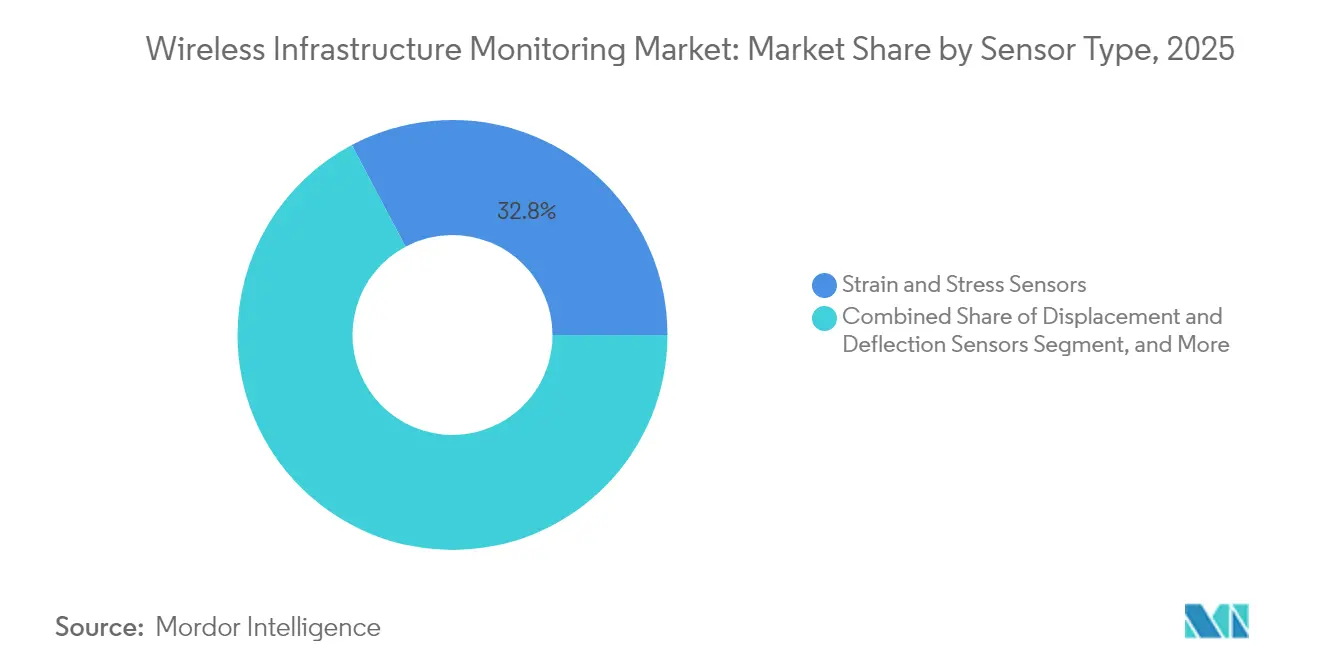
Strain Gauges Remain Cornerstone while Accelerometers OutpaceStrain/stress gauges held 32.76% revenue share in 2025, forming the backbone of structural health systems. Accelerometers and vibration sensors, however, register a 15.26% CAGR as multivariate analytics connect dynamic response data to fatigue modeling.
Temperature, humidity, and inclination sensors supply contextual parameters, enhancing model accuracy. Rising research output on smart sensor integration between 2019-2024 underscores technology maturation.
By End-user:
Civil Infrastructure Owners Dominate; Utilities Scale FastCivil owners control 34.62% of the 2025 demand, funding sensor retrofits to prolong design lifespans. Utilities and energy firms are the fastest risers at 14.41% CAGR as grid modernization and renewable integration intensify monitoring needs.
Smaller municipalities embrace turnkey SCADA plus wireless monitoring to satisfy regulatory standards, illustrated by Seguin, Texas, upgrading its electrical utility network.
Geography Analysis
APAC and Middle East Wireless Infrastructure Monitoring Market
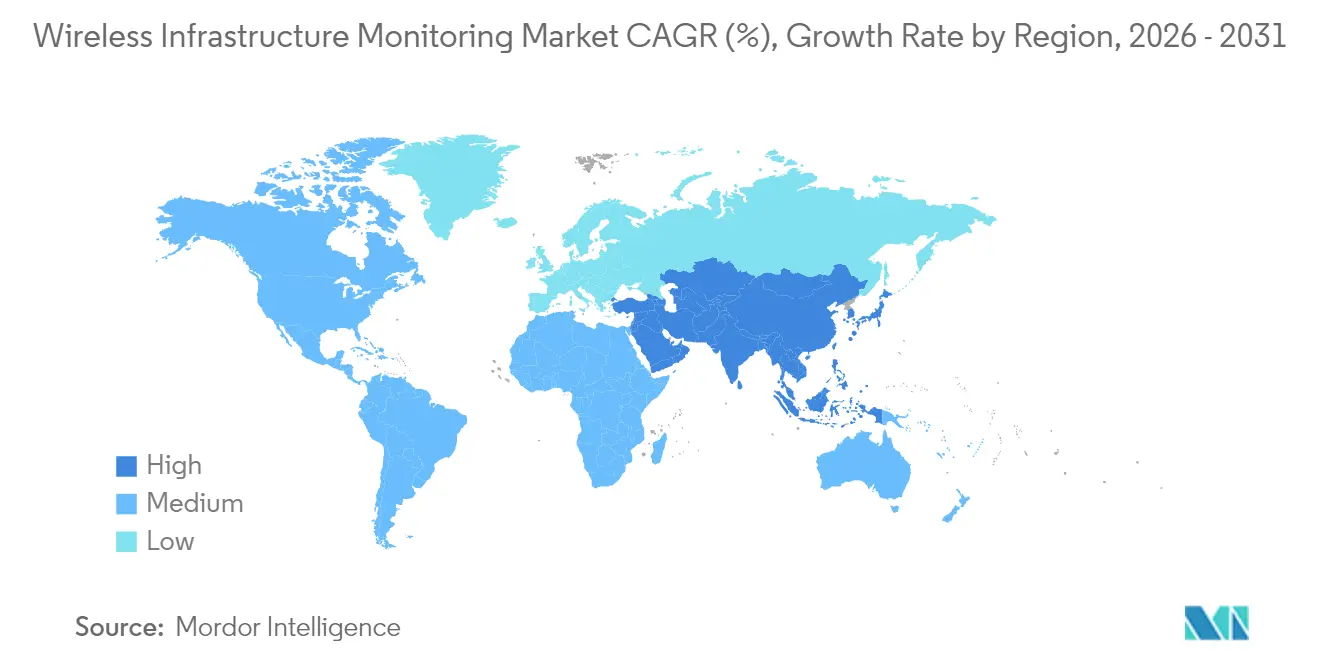
Asia Pacific retained 28.34% of global revenue in 2025, led by China, Japan, and South Korea, where IoT adoption supports national smart-city agendas. India’s smart-city mission and ASEAN infrastructure upgrades further widen the regional base. The Middle East is forecast to clock the fastest 14.06% CAGR through 2031, propelled by GCC megaprojects and mandatory monitoring standards for arid-climate resilience. Regional data-sovereignty rules, however, steer deployments toward localized clouds, shaping vendor go-to-market models across the wireless infrastructure monitoring market.
The Americas, Europe and Africa Wireless Infrastructure Monitoring Market
North America remains a mature but significant arena, channeling federal funds into bridge and roadway integrity programs. Insurance mandates expedite adoption for high-risk assets such as tailings dams. Europe leverages stringent safety directives and Horizon 2020 funding to extend the lifespans of mid-20th-century infrastructure, with digital twin pilots multiplying. South America focuses on mining and hydroelectric monitoring amid challenging topographies, whereas Africa, though nascent, offers greenfield opportunities aligning with new infrastructure investment waves.

Regulatory Landscape
Wireless infrastructure monitoring deployments are increasingly shaped by telecom security, equipment authorization, and 5G performance test requirements that determine which sensors, gateways, and radios can be used on critical assets. In the United States, the Federal Communications Commission (FCC) tightened attention on resilience and security in 2026, including actions tied to equipment authorization post-market surveillance (May 2026) and expanded cybersecurity expectations for critical communications systems, reinforcing the need for continuous monitoring of both physical integrity and cyber posture across fielded infrastructure.
In Europe and other major markets, standardization and national security frameworks are driving minimum technical and assurance baselines for connected monitoring. ETSI published TS 138 161 V19.3.0 (April 2026), updating 5G NR user equipment TRP/TRS requirements that feed into validation practices for 5G-connected monitoring endpoints and gateways. Country-level security regimes also add compliance layers for telecom-adjacent monitoring stacks, including the UK Telecommunications Security Code of Practice (2026 version, v1.1) and national schemes such as Germanys BSI TR-03163 and Indias ITSAR, pushing operators and infrastructure owners toward certified components, auditable data handling, and documented supply-chain controls.
Value Chain Analysis
The value chain begins with sensor and instrumentation suppliers (strain, vibration, corrosion, and environmental sensing), followed by gateway and connectivity providers covering LPWAN, cellular/5G, Wi-Fi/Bluetooth, and satellite links for remote assets. Data acquisition and device management then feed cloud or on-premise analytics platforms that support alerting, digital-twin feeds, and work-order integration, which are followed by deployment and lifecycle services delivered by system integrators, engineering firms, and telecom or managed-service providers that design networks, harden security, and maintain fleets under service-level agreements.
In practice, differentiation is increasingly tied to certification, security, and operational readiness, not sensor specifications alone. Telecom security guidance from bodies such as GSMA and incident reporting and resilience practices highlighted by ENISA (telecom security incidents reporting, 2024) underscore the importance of secure-by-design device onboarding, key management, and continuous monitoring within the delivery chain. Supply availability and site logistics also affect lead times, which is why buyers often seek vendors that can bundle hardware, connectivity, and managed analytics, and that can support localized architectures in data-sovereignty markets through regional hosting or on-premise processing.
Competitive Landscape
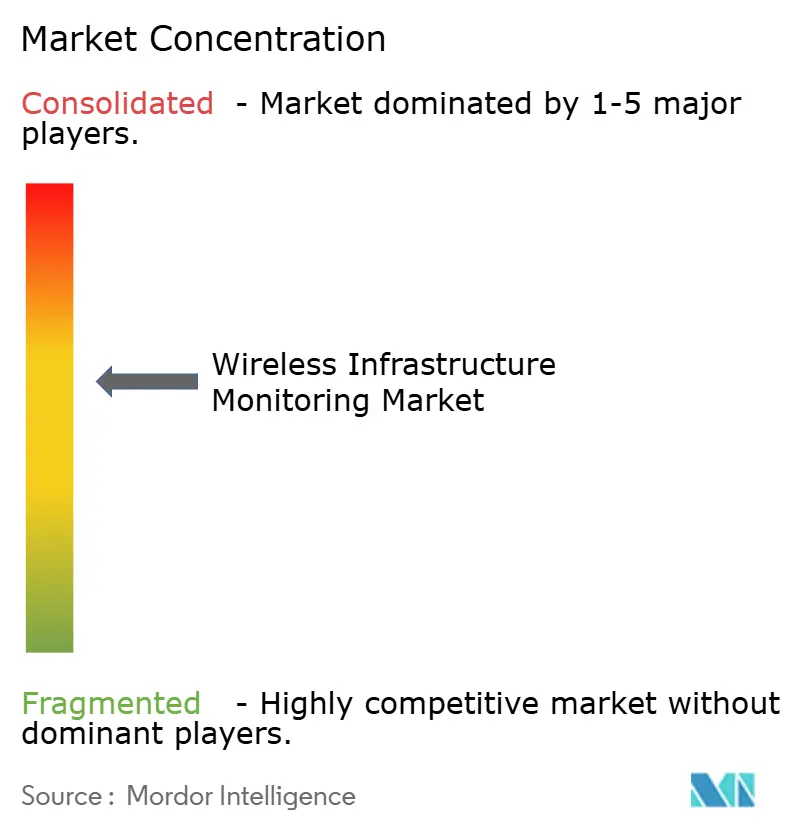
The wireless infrastructure monitoring market is moderately fragmented. Niche specialists supply rigorously certified sensors for targeted applications, while diversified technology firms integrate sensing, connectivity, and AI analytics into unified platforms. Strategic alliances between sensor makers, telecom operators, and engineering consultancies create one-stop solutions that span deployment, data analytics, and lifecycle services. Vendors increasingly pursue outcome-based contracts with predictive uptime guarantees, anchoring annuity revenues.
Disruptors exploit energy harvesting, MEMS miniaturization, and edge ML to overcome legacy hurdles such as battery life and signal attenuation. Certification from bodies like the American Bureau of Shipping provides market differentiation, particularly for offshore and maritime applications. Data-sovereignty trends encourage region-specific champions proficient in local compliance. M&A activity targets portfolio breadth and cross-selling into adjacent IoT verticals, signaling a gradual path toward consolidation.
Wireless Infrastructure Monitoring Industry Leaders
Acellent?Technologies, Inc.?
Monnit Corporation
Sisgeo S.r.l.
Campbell Scientific, Inc.
Geokon, Inc.
- *Disclaimer: Major Players sorted in no particular order
Wireless Infrastructure Monitoring Market Companies Covered in this Report
- Acellent Technologies, Inc.
- Monnit Corporation
- Sisgeo S.r.l.
- Campbell Scientific, Inc.
- Geokon, Inc.
- RST Instruments Ltd.
- Nova Metrix LLC
- Worldsensing SL
- Ackcio Pte Ltd.
- Xylem Inc.
- Honeywell International Inc.
- Cisco Systems, Inc.
- Schneider Electric SE
- Trimble Inc.
- HBM (HBK)
- National Instruments Corp.
- Fugro N.V.
- James Fisher & Sons plc
- Smart Structures Inc.
- Sixense Group
- Move Solutions Srl
- Sonicu
- Sensemetrics Inc.
- Vaisala
Read Analysis of Wireless Infrastructure Monitoring Companies

Market Opportunities and Future Outlook
Opportunities are widening where monitoring moves beyond traditional structural health use cases into security, resilience, and spectrum-aware operations on existing wireless infrastructure. Integrated Sensing and Communications (ISAC) on cellular networks is shifting from concept to funded prototypes and field demonstrations, with Department of Defense funding awarded to Cohere Technologies in July 2026 for a multi-waveform RAN prototype oriented to continuous air and ground monitoring. AT&T and Ericsson also demonstrated drone detection using Massive MIMO radios in July 2026, highlighting a route where sensing and anomaly detection can be delivered as software and radio feature upgrades rather than as standalone, dedicated monitoring networks.
A related whitespace is securing RF environments around high-value infrastructure and data centers, where wireless monitoring becomes part of physical and cyber defense. Oracle and Bastille initiated a global deployment in April 2026 aimed at protecting hyperscale AI data centers from RF-based attacks and unauthorized emitters, supporting demand for continuous spectrum/RF visibility, device geolocation, and policy enforcement. On the standards side, ETSI work on telemetry and network visibility, including F5G-related specifications, supports multi-vendor observability and can reduce integration friction for buyers that want hybrid architectures combining LPWAN baseline telemetry with 5G overlays for high-bandwidth events and edge analytics.
Recent Industry Developments in Wireless Infrastructure Monitoring Market
- June 2026: Monnit introduced NIST-traceable detachable leads for ALTA sensor bases to simplify compliance monitoring workflows and improve serviceability in the field. The product targets regulated and audit-driven deployments where traceability and faster maintenance reduce downtime and operating burden across distributed sensor fleets.
- November 2025: Sisgeo integrated its geotechnical instrumentation with Senceive wireless monitoring systems within the Eddyfi Remote Monitoring Solutions group, positioning a more unified offering for automated dam and geotechnical monitoring. The move strengthens end-to-end delivery by linking instruments, wireless transmission, and remote analytics under a single solutions umbrella.
- April 2024: Acellent secured a contract with Korea Aerospace Industries to supply structural health monitoring systems for KF-21 fighter aircraft production. The program win reinforces demand for high-reliability wireless and sensor-driven monitoring in mission-critical structures, helping validate SHM architectures and workflows that can transfer into broader infrastructure monitoring applications.


Wireless Infrastructure Monitoring Market Report Scope and Research Methodology
Market Definition and Coverage
This market counts revenues earned from solutions that use wireless sensors and connectivity to track the condition and performance of physical infrastructure. It also covers tools that help users detect risks, plan maintenance, and reduce unplanned outages through monitoring and alerts.
Scope exclusions: We exclude wired only monitoring setups and general construction work that does not involve ongoing wireless monitoring revenue.
Segments Covered in This Report
- By Component
- Hardware
- Sensors
- Data Acquisition Systems
- Gateways and Comms Devices
- Software
- Services
- Hardware
- By Connectivity Technology
- Wi-Fi
- Bluetooth
- Zigbee
- Cellular (3G/4G/5G)
- LPWAN (LoRa, Sigfox, NB-IoT)
- Satellite and Other Connectivity Technologies
- By Application
- Structural Monitoring
- Geotechnical Monitoring
- Environmental Monitoring
- Seismic and Vibration Monitoring
- Corrosion Monitoring
- Other Specialized Applications
- By Infrastructure Type
- Bridges and Tunnels
- Buildings and Commercial Structures
- Dams and Water Infrastructure
- Oil and Gas Pipelines and Refineries
- Power Plants and Energy Facilities
- Transportation Infrastructure (Rail, Roads, Airports)
- Mining Sites
- Renewable Energy Assets (Wind, Solar)
- By Sensor Type
- Strain and Stress Sensors
- Displacement and Deflection Sensors
- Accelerometers and Vibration Sensors
- Temperature and Humidity Sensors
- Inclination and Tilt Sensors
- Other Sensor Types
- By End-user
- Civil Infrastructure Owners and Operators
- Oil and Gas Companies
- Utilities and Energy Companies
- Transportation Authorities
- Mining Companies
- Government and Defense
- Other End-users
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Nordics
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia
- New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- Turkey
- Israel
- South Africa
- Nigeria
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk research started with public information that helps explain where monitoring demand comes from and how fast infrastructure owners are investing in upgrades. We referred to sources such as the US Federal Highway Administration for bridge condition context, US Geological Survey materials for monitoring use cases, and National Institute of Standards and Technology publications that touch on sensing and measurement practices.
To make the model practical, we also used materials such as IEEE journal papers on wireless sensor networks, World Bank infrastructure and investment indicators, and standards and guidance published by civil engineering associations. Company filings, investor presentations, and reputable press coverage were reviewed to understand product direction, typical pricing logic, and how services are being bundled with hardware. Where needed, a paid subscription focused on company financials and a patent database were used to validate revenue exposure and technology activity. These are illustrative examples, and many other public sources were reviewed to collect data, cross-check assumptions, and clarify open questions.
Primary Interviews and Surveys
Primary work focused on speaking with practitioners who specify, deploy, or operate wireless monitoring for bridges, buildings, energy and industrial sites, and transport assets. The goal was to confirm what is actually purchased and how projects scale after pilots, not just what vendors claim. Inputs from system integrators, infrastructure owners, and sensor and platform specialists were used to test adoption pacing, typical replacement cycles, and the share of spend that flows to software and ongoing services across APAC, EMEA, and the Americas.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 13% | APAC: 43% |
| Mid tier: 56% | Functional/Unit leaders: 34% | EMEA: 32% |
| Smaller Players: 14% | Managers: 53% | Americas: 25% |
Market-Sizing & Forecasting
Sizing followed a top-down and bottom-up approach. First, infrastructure monitoring spend pools were reconstructed using indicators tied to asset health programs, retrofit activity, and ongoing wireless monitoring adoption. Then, we cross-checked the totals using selective supplier and channel approximations. For the top-down build, we leaned on signals such as infrastructure rehabilitation budgets, the installed base of monitored assets, typical sensor density per asset type, and the mix shift toward analytics and managed monitoring, which tends to lift recurring revenue.
Those totals were then pressure-tested through bottom-up checks, including sampled average selling prices for sensor nodes and gateways, estimated project volumes from integrators, and software and services attach rates discussed in interviews. When bottom-up visibility was limited for a given use case, we applied conservative ranges for pricing and deployment scale, then narrowed them using what buyers said they approve and renew.
Forecasting relied mainly on scenario analysis, because adoption depends on procurement timing and asset safety priorities that can move year to year. We built base, slower, and faster adoption paths using inputs such as public infrastructure funding direction, wireless connectivity readiness, and the pace of moving from pilots to networked rollouts. The final forecast was aligned to consensus ranges heard from field discussions.
Data Validation & Update Cycle
Outputs were checked against independent signals, including infrastructure investment direction, observed growth in monitoring programs, and the implied spend per monitored asset, so the total does not drift away from real purchase behavior. Outliers were flagged when pricing, penetration, or regional splits moved outside what interviews and public references typically support, and assumptions were revisited before sign-off.
Each report is refreshed annually, and interim updates are made when material changes affect demand or supply conditions in a visible way. Before delivery, we complete a final review pass and re-check key inputs so clients receive an updated view that keeps the same repeatable logic.
黑料不打烊's Wireless Infrastructure Monitoring Market Estimate Compared With Other Published Estimates
Published market sizes for wireless infrastructure monitoring often differ because the category is easy to extend into adjacent areas, and because pricing and service inclusion can change the total quickly. The spread usually comes from how firms treat software and services, which end users are counted, and whether the numbers reflect a steady base case or a more aggressive adoption curve.
The main gap comes from including broader smart city sensing and general IoT platform revenue. 黑料不打烊 counts only wireless monitoring tied to infrastructure condition and related monitoring software and services, not unrelated IoT applications, which keeps the total anchored to asset monitoring demand.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 4.72 B (2025) | |
| Industry Publisher A | USD 5.49 B (2025) | Uses a wider basket that can fold in adjacent IoT platform and smart city sensing revenues, which inflates totals beyond infrastructure condition monitoring use cases. |
| Engineering Trade Journal B | USD 4.11 B (2024) | Anchors on an earlier year and tends to emphasize device shipments, which can undercount recurring software, analytics, and monitoring services that build after deployment. |
The benchmark comparison shows that most differences can be traced back to what gets bundled into the market and how recurring revenue is treated over time. By keeping the scope tied to infrastructure condition monitoring and then validating pricing and attach rates through interviews, the resulting number is easier to reconcile with real deployments and consistent year-over-year measurement.


Key Questions Answered in the Report
What is the current value of the wireless infrastructure monitoring market?
The market stands at USD 5.32 billion in 2026 and is projected to reach USD 9.69 billion by 2031 at a 12.74% CAGR.
Which region leads the wireless infrastructure monitoring market?
Asia Pacific holds the leading 28.34% revenue share due to extensive infrastructure expansion and smart-city initiatives.
Why are services growing faster than hardware in this market?
Asset owners seek predictive insights and uptime guarantees, making managed analytics and optimization services more valuable than standalone sensors.
What connectivity technology is most widely used?
LPWAN accounts for 37.22% of connectivity revenues, although 5G solutions are growing rapidly for high-bandwidth use-cases.
Which application segment is expanding the quickest?
Corrosion monitoring posts the highest 13.98% CAGR as offshore wind and marine assets require early detection of material degradation
How do data-sovereignty rules affect deployments in the Middle East?
In 2024, the Wireless Infrastructure Monitoring Market size was estimated at USD 4.11 billion. The report covers the Wireless Infrastructure Monitoring Market historical market size for years: 2019, 2020, 2021, 2022, 2023 and 2024. The report also forecasts the Wireless Infrastructure Monitoring Market size for years: 2026, 2027, 2028, 2029, 2030 and 2031.
Page last updated on:



