
Human Resource Consulting Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 84.58 Billion |
| Market Size (2031) | USD 118.76 Billion |
| Growth Rate (2026 - 2031) | 7.02 % |
| Fastest Growing Market | North America |
| Largest Market | Asia Pacific |
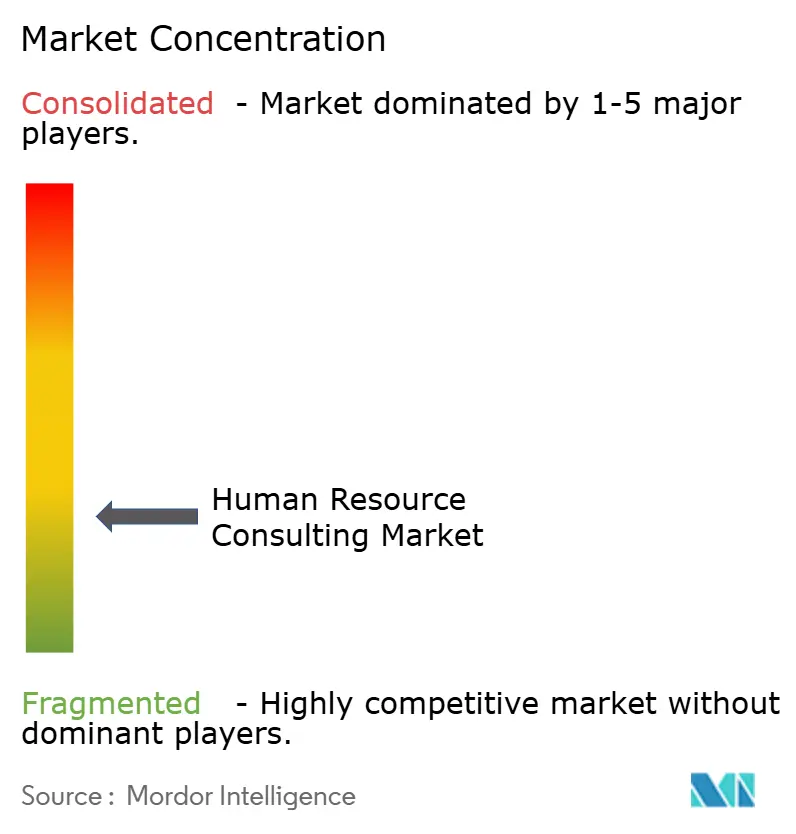
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Human Resource Consulting Market Analysis by 黑料不打烊
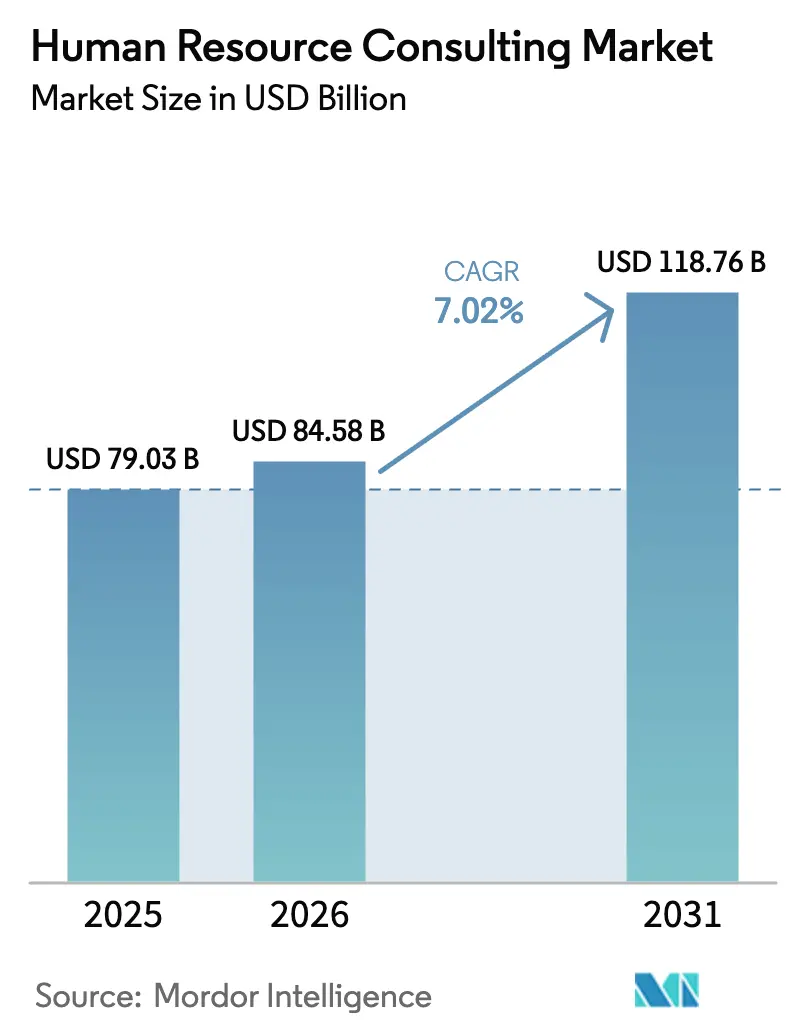
The Human Resource Consulting market size is expected to grow from USD 79.03 billion in 2025 to USD 84.58 billion in 2026 and is forecast to reach USD 118.76 billion by 2031 at 7.02% CAGR over 2026-2031.
The human resource consulting market is benefiting from rapid digital HR-tech adoption, stricter global compliance demands, and the urgent need to redesign work for hybrid models. North America presently anchors the human resource consulting market, yet Asia-Pacific is closing the gap quickly as SMEs digitize HR processes and regional regulators harmonize employment rules. Intensifying M&A activity, deeper analytics penetration, and immersive up-skilling technologies are widening advisory scopes, while commoditization of routine tasks pushes firms toward higher-value engagements. Competition remains moderate because the top-five firms command just one-fourth of the combined revenue, leaving ample white space for niche specialists.
Key Report Takeaways
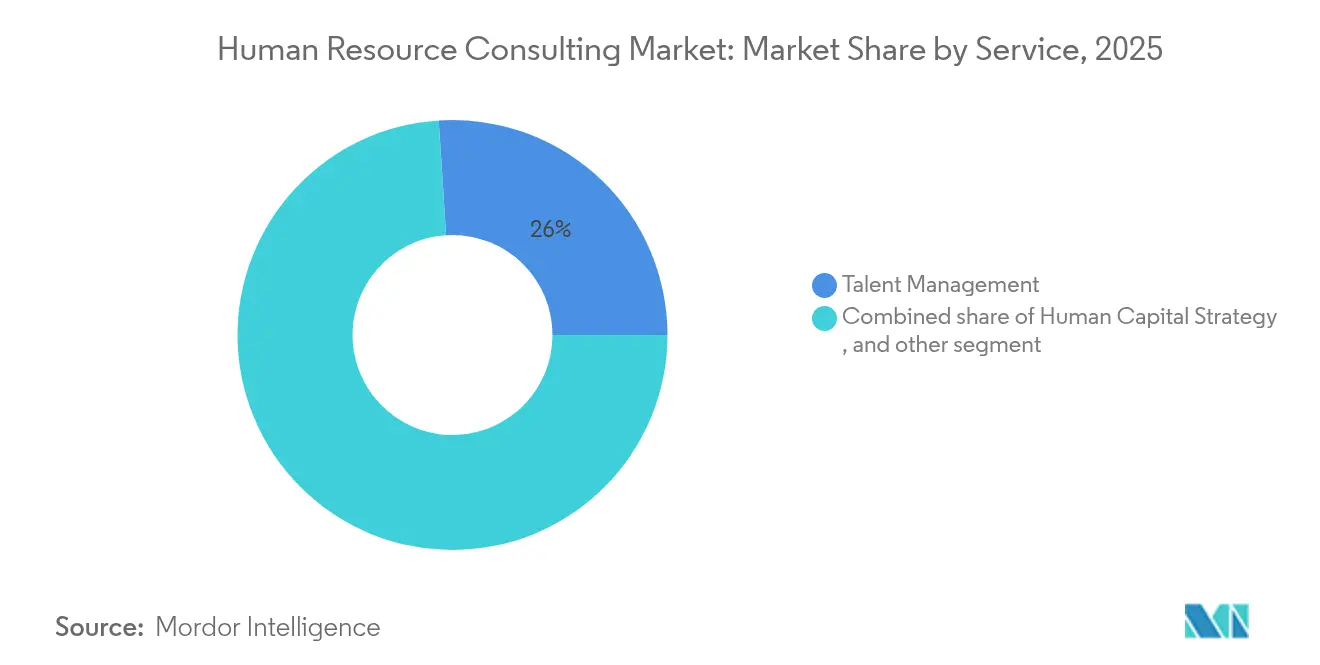
- By service, talent management captured 26.02% of the human resource consulting market share in 2025, whereas HR analytics is projected to grow at a 12.18% CAGR through 2031.
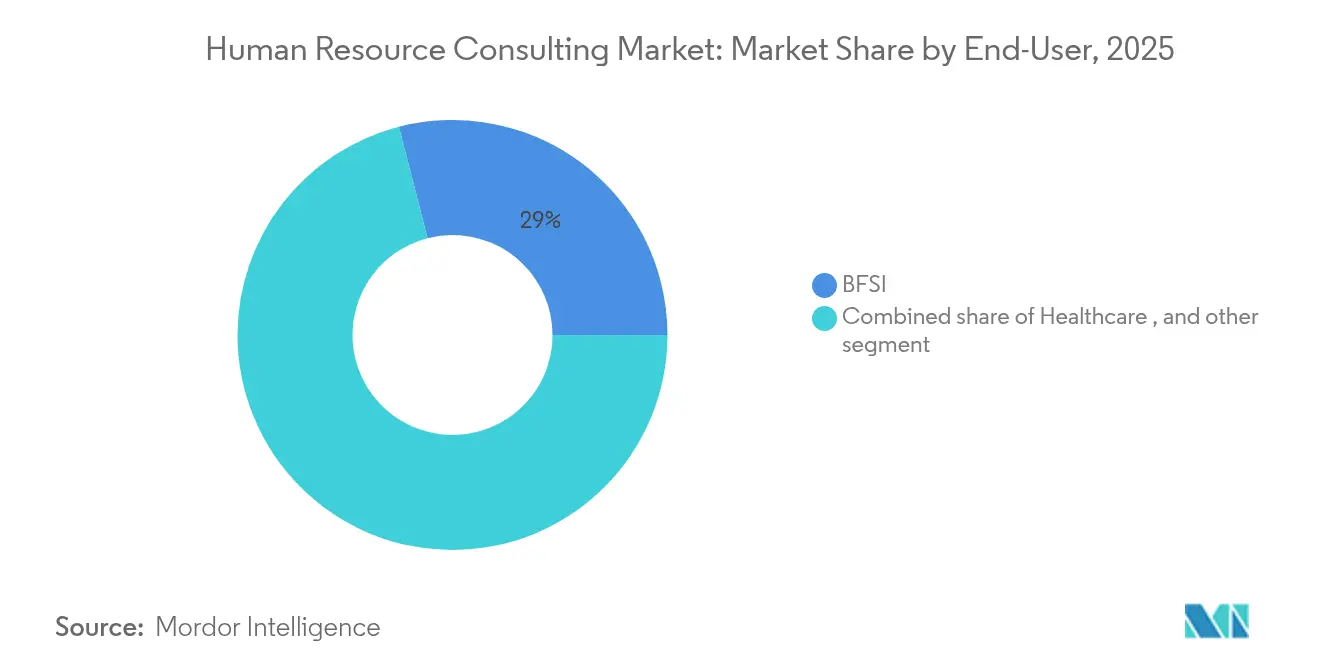
- By end-user, BFSI accounted for a 29.01% share of the human resource consulting market size in 2025, while retail & e-commerce is advancing at a 10.18% CAGR to 2031.
- By organization size, large enterprises held 62.11% share of the human resource consulting market size in 2025, whereas small and medium enterprises are expanding at a 9.25% CAGR through 2031.
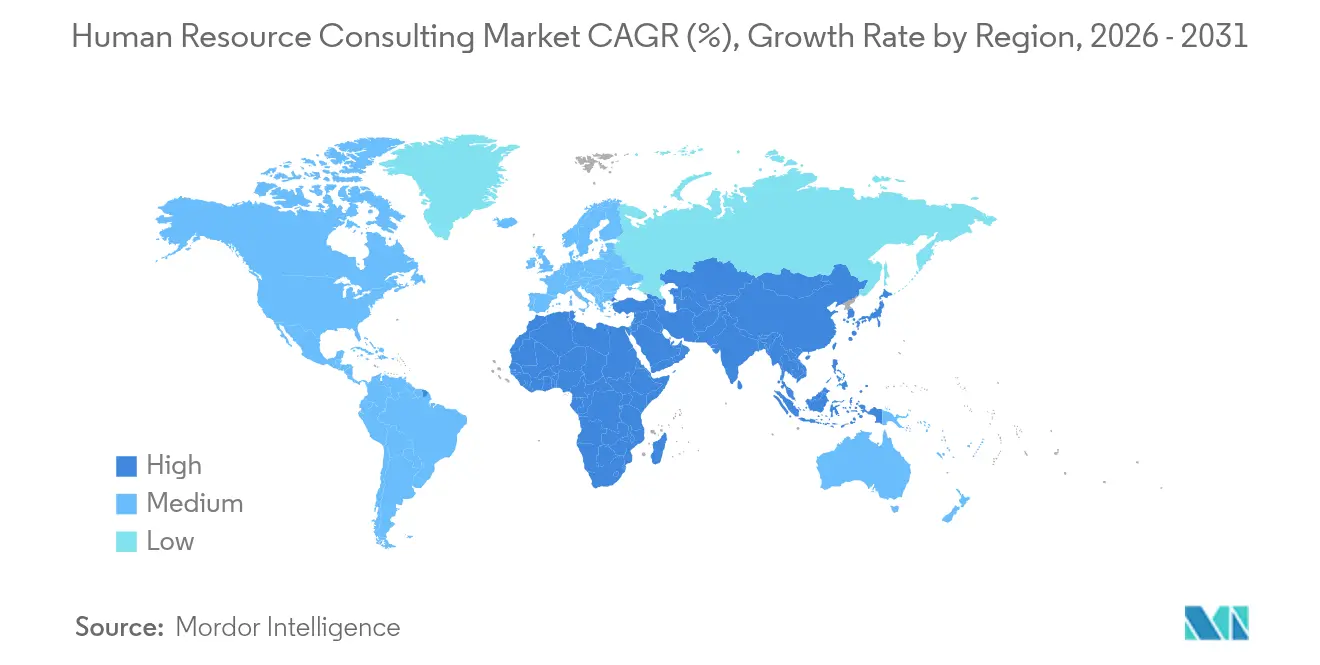
- By geography, North America led with 39.88% of the human resource consulting market share in 2025, and Asia-Pacific is projected to post an 8.78% CAGR to 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of Human Resource Consulting Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Digital HR-tech adoption & analytics integration | +2.1% | Global, APAC leading adoption | Medium term (2-4 years) |
| Regulatory complexity (DEI, pay transparency, ESG) | +1.8% | North America & EU, expanding globally | Long term (≥ 4 years) |
| Hybrid/remote work transformation needs | +1.4% | Global, developed markets | Short term (≤ 2 years) |
| M&A-led organizational restructuring wave | +1.2% | North America & Europe, APAC emerging | Medium term (2-4 years) |
| SME accelerator programs in emerging markets | +0.8% | APAC core, MEA & South America | Long term (≥ 4 years) |
| Immersive XR-based workforce up-skilling demand | +0.6% | North America & Europe, APAC following | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Digital HR-tech Adoption & Analytics Integration
Companies worldwide are embedding AI, machine learning, and predictive analytics in people processes, which raises the bar for data-driven workforce decisions. Advisory demand spikes when leadership teams lack internal capability to translate data signals into actionable talent strategies, a gap that only 21% of HR heads believe they have bridged [1]Charlotte Duerden, “Understanding and Preparing for the Rise in Pay Transparency,” Aon, aon.com . The shift from on-premises suites to cloud HCM and point-solution ecosystems is generating sizeable implementation and change-management opportunities for consultancies. In the Asia-Pacific region, first-time buyers among SMEs accelerate platform rollouts, extending the human resource consulting market footprint in tier-two cities. Consultants increasingly bundle managed analytics services with training so clients can self-serve dashboards, yet still buy strategic insight. Organizations that have leveraged analytics to enhance retention times demonstrate measurable financial gains while reinforcing enduring advisory relationships. These success stories underscore the strategic value of data-driven decision-making in fostering customer loyalty and driving sustainable business growth.
Regulatory Complexity (DEI, Pay Transparency, ESG)
A fast-evolving rulebook covering equal pay, inclusive hiring, and sustainability disclosure is reshaping the human resource consulting market across mature and emerging economies. The EU Pay Transparency Directive obliges companies to publish gender pay-gap metrics, while several U.S. states enforce salary-range postings, nudging global multinationals toward rigorous audit programs. Heightened scrutiny by investors and regulators on human-capital metrics in 10-K filings fuels consulting around data collection and narrative design. HR teams must also align with the EU AI Act’s human-in-the-loop safeguards for algorithmic hiring, a requirement propelling demand for specialized risk reviews [2]Gartner Research Team, “Talent Analytics | HR Insights,” Gartner, gartner.com . Because legislatures revise statutes frequently, forward-looking clients engage external partners on ongoing retainer models rather than one-off gap assessments.
Hybrid/Remote Work Transformation Needs
Hybrid work is now standard practice in developed economies, but many employers still grapple with productivity baselines, culture cohesion, and equitable career paths for remote staff. By 2029, the total rewards expenditure is anticipated to witness significant growth as organizations increasingly focus on customizing benefits to meet the needs of geographically dispersed teams. This trend highlights an escalating requirement for advanced expertise in compensation strategies and effective communication frameworks to address evolving workforce dynamics. Advisory assignments now extend beyond technology deployment to redesigning performance frameworks that prioritize outcomes over hours logged. Firms are commissioning consultants to integrate deskless workers into digital HR environments through mobile-first tools that elevate frontline engagement. Early adopters report measurable gains in retention and well-being, underscoring the necessity for structured change-management playbooks. As hybrid norms stabilize, transformation roadmaps drive a 1.4% positive impact on the human resource consulting market trajectory.
M&A-led Organizational Restructuring Wave
Deal volumes rebounded in 2024 and are forecast to climb further, particularly across healthcare, technology, and government services verticals. Misalignment of culture post-deal remains the top value-erosion risk, prompting acquirers to bring in HR consultants for integration blueprints from day one. Retention payments, now equivalent to the base pay for critical roles, have introduced additional layers of complexity to organizational compensation structures. This development underscores the growing reliance on experienced advisers to navigate and manage these intricate programs effectively. Cross-border transactions magnify regulatory and benefits harmonization challenges, amplifying the human resource consulting market demand in multilingual jurisdictions. Successful integrations that preserve talent synergies become case studies, reinforcing advisory ROI narratives. Consequently, deal-related work contributes an additional 1.2% to the sector’s forecast CAGR.
Restraints Impact Analysis of Human Resource Consulting Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Commoditization of routine HR advisory tasks | -1.3% | Global, mature markets | Medium term (2-4 years) |
| In-house HR analytics capabilities rising | -0.9% | North America & Europe, APAC following | Long term (≥ 4 years) |
| Client budget compression during downturns | -0.7% | Global, cyclical | Short term (≤ 2 years) |
| Data-privacy / AI-ethics compliance hurdles | -0.5% | EU leading, global spillover | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Commoditization of Routine HR Advisory Tasks
AI-driven workflow engines now draft policies, draft proposals, and prepare dashboards that junior consultants once produced manually. This automation lowers perceived differentiation for standard deliverables and exerts downward pricing pressure across the human resource consulting market. Established firms respond by pivoting toward premium domains such as AI ethics, climate workforce planning, and cross-border regulatory orchestration. Boutique providers counter by embedding domain IP into subscription software, locking in annuity revenue despite lower ticket sizes. Although strategic work remains insulated, the volume of commoditized tasks reduces the sector CAGR by 1.3% in medium-term forecasts.
In-house HR Analytics Capabilities Rising
Affordable cloud tools combined with growing pools of data scientists enable companies to internalize descriptive and predictive analytics once outsourced. Financial institutions are staffing dedicated analytics pods that deliver near-real-time hiring and attrition insights, shrinking external advisory spend. Yet most enterprises still struggle to benchmark findings against peers, a space where consultants retain value. Providers that reposition as insight interpreters rather than dashboard builders can offset lost volume, but margin compression persists. Over the long horizon, this dynamic subtracts 0.9% from the human resource consulting market CAGR.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Human Resource Consulting Market Segment Analysis
By Service:
Analytics Drives Premium GrowthIn 2025, talent management held the largest slice of the human resource consulting market at 26.02%, reflecting organizations’ urgent need to secure scarce skills and craft succession pipelines. HR Analytics, although representing a smaller base, is on course to expand at a 12.18% CAGR, indicating outsized appetite for data-backed talent strategies. The human resource consulting market size for analytics-related engagements is projected to climb steadily, propelled by clients’ recognition that robust insights cut turnover costs and lift engagement metrics. Compensation & Benefits work is undergoing a redesign as pay-transparency rules force firms into real-time benchmarking, prompting cross-border harmonization projects. Advisory demand in Learning & Development tilts toward immersive formats that capitalize on XR and adaptive learning to shorten skill cycles.
Organizations that integrated predictive models into hiring processes reported time-to-fill reductions of 30%, underscoring analytics’ strategic relevance. Talent Management services remain resilient because evolving skills taxonomies and gig-style labour models complicate workforce planning for even sophisticated HR departments. Meanwhile, Human Capital Strategy projects rise in prominence as clients pursue boundaryless HR operating models that break down silos across finance, IT, and line leadership. Mid-cycle reviews show that only 8% of enterprises rate their analytics muscle as “strong,” unlocking a sizeable advisory backlog. Consequently, service providers that couple domain expertise with scalable tech playbooks is positioned to capture disproportionate value in the human resource consulting market.


By End-User:
Financial Services Lead, Retail AcceleratesBFSI retained 29.01% of the human resource consulting market share in 2025 owing to tight regulatory requirements, rigorous risk cultures, and elevated talent churn in digital banking . The sector remains a bellwether for innovative reward designs, from skills-based pay to location-agnostic salaries, fuelling specialized advisory contracts. Retail & E-Commerce, by contrast, is projected to compound at 10.18% annually through 2031 as omnichannel strategies necessitate rapid workforce adaptation and robust frontline retention programs. Healthcare follows closely, with chronic clinician shortages and stringent accreditation demands creating evergreen consulting needs.
Financial institutions increasingly experiment with AI-driven talent marketplaces to redeploy under-utilized employees, further diversifying consultant mandates. Retailers channel investments into employee-experience analytics to tame attrition spikes after seasonal peaks, an emerging hotspot for algorithmic scheduling projects. Healthcare providers require nuanced workforce planning that accounts for immigration constraints, gig nursing pools, and escalating credentialing audits, amplifying advisory complexity. IT & Telecom clients mix digital-skills up-skilling with remote-work governance frameworks, generating hybrid project portfolios. Collectively, end-user heterogeneity compels consultants to maintain deep sector verticalization strategies to remain competitive in the human resource consulting market.
By Organization Size:
SME Segment EmergesLarge enterprises still dominate spending with a 62.11% revenue contribution in 2025, driven by their broad transformation agendas and geographic footprints. Yet SMEs are the fastest-growing cohort at 9.25% CAGR because public grants and low-cost SaaS platforms lower engagement barriers. The human resource consulting market size attributable to SMEs is poised to widen as these firms formalize HR processes to attract skilled labour against larger competitors. Medium Enterprises bridge the gap, demanding modular, scalable solutions that can be switched on without extensive change-management overhead.
SME buyers value practical toolkits and local compliance insight over multi-year strategic roadmaps, prompting consultants to tailor “lite” offerings delivered via subscription. Government programs such as ASEAN digital vouchers subsidize first-year advisory fees, accelerating contract momentum. Large Enterprises, meanwhile, engage consultants for sophisticated analytics, global mobility, and ESG-linked reward structures. This bifurcation forces service providers to adopt tiered go-to-market models that serve both mass and enterprise segments without diluting brand equity. Ongoing SME penetration is projected to reshape the revenue mix across the human resource consulting market by the close of the decade.

Geography Analysis
North America Human Resource Consulting Market
North America’s 39.88% human resource consulting market share in 2025 underscores its status as the sector’s most mature region, supported by advanced analytics adoption and comprehensive pay-transparency statutes. Advisory pipelines focus on AI governance, sustainability workforce planning, and total-rewards personalization, although federal budget tightening has tempered short-term growth. Canadian and Mexican demand rises on the back of cross-border labour-mobility programs under USMCA, adding regional nuance to talent-strategy projects. Providers are differentiating through proprietary AI accelerators targeted at regulated industries, reinforcing North America’s premium-pricing profile. Despite near-term softness, the region’s high client sophistication ensures sustained long-run relevance for the human resource consulting market.
Europe Human Resource Consulting Market
Europe represents a multifaceted opportunity, buoyed by sweeping regulatory changes such as the EU AI Act and Pay Transparency Directive that generate consistent compliance work. In 2025, several countries introduced fresh protections, from Germany’s whistle-blower reforms to the Netherlands’ disability-hiring incentives, intensifying localization needs. Nordic and BENELUX clients emphasize ESG-linked pay, driving sophisticated reward-strategy projects, while Southern Europe prioritizes digital workforce transformation for mid-cap firms. M&A activity rebounded sharply, sparking post-deal integration assignments centred on cultural harmonization and leadership retention. Aging demographics across Western Europe further boost succession-planning mandates, reinforcing the human resource consulting market outlook.
APAC Human Resource Consulting Market
Asia-Pacific, projected to register an 8.78% CAGR, remains the engine of future expansion for the human resource consulting market, propelled by MSME digitalization programs and rising cross-border trade. Southeast Asia’s HCM software boom leads to strong implementation and managed-services contracts for local and global advisers . China and India anchor scale projects, ranging from AI-enabled recruitment to regulatory remediation, while Australia and Japan invest heavily in analytics centers of excellence. Government funds targeting SME capability building spread advisory demand into second-tier cities, creating new client pools. These dynamics position Asia-Pacific to challenge Western dominance and redefine global revenue shares before 2030.

Regulatory Landscape
Regulation affecting the human resource consulting market is increasingly anchored in pay transparency, AI and automated decision-making oversight, and evolving worker classification and wage-hour standards across major economies. In Europe, the EU Pay Transparency Directive shifted into national implementation activity from June 2026, expanding the need for pay-gap measurement, remediation governance, and documentation across multinational workforces. In the United States, the Department of Labor signaled renewed attention to employment-status and responsibility frameworks through an April 23, 2026 Notice of Proposed Rulemaking to create a unified joint employer standard spanning the FLSA, FMLA, and MSPA. A June 2026 technical amendment by the Wage and Hour Division restored 2024 exempt-status overtime standards following a court decision.
Data privacy and algorithmic fairness requirements are also shaping consulting scopes, particularly for HR analytics and AI-enabled hiring. California Consumer Privacy Act automated decision-making rules became effective January 1, 2026, pushing employers to formalize how they use and explain automated tools in HR processes. At the state level, Colorado SB 24-205 (AI Act) was amended toward a transparency framework effective January 1, 2027, reinforcing a move beyond one-time compliance checks toward ongoing control design, audits, and disclosure readiness across HR technology stacks.
Value Chain Analysis
The human resource consulting value chain runs from diagnosis and strategy (workforce and operating-model design), to solution build (HR technology selection, implementation, and integration), and then to run and optimize delivery through managed services and continuous improvement. At the front end, consultancies convert business priorities into talent, rewards, and organization design roadmaps, and they support change management and capability building to drive adoption. In the build phase, firms deliver cloud HCM transformations through alliances and certified practices around major platforms, while increasingly bundling data engineering and analytics to support workforce insights.
Downstream, vendors are moving toward recurring delivery through Operate and Human Capital as a Service models, combining application management, HR process operations, and governance with embedded automation. Large global firms such as Deloitte, Accenture, PwC, Mercer, and Aon anchor this end-to-end chain by pairing advisory with implementation and ongoing operations, while boutiques compete by productizing domain IP into repeatable toolkits and subscription-like delivery. Data privacy, cybersecurity controls, and localized employment-law interpretation act as cross-cutting enablers, especially for cross-border workforce data programs and regulated end users such as BFSI.
Competitive Landscape
The human resource consulting market remains moderately fragmented. Market leaders differentiate through multibillion-dollar AI investments and proprietary platforms that automate low-value tasks, freeing consultants to focus on strategic advisory. Deloitte’s HR Cloud Operate couples application management with functional optimization, reinforcing stickiness well beyond system go-lives. McKinsey and other strategy houses embed generative AI to accelerate diagnostics, but also confront internal efficiency drives and workforce right-sizing.
Boutique specialists thrive by combining deep sector knowledge with technology-driven delivery at lower price points, filling gaps left by large players. Willis Towers Watson revived legacy sub-brands to sharpen go-to-market clarity and partnered with Bain Capital to re-enter treaty reinsurance broking, illustrating niche expansion tactics. Strategic alliances between software vendors and consultancies proliferate, evidenced by SAP’s WalkMe purchase that blends product adoption with advisory change management. Geographic partnerships, like WTW’s tie-up with Al-Futtaim Willis in the Middle East, broaden reach where green-field entry would be costlier.
Pricing models continue to evolve from time-and-materials toward performance-linked structures that align fees with measurable outcomes such as turnover reduction or digital-adoption rates. Clients reward providers able to integrate compliance, analytics, and transformation services under a single governance framework. Cybersecurity and data privacy credentials increasingly serve as competitive differentiators, especially for cross-border talent data projects. The sustained emergence of focused disruptors ensures healthy rivalry and innovation across the human resource consulting market while limiting over-consolidation risk.
Human Resource Consulting Industry Leaders
Deloitte
PwC
Accenture
Aon
Mercer
- *Disclaimer: Major Players sorted in no particular order
Human Resource Consulting Market Companies Covered in this Report
- Deloitte
- PwC
- KPMG
- EY
- McKinsey & Company
- Boston Consulting Group
- Bain & Company
- Accenture
- Mercer
- Aon
- Willis Towers Watson
- Korn Ferry
- Randstad
- Adecco
- Hay Group
- Oliver Wyman
- IBM Consulting
- SAP SuccessFactors Services
- Workday Advisory Services
- Tata Consultancy Services
- Infosys
- Capgemini
- HCLTech

Market Opportunities and Future Outlook
Compliance-led transformation is creating whitespace for specialized advisory tied to pay transparency, AI use in talent decisions, and workforce reporting across jurisdictions. The June 2026 start of EU Pay Transparency Directive implementation activities and the January 1, 2026 effectiveness of California Consumer Privacy Act automated decision-making rules are pushing employers to connect policy, data, and technology controls, lifting demand for integrated programs that combine compensation benchmarking, HR analytics governance, and change management. Alongside this, the April 23, 2026 U.S. Department of Labor proposal to unify joint employer standards is increasing the need for scenario planning and operating-model updates for organizations using contractors, franchises, and multi-entity staffing structures.
Delivery-model opportunity is focused on tech-enabled, recurring services that reduce dependence on one-off projects and help defend margins as routine work is automated. Market evidence includes providers scaling managed offerings such as Deloitte Human Capital as a Service/Operate models and broader industry emphasis on ecosystem partnerships that link consulting delivery to cloud platforms and digital adoption tooling. A second focus area is AI and automated decision-making compliance and assurance, supported by benchmarking that identified AI and automated decision-making compliance as the top emerging trend for 51% of HR professionals over the 12 to 18 months following early 2026. APAC also offers a structural expansion lane for multi-process HR outsourcing and modernization programs as HR tech adoption deepens beyond mature markets, supporting modular engagements for SMEs alongside enterprise-grade transformation work.
Recent Industry Developments in Human Resource Consulting Market
- June 2026: Accenture acquires Industries eXcellence Group (IndX), a Siemens Digital Industries partner, to strengthen manufacturing and supply chain software capabilities. The acquisition expands Accenture's enterprise software and automation footprint in asset-heavy industries, enabling broader HR transformation advisory potential across these sectors.
- June 2026: Accenture invests in and partners with AlphaSense to integrate AI-powered market intelligence into enterprise agentic workflows. The adoption of AI-enabled market intelligence integrated into workflows embeds analytics and market insights into HR cloud operations and change-management offerings.
- May 2026: Accenture completed the acquisition of Verum Partners, an infrastructure and capital projects management firm in Brazil. The move expands capex project delivery capabilities and extends end-to-end delivery for clients undergoing large-scale HR and transformation programs in emerging markets.


Human Resource Consulting Market Report Scope and Research Methodology
Market Definition and Coverage
We define the human resource consulting market as third-party advisory and project-based services that help employers design, change, and run HR policies, programs, and operating models. In this study, revenues are captured as service fees billed to clients.
Scope exclusions: we exclude outsourced HR administration run as a managed service, staffing and recruitment process outsourcing, and HR software license revenue unless it is sold as part of a consulting engagement fee.
Segments Covered in This Report
- By Service
- Human Capital Strategy
- Compensation & Benefits
- Talent Management
- Organizational Change
- Learning & Development
- HR Function
- HR Analytics
- By End-User
- IT & Telecom
- BFSI
- Healthcare
- Retail and E-Commerce
- Other End-Users
- By Organization Size
- Large Enterprises
- Medium Enterprises
- Small Enterprises
- By Geography
- North America
- Canada
- United States
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX
- NORDICS
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South-East Asia
- Rest of Asia-Pacific
- Middle East & Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East & Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk work starts by grounding the demand side and the workforce backdrop that drives consulting spend, then translating that into a service revenue logic. Public sources used for the base include the US Bureau of Labor Statistics for employment and wage signals, the OECD for labor market indicators, the World Bank for macro and services value add context, and the International Labour Organization for workforce structure and participation trends.
We also review company annual reports, SEC filings, and investor presentations to understand how service lines are described, what pricing tends to look like, and where growth is being reported by geography. Reputed press, association websites, and peer-reviewed HR and organizational research are used to sanity check themes like remote work adoption, regulation-driven change, and skills development intensity. A few paid subscriptions are used selectively for company financials and news screening, plus patent and contracts databases when they help confirm consulting demand around analytics and compliance programs. The specific desk sources listed here are illustrative only, and many other public and paid references are used to collect, validate, and clarify data points.
Primary Interviews and Surveys
Primary work focuses on how buyers budget and how providers recognize revenue, since HR consulting is not tracked as a single clean public statistic. We speak with HR leaders, procurement and shared services owners, and consulting delivery managers across APAC, EMEA, and the Americas to confirm service scope boundaries, pricing behavior, and what is being delayed or accelerated in the pipeline.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 35% | CXOs: 15% | APAC: 41% |
| Mid tier: 45% | Functional/Unit leaders: 30% | EMEA: 36% |
| Smaller Players: 20% | Managers: 55% | Americas: 23% |
Market-Sizing & Forecasting
Sizing is built using a top-down approach where the addressable employer spend pool is reconstructed by region, then filtered into HR consulting attach rates by service demand drivers. The model is organized around practical inputs, including total employed workforce, the share of large and mid-sized enterprises, HR spend intensity as a percent of operating cost, consulting penetration by program type, and typical project cycle timing that affects annual revenue recognition.
Those inputs are then pressure tested with selective bottom-up checks so the total does not drift away from reality. We use sampled provider revenue disclosures where available, channel checks on average project fees, and cross-checks of engagement volumes for areas like compensation redesign, change management, learning programs, and HR analytics advisory. When a country level view is thin, we bridge gaps using proxy indicators like GDP per capita, services sector share, and enterprise count bands, and then re-check the outputs with primary feedback before locking assumptions.
For forecasting, scenario analysis is used so growth is not driven by one single macro line item. Baseline, conservative, and upside cases are linked to variables that respondents could speak to with confidence, such as hiring momentum, regulatory change load, M&A-led integration needs, digital HR transformation pace, and wage inflation pressure that triggers compensation projects.
Data Validation & Update Cycle
Validation is done through triangulation across demand indicators, provider commentary, and the internal math checks in the model. We run variance checks by region and by service theme so sudden spikes are explained by a real trigger, such as a regulation wave or a step change in transformation budgets, before estimates move.
Outputs are reviewed in more than one step, with assumptions re-opened when interview feedback or new filings create a mismatch versus the prior view. The report is refreshed annually, and interim updates are completed when material events occur, including large contract awards, restructuring cycles, or clear macro shifts that change consulting budgets. Before delivery, a final analyst pass is completed so the latest public releases and confirmed expert inputs are reflected.
黑料不打烊's Human Resource Consulting Market Estimate Compared With Other Published Estimates
Published market sizes for human resource consulting can vary even when the topic sounds identical, because the counting rules are not always the same. Differences usually come from what is treated as consulting versus outsourcing, whether software and staffing related revenue gets mixed in, and how regions are converted and timed into USD.
By tracking scope gates around advisory project fees, refreshing currency timing assumptions, and checking mix shifts by geography, 黑料不打烊 keeps the estimate tied to HR consulting revenue recognition rather than broader HR services bundles.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 84.58 B (2026) | |
| Global Consultancy A | USD 72.00 B (2026) | Often narrows the scope to HR advisory only and leaves out change, learning, and HR analytics consulting, which reduces the captured revenue pool in multi-service engagements. |
| Industry Tracker B | USD 46.71 B (2026) | Commonly blends a smaller service definition with conservative pricing and slower adoption assumptions, and it may treat multi-year transformation programs as partial year revenue. |
The spread in the table is mainly explained by service boundary choices and by how pricing and program timing are treated in the model. When the scope is kept to consulting fees and then cross-checked with practical demand signals and provider disclosures, the result is easier to reconcile and repeat year after year.


Key Questions Answered in the Report
What is the projected value of global human resource consulting by 2031?
Spending is forecast to reach USD 118.76 billion by 2031, up from USD 84.58 billion in 2026.
Which service area will see the fastest revenue growth through 2031?
HR Analytics leads with a 12.18% CAGR expected between 2026 and 2031.
How fast is Asia-Pacific HR consulting revenue expected to grow?
Asia-Pacific revenue is projected to advance at an 8.78% CAGR over the 2026–2031 period.
Why do BFSI firms rely heavily on external HR consultants?
Tight regulatory requirements and rapid digital-banking transformation create constant needs for compliance, risk, and talent-strategy expertise.
What share of global HR consulting spending comes from large enterprises in 2025?
Large enterprises account for 62.11% of total spending, reflecting their complex multi-country HR needs.
How are top consulting firms staying competitive as routine tasks become automated?
They invest in AI platforms, outcome-based pricing, and niche offerings such as AI ethics and climate workforce planning to preserve value and margins.
Page last updated on:


